
Wearable Medical Devices Market Report Scope & Overview:
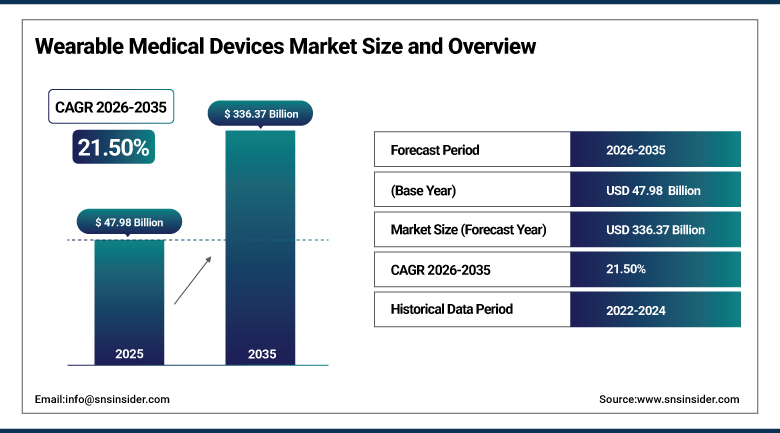
The Wearable Medical Devices Market was valued at USD 47.98 Billion in 2025 and is expected to reach USD 336.37 Billion by 2035, growing at a CAGR of 21.50% from 2026-2035.
The Wearable Medical Devices Market is expanding quickly as continuous health monitoring moves from hospitals into daily life. Glucose sensors, cardiac patches, smartwatches with regulatory clearance and connected insulin systems now generate clinical data around the clock. Chronic disease, an aging population and the push for care at home support steady demand. Reimbursement for remote monitoring is widening access. Artificial intelligence turns raw sensor streams into alerts that clinicians can act on. Smaller sensors and longer battery life improve comfort and adherence. Technology groups and medical device makers are competing for the same users. Regulators are clearing more wearable features each year, and that is expected to sustain double-digit growth.
⮞In January 2026, Abbott reported that its continuous glucose monitoring sales reached about USD 2.0 billion in the fourth quarter of 2025, up 15.0% on a reported basis. The result shows how fast wearable glucose sensing is scaling in routine diabetes care.
To Get more information Wearable Medical Devices Market - Request Free Sample Report
Wearable Medical Devices Market Trends
-
Over-the-counter continuous glucose monitors for people without insulin therapy
-
Smartwatch features cleared by regulators for hypertension, sleep apnea and heart rhythm
-
Automated insulin delivery systems linked to wearable sensors
-
Reimbursed remote patient monitoring programs moving care into the home
-
Artificial intelligence algorithms that convert sensor data into clinical alerts
U.S. Wearable Medical Devices Market Outlook
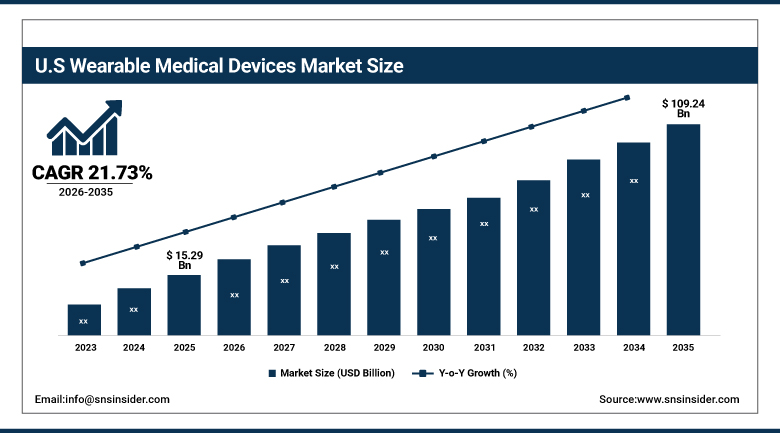
The U.S. Wearable Medical Devices Market was valued at USD 15.29 Billion in 2025 and is expected to reach USD 109.24 Billion by 2035, growing at a CAGR of 21.73% from 2026-2035.
The U.S. Wearable Medical Devices Market is the largest national market, supported by high chronic disease prevalence and strong technology adoption. Millions of adults live with diabetes, hypertension or heart rhythm disorders that need continuous tracking. The Food and Drug Administration is clearing more wearable features each year. Medicare coverage for glucose sensors and remote monitoring is widening access. Technology brands sell directly to consumers, while device makers sell through clinics and pharmacies. Health systems are adding remote monitoring to reduce readmissions. Data privacy duties and device cost remain hurdles. Growth is expected to stay strong as clearances and coverage expand.
⮞The Centers for Disease Control and Prevention reported in 2026 that 40.1 million people in the United States, or 12.0%, had diabetes in 2023, and 27.6% of adults with diabetes were undiagnosed. The scale of the condition shows the size of the population that benefits from continuous monitoring.
Wearable Medical Devices Market Segment Analysis
-
By Product Type, the Diagnostic and Monitoring Devices segment dominated the Wearable Medical Devices Market with approximately 61.15% share in 2025, while the Therapeutic Devices segment is the fastest growing with a CAGR of approximately 23.14%.
-
By Application, the Home Healthcare segment dominated the Wearable Medical Devices Market with approximately 52.98% share in 2025, while the Remote Patient Monitoring segment is the fastest growing with a CAGR of approximately 23.87%.
-
By Grade Type, the Consumer-Grade segment dominated the Wearable Medical Devices Market with approximately 68.17% share in 2025, while the Clinical-Grade segment is the fastest growing with a CAGR of approximately 23.42%.
-
By Distribution Channel, the Pharmacies segment dominated the Wearable Medical Devices Market with approximately 37.53% share in 2025, while the Online segment is the fastest growing with a CAGR of approximately 24.35%.
By Product Type, Diagnostic and Monitoring Devices Dominates the Wearable Medical Devices Market and Therapeutic Devices Grows Fastest
Diagnostic and monitoring devices lead because they serve the widest group of users, from people with diabetes to those at risk of heart rhythm disorders. Continuous glucose monitors, electrocardiogram patches, blood pressure watches and pulse oximeters generate data that doctors use to adjust treatment. Insurers increasingly pay for these devices, which lowers the cost barrier. Wearing the device is less intrusive than clinic visits, so adherence is better. Technology companies add health sensors to mass-market watches, which brings monitoring to millions of new users. These advantages give the segment the largest value share.
Therapeutic devices are growing fastest as wearables move from measuring to treating. Insulin pumps that adjust doses from sensor readings are the clearest example, and wearable neuromodulation, pain relief and respiratory therapy devices are following. Closed-loop systems cut the daily burden of managing diabetes and improve time in range. Regulators are clearing new algorithms and pump features at a steady pace. Pharmacy channel access and pay-as-you-go pricing are widening the user base beyond specialist clinics. Combined sensing and therapy also create recurring revenue from consumables, which attracts investment from device makers and new entrants. Pharmaceutical companies are also exploring wearable delivery for other chronic therapies.
⮞In February 2026, iRhythm reported FY2025 revenue of USD 747.1 million, up 26.2% from USD 591.8 million a year earlier. The growth shows strong demand for wearable cardiac monitoring patches.
By Application, Home Healthcare Dominates the Wearable Medical Devices Market and Remote Patient Monitoring Grows Fastest
Home healthcare leads because patients prefer to manage chronic conditions outside hospitals and health systems want to lower costs. Wearables let older adults and people with long-term illness track vital signs without travel. Glucose sensors, blood pressure monitors and activity trackers are the most common home tools. Caregivers can view readings on a phone and call for help when readings drift. Hospital-at-home programs depend on wearable sensors to track patients after discharge. The shift from episodic visits to continuous monitoring keeps home use ahead of other settings.
Remote patient monitoring is the fastest growing application because payers now reimburse it and clinicians can scale it. Care teams enroll patients with hypertension, heart failure, diabetes and chronic lung disease, then review sensor data and intervene early. Cloud platforms and electronic health record links reduce manual work. Artificial intelligence filters alerts so that nurses focus on patients at risk. Employers and insurers fund programs that cut readmissions and emergency visits. Sports and fitness use remains smaller but is expanding as consumer devices add medically validated features. Athletes and recreational users value recovery and sleep metrics, and clinicians increasingly accept these data points as supporting evidence.
⮞In August 2025, the U.S. Department of Health and Human Services Office of Inspector General reported that Medicare payments for remote patient monitoring exceeded USD 500 million in 2024. The level of spending shows how reimbursement is driving adoption.
By Grade Type, Consumer-Grade Dominates the Wearable Medical Devices Market and Clinical-Grade Grows Fastest
Consumer-grade devices lead because they reach the largest number of buyers through retail and online stores. Smartwatches and rings sell at prices individuals can afford, and they carry sensors for heart rate, oxygen saturation and sleep. Brands such as Apple, Samsung and Google add health features that need no prescription, and many are now cleared by regulators. Large installed bases and app ecosystems give these products an advantage in user engagement. People who first buy a device for fitness then use its health alerts, which blurs the line between wellness and medical use. App ecosystems keep users engaged long after purchase.
Clinical-grade devices are growing fastest because doctors want data they can trust for diagnosis and billing. These devices go through regulatory review, validation studies and quality systems that consumer products often skip. Patches, continuous glucose monitors and ambulatory electrocardiogram monitors are the main products. Prescription use opens reimbursement, and hospitals prefer devices that connect to electronic records. Regulatory actions against unapproved health claims push companies toward formal clearances. Technology brands are partnering with medical device makers to move from wellness features to clinical-grade claims.
⮞In June 2025, Samsung reported that its over-the-counter sleep apnea feature on Galaxy Watch is now available in 70 markets, including 34 in Europe, backed by an FDA De Novo authorization. The reach shows how consumer devices are gaining clinical status.
By Distribution Channel, Pharmacies Dominates the Wearable Medical Devices Market and Online Grows Fastest
Pharmacies are leading the channel evolution because patients are getting their prescriptions there already and pharmacists know how to instruct about using devices. Continuous glucose monitor supplies and insulin pumps are supplied on a monthly basis, which is consistent with the pharmacy channel. The insurance coverage under the pharmacy benefit makes billing easier for consumers. Pharmacy retail chains sell OTC glucose meters and blood pressure monitors and offer health services in-store. Hospital pharmacies provide devices to patients discharging from the hospital with new devices. This makes pharmacies a leading channel, especially for diabetes devices that require periodic supplies. Pharmacist educational programs help in correct usage of the devices and prevent early discontinuation.
E-commerce channels are evolving rapidly as consumers are purchasing devices and subscriptions from manufacturer websites and big marketplaces or telehealth platforms. Direct-to-consumer distribution gives brands the opportunity to manage prices, data, and renewals directly. Subscriptions for glucose sensors and applications generate recurrent revenue. Telehealth visit may result in ordering of a device online and remote consultations. Young generation consumers feel comfortable buying health products using smartphones.
⮞In May 2026, Tandem Diabetes Care reported that it launched a pay-as-you-go model in the U.S. pharmacy channel and shipped more than 29,000 pumps in the first quarter of 2026. The model shows how access routes are being redesigned around the pharmacy counter.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
79.00 |
|
Europe |
Germany |
24.38 |
|
Asia Pacific |
China |
36.47 |
|
Latin America |
Brazil |
45.71 |
|
Middle East & Africa |
Saudi Arabia |
27.64 |
North America Wearable Medical Devices Market Insights
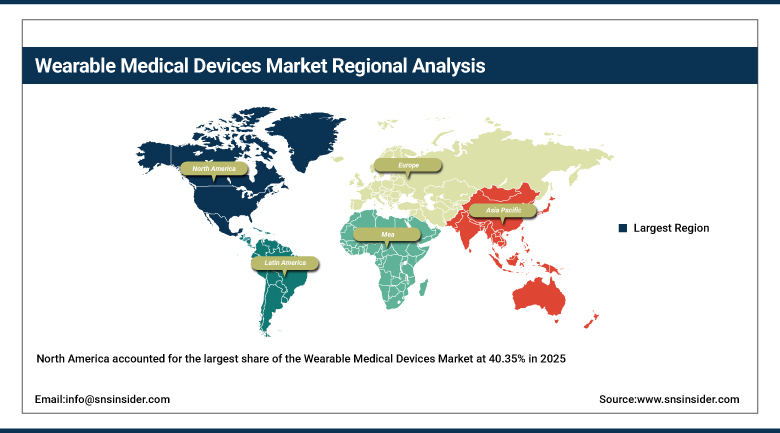
North America accounted for the largest share of the Wearable Medical Devices Market at 40.35% in 2025, led by the United States. High rates of diabetes and heart disease, strong insurance coverage and early adoption of digital health support demand. The region is home to Abbott, Dexcom, Medtronic, Insulet, Tandem, Apple and Google, which compete on sensor accuracy, wear time and software. Canada adds demand through provincial programs for glucose monitoring and a growing base of digital health start-ups. Hospital systems and large employers are also buying wearables for staff and patient programs.
Regulation and payment shape the market. The Food and Drug Administration clears new wearable features through 510(k) and De Novo pathways, and the Centers for Medicare and Medicaid Services decides coverage for sensors and remote monitoring. Warning letters to companies that make unapproved health claims show that oversight is tightening. Cybersecurity and privacy duties add cost for manufacturers. Health systems are building remote monitoring programs, and employers are funding wearables for chronic disease management. Venture funding for sensor and software start-ups remains active, which keeps new entrants coming to market.
⮞In February 2026, Medtronic reported that Medicare and Medicare Advantage beneficiaries can now access the MiniMed 780G insulin system with the Abbott Instinct sensor, which wears for up to 15 days. The coverage expansion adds a large group of older users to the wearable base.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Wearable Medical Devices Market Insights
Europe is the second largest region and is led by Germany, the United Kingdom, France, Italy and Spain. An aging population and high diabetes prevalence create steady demand for glucose, cardiac and blood pressure wearables. National health systems increasingly reimburse continuous glucose monitoring, and Germany's digital health applications pathway supports prescribed software linked to devices. European firms such as Roche, Philips and Withings sell clinical and consumer products across the region. Public tenders for glucose monitoring supplies give large suppliers steady volume.
The Medical Device Regulation sets a high bar for evidence and post-market surveillance, which slows launches but builds clinician trust. CE marking opens many markets at once, and companies often launch in Europe before the United States. Procurement rules differ by country, and reimbursement varies widely between the Nordic markets and southern Europe. The General Data Protection Regulation limits how health data may be processed. Remote monitoring pilots in Germany, the United Kingdom and the Netherlands are broadening use beyond diabetes. Cardiac and respiratory programs are adding wearables to routine follow-up, and hospital groups are testing home recovery pathways.
⮞In January 2026, Senseonics reported that it received the CE Mark for Eversense 365, a one-year implantable glucose monitor, and said the approval adds more than 30 million people with diabetes to its addressable market. The approval shows how European clearance supports long-wear sensor products.
Asia Pacific Wearable Medical Devices Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 22.30% during 2026-2035. China, Japan, India, South Korea and Australia lead regional demand. The region has the largest number of people with diabetes, and rising incomes and urbanization are lifting health spending. Local brands such as Huawei and Xiaomi sell health-tracking watches at lower prices, while Samsung, Apple and Garmin hold premium positions. Japan and South Korea are mature markets with strong medical device regulation. Telecom operators and insurers in the region also bundle devices with health plans to build user bases.
Awareness and reimbursement are still uneven, and many users pay out of pocket. Governments in China and India are promoting digital health platforms and home care, and online retail channels reach cities quickly. Local manufacturing of sensors and patches is rising, which lowers prices. Regulators in Japan, South Korea and Australia are building approval routes for software and wearable devices. International sensor makers are planning launches across the region and building distribution partnerships with local diabetes clinics and pharmacy chains. Medical tourism hubs such as Singapore and Thailand add demand for advanced monitoring in private hospitals.
⮞In June 2026, Dexcom announced that its Stelo glucose biosensor will launch in the United Kingdom, Australia, New Zealand and South Korea starting later in 2026. The plan shows how over-the-counter sensors are being taken into Asia Pacific markets.
MEA & Latin America Wearable Medical Devices Market Insights
In Latin America, Brazil is the largest market, followed by Mexico, Argentina and Colombia. Rising smartphone use and a growing middle class support sales of smartwatches and fitness bands with health features. Diabetes and hypertension rates are high, and public health systems are expanding glucose monitoring for insulin users. Import dependence exposes prices to currency swings, and regulators are tightening checks on health claims made by consumer devices. Private hospital chains in Brazil and Mexico are adding remote monitoring for cardiac and diabetes patients, and local distributors are widening pharmacy coverage.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Israel and South Africa lead demand. Gulf governments are investing in digital health and chronic disease programs, and international sensor and pump makers are launching products there. Awareness is lower in much of Africa, and cost and limited insurance coverage restrain growth. Online retail and telehealth services are widening access in large cities, and local distributors are building training programs for clinics and pharmacies. International manufacturers are signing distribution agreements to reach private hospital networks and pharmacy chains across the Gulf and southern Africa.
⮞In August 2025, Brazil's health regulator Anvisa banned the sale of the GlicoWatch smartwatch, which claimed to measure glucose and blood pressure without proven efficacy. The action shows regulators enforcing clinical evidence standards for wearable health claims.
Market Dynamics
Growth Drivers: Chronic Disease Burden and Reimbursed Home Monitoring Drive Growth in the Wearable Medical Devices Market
Chronic disease prevalence is the main source of demand. Diabetes, hypertension and heart rhythm disorders need continuous tracking, and wearables provide readings that clinics cannot capture during short visits. Older adults want to remain at home, and caregivers use shared dashboards to follow trends. Better sensor accuracy and longer wear time reduce user burden. Insulin dosing linked to sensor data improves outcomes and gives patients a reason to stay on the device over years. Real-world data from large user groups also helps companies refine algorithms and prove value to payers.
Reimbursement and technology advances add momentum. Payers now cover glucose sensors for more patients, and remote monitoring codes pay care teams for time spent reviewing data. Artificial intelligence turns noisy signals into reliable alerts and supports early detection of atrial fibrillation, sleep apnea and hypertension. Smaller chips and low-power connectivity make new form factors possible, including rings, patches and earbuds. Technology brands bring health sensors to large consumer bases, which lowers acquisition cost for medical features. Telehealth platforms also add sensor-based visits, which keeps patients connected to care teams between appointments.
⮞The World Health Organization reported in September 2025 that about 1.4 billion adults aged 30 to 79 had hypertension in 2024, and about 44% were undiagnosed. The number of undiagnosed patients shows the opportunity for continuous blood pressure wearables.
Restraints: Privacy Duties and Regulatory Scrutiny Restrain Growth in the Wearable Medical Devices Market
The duties of maintaining data privacy and security are costly and risky. The wearables gather health data constantly and this data needs to be collected and communicated to health care providers while being protected from breaches. Regulations like HIPAA in the United States or GDPR in Europe are strict and have severe fines. People do not like to share their information with advertisers or employers and a breach of health data from the Internet of Things devices will cause them a lot of trouble. Small companies cannot afford the security and legal department like big tech companies do. International data transfer is another difficulty as well as for the companies selling products in different territories.
Sensor, batteries and microchips will eventually become obsolete and require replacing, thus increasing the price in the long term. The reimbursement of fitness trackers and smartwatches is not widely available. Regulators are fighting with unauthorized claims on medical purposes and sensor malfunctions can create a negative impact on consumer behavior. Tariffs on semiconductors and electronics increase the cost of production. Poor insurance coverage in some regions also limits accessibility of wearable technologies among the population.
⮞In July 2025, the U.S. Food and Drug Administration issued a warning letter to Whoop stating that its Blood Pressure Insights feature is an unauthorized medical device. The letter shows tighter scrutiny of health claims made by consumer wearables.
Opportunities: Over-the-Counter Sensors and AI-Enabled Care Create Opportunities in the Wearable Medical Devices Market
OTC sensing attracts a new consumer segment. OTC glucose biosensor devices enable those with pre-diabetic condition, weight loss or sports purposes to monitor their metabolism. Blood pressure, sleep apnea, and heart rate sensors available in smartwatches become screening tools for the consumers. Subscription-based business model is possible by offering health coaching and data analysis to generate recurring revenues. Wellness plans provided by employers and insurance companies are currently being explored for paying for the approved devices. Collaboration of technology companies with medical device manufacturers will bring validation and accelerate entry into the market for consumer brands.
AI and emerging markets provide additional opportunities for growth. AI will help in predicting glucose level fluctuations, identifying heart arrhythmias at an earlier stage and creating custom care plans. Distribution channels through pharmacy chains and online retailers reach the consumer who is not visiting specialists regularly. Emerging countries such as India, China, Brazil and Gulf region have high patient base but low penetration levels. Pay-per-use or subscription models negate the initial cost barrier. Child and elder patient segments are less catered to where custom-designed devices have an opportunity to gain a customer base.
⮞Beta Bionics reported in April 2026 that first quarter net sales were USD 27.6 million, up 57%, and that its pharmacy channel grew 181%. The pharmacy growth shows how simpler access routes can widen the market for wearable therapy.
Recent Developments:
-
In February 2025, Google announced that the U.S. Food and Drug Administration cleared Loss of Pulse Detection on Pixel Watch 3. The feature can alert emergency services when a user loses consciousness with no pulse, and the U.S. rollout began at the end of March 2025.
-
In September 2025, Apple announced hypertension notifications for Apple Watch Series 9 and later and Ultra 2 and 3. The feature was validated in a study of more than 2,000 participants, and the company expects to alert over one million people in its first year.
-
In November 2025, Withings announced FDA clearance of BeamO, a handheld device that combines an electrocardiogram, a digital stethoscope and a thermometer. The product went on sale at USD 249.95 and brings multi-parameter checks into the home.
-
In December 2025, Insulet announced FDA 510(k) clearance of Omnipod 5 algorithm enhancements, including a new 100 mg/dL glucose target. The update gives users tighter control and was expected to reach U.S. customers in the first half of 2026.
Wearable Medical Devices Market Key Players
-
Abbott Laboratories
-
Dexcom, Inc.
-
Medtronic plc
-
Insulet Corporation
-
Tandem Diabetes Care, Inc.
-
Beta Bionics, Inc.
-
Senseonics Holdings, Inc.
-
iRhythm Technologies, Inc.
-
Apple Inc.
-
Samsung Electronics Co., Ltd.
-
Google LLC (Fitbit)
-
Withings
-
Koninklijke Philips N.V.
-
Biotricity, Inc.
-
BioIntelliSense, Inc.
-
Garmin Ltd.
Wearable Medical Devices Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 47.98 Billion |
| Market Size by 2035 | USD 336.37 Billion |
| CAGR | CAGR of 21.50% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Diagnostic and Monitoring Devices and Therapeutic Devices) • By Application (Home Healthcare, Remote Patient Monitoring, and Sports and Fitness) • By Grade Type (Consumer-Grade and Clinical-Grade) • By Distribution Channel (Pharmacies, Online, Hypermarkets and Supermarkets, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Abbott Laboratories, Dexcom, Inc., Medtronic plc, Insulet Corporation, Tandem Diabetes Care, Inc., Beta Bionics, Inc., Senseonics Holdings, Inc., iRhythm Technologies, Inc., Apple Inc., Samsung Electronics Co., Ltd., Google LLC (Fitbit), Withings, Koninklijke Philips N.V., Biotricity, Inc., BioIntelliSense, Inc., Garmin Ltd. |

Frequently Asked Questions
Key players include Abbott Laboratories, Dexcom, Medtronic, Insulet, Tandem Diabetes Care, Beta Bionics, Senseonics, iRhythm Technologies, Apple, Samsung Electronics, Google (Fitbit), Withings, Koninklijke Philips, Biotricity, BioIntelliSense and Garmin.
Key opportunities include over-the-counter glucose and blood pressure sensing, artificial intelligence analytics, pharmacy and online sales, and growth in emerging markets.
Rising chronic disease prevalence, together with reimbursed remote patient monitoring and continuous sensor technology, is the main growth factor.
By Product Type, the Diagnostic and Monitoring Devices segment dominated the market in 2025 with an estimated 61.15% share, supported by wide use of glucose, cardiac and blood pressure monitoring.
North America dominated the market with a share of 40.35% in 2025, driven by high chronic disease prevalence, insurance coverage and early adoption of digital health.
