
Automotive Keyless Entry Systems Market Report Scope & Overview:
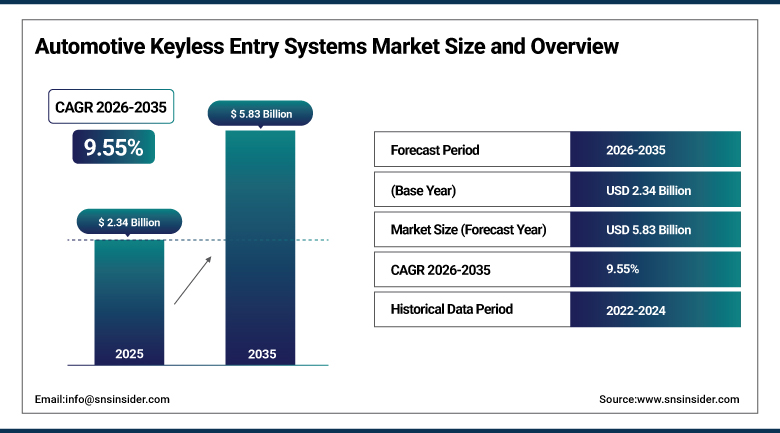
The Automotive Keyless Entry Systems Market was valued at USD 2.34 Billion in 2025 and is expected to reach USD 5.83 Billion by 2035, growing at a CAGR of 9.55% from 2026-2035.
Automotive keyless entry systems let drivers unlock, lock, and start a vehicle without inserting a physical key, using radio frequency, Bluetooth, or near-field communication signals exchanged between a credential device and the car. The category spans traditional remote keyless entry, where a driver presses a button on a fob, through passive keyless entry, which unlocks and starts the vehicle automatically once the fob is detected nearby, and increasingly smartphone-based digital key systems that eliminate the physical fob entirely. Growth is supported by rising consumer demand for seamless convenience, the automotive industry's broader transition toward connected and increasingly autonomous vehicle architectures, and growing awareness of vehicle security that has pushed suppliers toward ultra-wideband technology capable of defeating relay-attack theft.
On June 25, 2025, Continental started providing the CoSmA digital access system to Audi Q6 e-tron, a high-end electric sports utility vehicle (SUV), thus promoting the use of smartphone technology to gain access to vehicles. CoSmA technology leverages ultra-wideband technology to provide accurate position between the smartphone and the car, thus helping to prevent the vulnerability of relay attacks to achieve secured access. Using CoSmA, users have the ability to unlock and drive their car without removing the smartphone from the pocket.
To Get more information Automotive Keyless Entry Systems Market - Request Free Sample Report
Automotive Keyless Entry Systems Market Trends
- Rising adoption of smartphone-based digital key systems eliminating the need for a physical key fob.
- Growing use of ultra-wideband technology defeating relay-attack theft through precise proximity detection.
- Expanding passive keyless entry adoption on electric vehicle platforms with digital electrical architectures.
- Increasing extension of digital key technology from passenger cars into commercial fleet management.
- Rising Car Connectivity Consortium standardisation supporting cross-brand digital key compatibility.
U.S. Automotive Keyless Entry Systems Market Overview
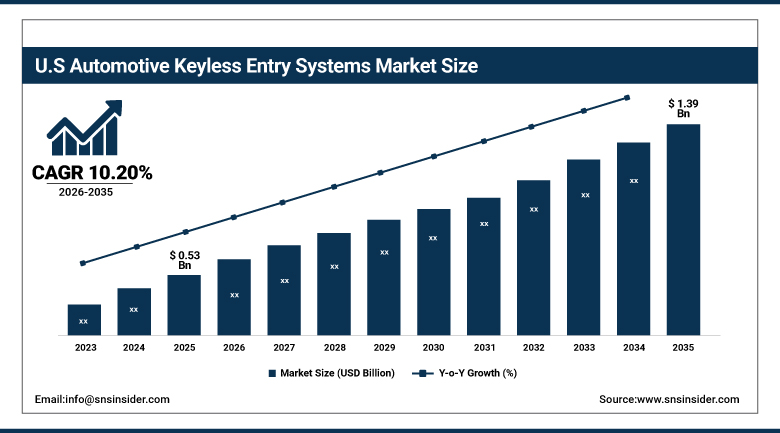
The U.S. Automotive Keyless Entry Systems Market was valued at USD 0.53 Billion in 2025 and is expected to reach USD 1.39 Billion by 2035, growing at a CAGR of 10.20% from 2026-2035.
The U.S. Automotive Keyless Entry Systems Market benefits from strong consumer demand for connected vehicle convenience features, an established base of leading Tier-1 suppliers developing next-generation digital key technology, and rising U.S. electric vehicle production that favours passive, software-defined access systems. Fleet operators are increasingly adopting keyless access technology to address the practical challenges of managing physical key fobs across large vehicle fleets, including loss, theft, and the administrative burden of tracking and reissuing keys. Leading suppliers continue to extend keyless technology originally developed for consumer passenger vehicles, giving fleet managers centralised visibility and control over vehicle access from a single dashboard. Continued adoption of ultra-wideband and Bluetooth-based digital key standards for the U.S. market is expected to sustain demand growth through the forecast period.
In November 2025, Denso demonstrated their keyless entry system for vehicle fleets at the ITS World Congress that took place in Atlanta. This system uses the same access technology as is used by BMW and Volvo in private cars. Access through Bluetooth and the ultra-wideband standard from the Car Connectivity Consortium allows you to have digital access without the use of any physical keys. Administrators of the vehicle fleets may manage all accesses via dashboard. The development expands Denso’s digital access technology into commercial fleet applications and strengthens connected vehicle access capabilities.
Automotive Keyless Entry Systems Market Segment Analysis
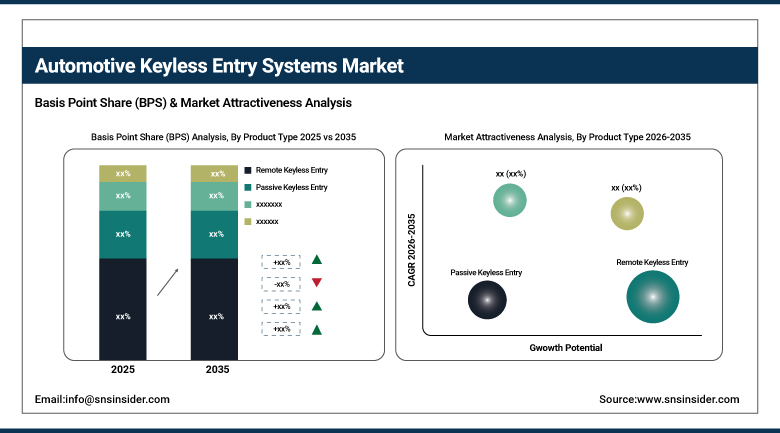
- By Product Type, the Remote Keyless Entry segment dominated the market with a 58.60% share in 2025, while the Passive Keyless Entry segment is the fastest growing with a CAGR of 10.60% during 2026-2035.
- By Vehicle Type, the Passenger Cars segment dominated the market with a 71.60% share in 2025, while the Light Commercial Vehicles segment is the fastest growing with a CAGR of 10.20% during 2026-2035.
- By Technology, the RF-Based segment dominated the market with a 62.60% share in 2025, while the Bluetooth/BLE-Based segment is the fastest growing with a CAGR of 11.60% during 2026-2035.
- By Sales Channel, the OEM segment dominated the market with a 78.60% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of 10.80% during 2026-2035.
By Product Type, Remote Keyless Entry Dominates the Market and Passive Keyless Entry Grows Fastest
Remote keyless entry dominated the market in 2025. This established technology, requiring a driver to press a button on a fob to lock or unlock a vehicle, continues to benefit from mature, well-understood radio frequency architecture and an attractive cost per vehicle, keeping it the standard equipment choice across a broad range of vehicle price points and sustaining its position as the largest product type category.
Passive keyless entry is projected to be the fastest-growing product type over the forecast period. Electric vehicle platform design, which simplifies continuous proximity detection through more digital, software-defined electrical architecture, continues to accelerate adoption of this more convenient technology, which unlocks and starts the vehicle automatically once the fob is detected nearby without requiring the driver to press any button at all.
By Vehicle Type, Passenger Cars Dominates the Market and Light Commercial Vehicles Grows Fastest
Passenger cars dominated the market in 2025. The sheer global production and ownership volume of passenger vehicles continues to anchor this vehicle type as the largest source of keyless entry system demand, reinforced by rising consumer expectation that convenience features once reserved for premium models are now standard across mainstream vehicle segments.
Light commercial vehicles are projected to be the fastest-growing vehicle type over the forecast period. Rising fleet electrification and growing adoption of keyless access technology for delivery and service fleet management continue to drive above-market growth for this vehicle type, as fleet operators increasingly value the operational efficiency keyless systems offer relative to traditional physical key management.
By Technology, RF-Based Dominates the Market and Bluetooth/BLE-Based Grows Fastest
RF-based technology dominated the market in 2025. Radio frequency remains the most widely deployed and thoroughly proven technology underlying automotive keyless entry systems, benefiting from decades of accumulated engineering refinement and a deeply established supplier and manufacturing ecosystem that continues to support reliable, cost-effective production at scale.
Bluetooth and Bluetooth Low Energy-based technology is projected to be the fastest-growing technology over the forecast period. Rising adoption of smartphone-based digital key systems, which rely on Bluetooth connectivity paired increasingly with ultra-wideband for precise, relay-attack-resistant location detection, continues to drive accelerating adoption of this technology relative to the broader RF-dominated technology mix.
By Sales Channel, OEM Dominates the Market and Aftermarket Grows Fastest
OEM installation dominated the market in 2025. Automakers continue to specify keyless entry systems directly into new vehicle electrical architecture during original design and manufacturing, ensuring proper integration with the vehicle's broader security and connectivity systems, and this factory-fit approach continues to account for the overwhelming majority of overall market volume.
The aftermarket is projected to be the fastest-growing sales channel over the forecast period. Owners of older vehicles equipped only with traditional physical keys increasingly seek aftermarket keyless entry retrofit kits, and growing awareness of these upgrade options continues to drive above-market growth for the aftermarket channel relative to the broader OEM-dominated sales mix.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
Asia Pacific |
China |
39.60% |
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
Asia Pacific Automotive Keyless Entry Systems Market Insights
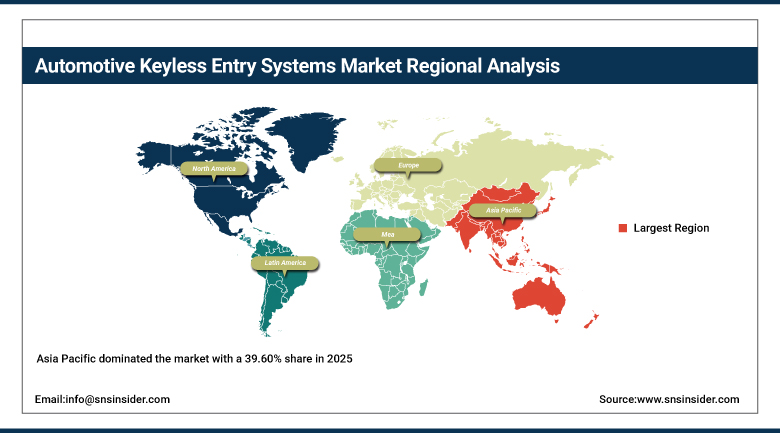
Asia Pacific dominated the market with a 39.60% share in 2025, supported by its position as the world's largest vehicle production base, rapidly expanding electric vehicle manufacturing, and growing consumer demand for connected vehicle convenience technologies. The region benefits from extensive automotive electronics supply chains and strong adoption of digitally enabled vehicle features across major markets. China anchors regional demand through its large-scale vehicle manufacturing industry, rapidly expanding electric vehicle production, and strong integration of connected technologies into new vehicle platforms.
Japan and South Korea provide even more regional depth by means of developed automotive electronics ecosystem, advanced vehicles technology, and the presence of top automotive producers. India also becomes a progressively significant contributor in terms of growing vehicle production, adoption of connected mobility, and digital automotive technologies. Increased use of smartphones, keyless access, and secure digital access technologies are also forecasted to drive regional demand.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Automotive Keyless Entry Systems Market Insights
North America is projected to be the fastest-growing region over the forecast period, registering a CAGR of approximately 10.20%. Rising consumer demand for convenience features of connected vehicles, rising production levels of electric vehicles, and innovations in digital key technology are some factors driving the adoption rate in the region. The US makes up the bulk of the regional demand driven by high expectations from consumers for vehicle access via smartphones.
Leading automotive manufacturers and Tier-1 technology suppliers are increasingly incorporating Bluetooth, ultra-wideband, and smartphone-based access solutions into new vehicle platforms. Canada contributes through its established automotive manufacturing and technology ecosystem, also adds demand through expanding vehicle production and assembly operations closely integrated with U.S. automotive supply chains. Growing adoption of connected vehicles and digital access technologies is expected to sustain regional expansion.
Europe Automotive Keyless Entry Systems Market Insights
Europe holds a significant share of the global market, anchored by Germany's substantial automotive manufacturing base and its position as a major center for premium vehicle production. Leading German automakers have supported adoption of advanced digital key, Bluetooth, and ultra-wideband access technologies across increasingly broad model portfolios. France, Italy, and other major European automotive markets contribute consistent regional demand through established vehicle manufacturing industries, strong premium vehicle segments, and growing integration of connected technologies.
European manufacturers are increasingly focusing on the integration of smartphones-based keyless entry and secure digital access systems in order to support the growth of the market. The focus on the security of vehicles, theft prevention, and secure access systems is promoting investments in secure digital access systems. The rising inclination towards connected convenience systems is likely to drive demand in Europe during the forecast period.
MEA & Latin America Automotive Keyless Entry Systems Market Insights
The Middle East & Africa region is supported by growing vehicle ownership, expanding premium vehicle sales, and increasing consumer demand for advanced in-vehicle technologies across the United Arab Emirates and Saudi Arabia. Strong adoption of connected and technology-rich vehicles is supporting demand for keyless entry systems, particularly across premium and luxury vehicle segments.
Latin America is anchored by Brazil, where an established domestic vehicle manufacturing industry, large vehicle parc, and expanding automotive electronics integration sustain steady demand for keyless entry technologies. Mexico contributes additional regional growth through its substantial vehicle production and assembly base and deep integration with North American automotive supply chains. Increasing adoption of connected vehicle features, smartphone-enabled access, and secure digital entry technologies is expected to support continued market development across both regions throughout the forecast period.
Market Dynamics
Growth Drivers: Consumer Convenience Demand and Connected Vehicle Architecture
Rising consumer demand for hassle-free entry into vehicles serves as a key factor driving the growth of the Keyless Entry System Market due to the rising expectation among consumers for easy access without physical contact. Increasing experience of users with phone-based services and digital authentication in various facets of daily life acts as an additional factor fueling consumer expectations regarding the same in vehicles. Shift in the automobile industry toward connected and autonomous vehicles serves as another important growth factor.
Keyless entry systems increasingly support these requirements through smartphone integration, Bluetooth, and ultra-wideband technologies. Growing awareness of vehicle theft and cybersecurity risks is further encouraging investment in secure access solutions, particularly ultra-wideband technologies designed to improve positioning accuracy and reduce relay-attack vulnerabilities. These trends are supporting broader adoption across premium and mainstream vehicle segments worldwide.
Restraints: Relay Attack Vulnerability and System Cost
Vulnerability to relay-attack theft remains a genuine restraint for legacy passive keyless entry systems, as criminals have developed technology capable of intercepting and extending key fob signals to gain unauthorised vehicle access, a security concern that continues to require ongoing supplier investment in more sophisticated, precisely localised access technology.
System cost presents a further restraint, as advanced keyless entry systems incorporating ultra-wideband technology and digital key management continue to command premium pricing relative to legacy remote keyless entry, a cost differential that can influence which trim levels and vehicle segments receive the most advanced access technology first.
Opportunities: Digital Key Standardisation and Fleet Management Expansion
The further standardization of digital key technology according to Car Connectivity Consortium standards offers considerable prospects for the development of the Keyless Entry System Market since more automobile manufacturers strive for solutions based on smartphones that work across various devices and platforms and can be used for accessing any vehicles regardless of their brand. The ability of suppliers to support digital key standardization allows automakers to decrease their reliance on proprietary access systems and to facilitate consumer convenience and technology compatibility.
Solutions that provide fleet managers with centralized visibility, authorization, monitoring, and control of vehicle access can improve operational efficiency and security across commercial fleets. Integration with fleet management platforms, Bluetooth, ultra-wideband, and smartphone authentication technologies can further expand addressable demand. These developments are expected to create new opportunities across logistics, rental, corporate, delivery, and shared mobility fleets.
Recent Developments:
- 2026: Tokai Rika Co., Ltd. advanced its Digitalkey strategy, targeting Tier 1 digital-key status while expanding smart-key sales in India and two-wheeler and micromobility applications.
- 2026: Kiekert AG expanded its vehicle-access technology portfolio around electronically controlled door and locking systems, supporting increasing OEM requirements for integrated keyless entry and automated vehicle access.
- 2025: HELLA GmbH & Co. KGaA (FORVIA) began series production of its digital Smart Car Access system in Romania and Mexico, incorporating UWB-based hands-free access and child-presence detection.
Automotive Keyless Entry Systems Market Key Players are:
- Continental AG
- Denso Corporation
- Valeo SE
- HELLA GmbH & Co. KGaA (Forvia)
- Tokai Rika Co., Ltd.
- Alps Alpine Co., Ltd.
- Kiekert AG
- Mitsubishi Electric Corporation
- Alpha Corporation (U-Shin)
- Robert Bosch GmbH
- Lear Corporation
- Marquardt GmbH
- Huf Hulsbeck & Furst GmbH & Co. KG
- Aptiv PLC
- ZF Friedrichshafen AG
- Texas Instruments Incorporated
- NXP Semiconductors N.V.
- Infineon Technologies AG
- Voxx International Corporation
- Directed Electronics, Inc.
Automotive Keyless Entry Systems Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.34 Billion |
| Market Size by 2035 | USD 5.83 Billion |
| CAGR | CAGR of 9.55% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Remote Keyless Entry, Passive Keyless Entry, Digital / Phone-as-a-Key) • By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles) • By Technology (RF-Based, Bluetooth/BLE-Based, NFC-Based, Ultra-Wideband (UWB)-Based, Others) • By Sales Channel (OEM, Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Continental AG, Denso Corporation, Valeo SE, HELLA GmbH & Co. KGaA (Forvia), Tokai Rika Co., Ltd., Alps Alpine Co., Ltd., Kiekert AG, Mitsubishi Electric Corporation, Alpha Corporation (U-Shin), Robert Bosch GmbH, Lear Corporation, Marquardt GmbH, Huf Hulsbeck & Furst GmbH & Co. KG, Aptiv PLC, ZF Friedrichshafen AG, Texas Instruments Incorporated, NXP Semiconductors N.V., Infineon Technologies AG, Voxx International Corporation, Directed Electronics, Inc. |
Frequently Asked Questions
Key players include Continental AG, Denso Corporation, Valeo SE, HELLA GmbH & Co. KGaA, and Tokai Rika Co., Ltd., among other automotive electronics suppliers.
Continued standardisation of digital key technology and continued expansion into fleet management applications represent the primary opportunities for suppliers.
Growth is primarily driven by escalating consumer demand for seamless convenience, combined with the automotive industry's transition toward connected vehicle architectures.
By Product Type, Remote Keyless Entry dominated the market with a 58.60% share in 2025, reflecting its mature, cost-effective radio frequency architecture.
Asia Pacific dominated the market with a 39.60% share in 2025, supported by the region's position as the world's largest vehicle production base.
