
Used Car Market Report Scope & Overview:
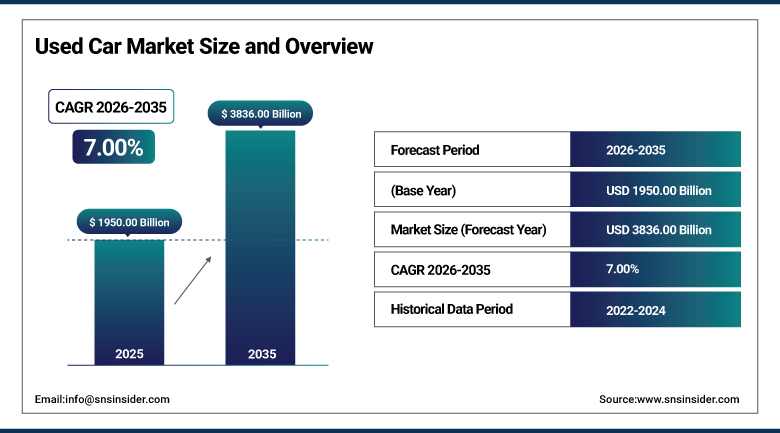
The Used Car Market was valued at USD 1,950.00 Billion in 2025 and is expected to reach USD 3,836.00 Billion by 2035, growing at a CAGR of 7.00% from 2026-2035.
Rise in The Used Car Market is mainly due to increases in costs of buying new cars that are driving an increasing number of consumers to consider second-hand cars as a cheaper means of getting hold of a car. Increased use of digital automotive marketplaces has turned the old market characterized by fragmentation and control by the dealers into an integrated value chain enhanced by digitization. Demand is also supported by increased availability of financing and increased consumer confidence in certified pre-owned vehicles programs that offer both the cost factor of a used car along with warranty and inspection making it almost comparable to buying a new one. Increased environmental consciousness and maturity of the first generation of electric vehicles is beginning to change the composition of the vehicles traded in the used car market leading to potential for above average growth going forward.
In March 2024, Auto1 Group SE enhanced its cross-border digital wholesale marketplace infrastructure across European markets to optimize dealer-to-dealer inventory redistribution and accelerate vehicle turnover cycles. The initiative illustrates how leading digital marketplace operators are investing in cross-border technology infrastructure to balance regional supply imbalances and improve transaction efficiency across an increasingly interconnected used vehicle ecosystem.
To Get more information Used Car Market - Request Free Sample Report
Used Car Market Trends
-
Rapid growth of digital automotive marketplaces and online platforms transforming used vehicle procurement.
-
Rising consumer preference for SUVs among used vehicle buyers, mirroring broader new-vehicle demand trends.
-
Growing maturation of first-generation electric vehicle fleets entering the used vehicle resale market.
-
Expanding certified pre-owned vehicle programs improving buyer confidence through warranty and inspection standards.
-
Increasing institutionalization of resale ecosystems shifting share from private-party sales toward organized dealers.
U.S. Used Car Market Outlook
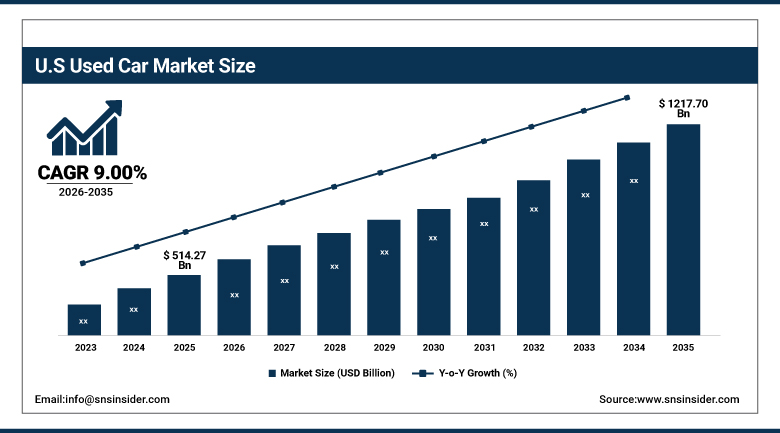
The U.S. Used Car Market was valued at USD 514.27 Billion in 2025 and is expected to reach USD 1,217.70 Billion by 2035, growing at a CAGR of 9.00% from 2026-2035.
U.S. Used Car Market growth is continually driven by a very fragmented retail environment, where the ten biggest U.S. used car retailers account for less than 10% of total market share. In addition to that, domestic demand enjoys strong e-commerce infrastructure in support of used cars retailers, as well as a strong vertically integrated logistics and reconditioning network. The ongoing growth in the number of transactions of domestic used electric vehicles contributes towards the need for dedicated capabilities to inspect, diagnose and evaluate battery electric vehicles being sold on the secondary market.
In January 2025, Cars.com Inc., a U.S.-based automotive technology company, acquired DealerClub, a digital wholesale auction platform, for USD 25 million, expanding into the wholesale used-vehicle market and enhancing its platform with dealer-to-dealer digital auction capabilities. The acquisition reflects continued domestic consolidation of digital marketplace infrastructure serving the broader U.S. used vehicle ecosystem.
Used Car Market Segment Analysis
-
By Vehicle Type, the SUV segment dominated the Used Car Market with approximately 34.50% share in 2025, and is also the fastest growing with a CAGR of approximately 8.20%.
-
By Fuel Type, the Petrol segment dominated the Used Car Market with approximately 43.60% share in 2025, while the Electric segment is the fastest growing with a CAGR of approximately 12.60%.
-
By Vendor Type, the Organized segment dominated the Used Car Market with approximately 54.50% share in 2025, while the Unorganized segment is the fastest growing with a CAGR of approximately 9.80%.
-
By Distribution Channel, the Offline segment dominated the Used Car Market with approximately 70.54% share in 2025, while the Online segment is the fastest growing with a CAGR of approximately 11.50%.
By Vehicle Type, SUV dominates and grows fastest
SUVs remain both the dominant and fastest-growing vehicle type segment within the Used Car Market, reflecting sustained consumer preference for SUV body styles that has carried over from the new-vehicle market into the resale segment over the past decade. This segment benefits from a rapidly expanding installed base of used SUVs entering the market as original owners trade in or sell vehicles purchased during the segment's strong new-vehicle sales growth in recent years.
This segment also focuses on strong residual value retention relative to sedans and hatchbacks, a characteristic that continues to attract both individual buyers and organized dealers seeking inventory with favorable resale economics. As consumer preference for SUV body styles remains durable across income levels and geographies, this segment is positioned to sustain its leadership across both current market share and forward growth.
By Fuel Type, Petrol dominates and Electric grows fastest
Petrol continues to be the dominating segment of fuel type in the Used Car Market because of the fact that the majority of cars operating in the current global fleet are powered by petrol engines as a result of years of production of the said vehicles. The petrol vehicle segment enjoys a well-established system for evaluation and testing as well as a vast infrastructure supporting its operation.
The Electric segment is becoming one of the fastest-growing segments in terms of fuel type. This is due to the fact that first-generation electric vehicles have started to enter the resale market and generate consumer interest due to their technical characteristics. The main task of the electric vehicle segment is to create systems of diagnostics which will be aimed at providing consumers with information about battery conditions.
By Vendor Type, Organized dominates and Unorganized grows fastest
Organized Dealers, which includes networks of franchised and certified pre-owned dealerships, continue to be the most prominent Vendor Type segment in the Used Car Market due to organized processes, standardized pricing systems, and efficient vendor management that eliminate risks of overpricing and low-quality vehicles during the transactions. The advantage of this segment is that its representatives are capable of selling certified vehicles with warranties and financing support which makes them more trusted compared to other segments.
Unorganized is the segment of private sellers and independent dealers, which represents the fastest growing category of vendors in the market because of its flexibility and accessibility for the buyers looking for low-priced vehicles and negotiable terms. It concentrates mainly on the development of online listings and peer-to-peer platforms and is oriented towards gaining bigger shares of the transactions regardless of slower sales processes compared to the organized dealerships.
By Distribution Channel, Offline dominates and Online grows fastest
Offline distribution is still the largest distribution channel in the Used Car Market due to consumers' preference for face-to-face car assessment and negotiations before committing to such a major purchase. Such type of distribution takes advantage of existing dealership channels and auctions that continue to be responsible for the large share of used vehicles transactions in the world.
Online distribution channel is expected to be the fastest growing one due to the increased number of online marketplaces that enable buyers to conduct research and financing and even make a full transaction via Internet. This distribution channel concentrates efforts on further improvement of digital vehicle inspection technologies and transparent pricing mechanisms.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
52.60% |
|
North America |
United States |
88.50% |
|
Europe |
Germany |
32.40% |
|
Latin America |
Brazil |
44.80% |
|
Middle East & Africa |
United Arab Emirates |
26.90% |
Asia Pacific Used Car Market Insights
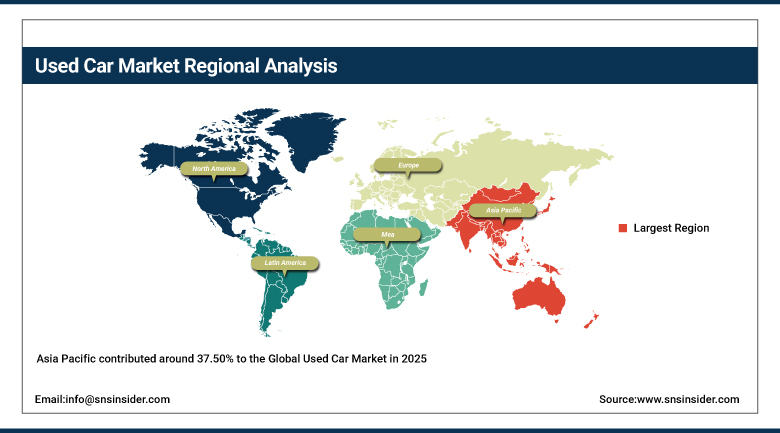
The Asia Pacific contributed around 37.50% to the Global Used Car Market in 2025 because of the large number of vehicles existing in the region, along with the fast-growing middle-class who want to own vehicles at economical prices.
China is one of the major contributors to this region owing to the large number of vehicles present in the country and also because of the rapid development of digital used vehicle market ecosystem.
Indian and Southeast Asian markets also add considerable regional demand, with the help of digital platforms like Cars24 that bring buyers and independent sellers together to facilitate transactions on used vehicles.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Used Car Market Insights
North America is projected to expand at the fastest CAGR of approximately 9.00% across the Used Car Market during the 2026-2035 forecast period, driven by sustained new-vehicle price inflation and a highly fragmented retail landscape that continues to support platform consolidation and market share capture by both traditional and digital-first retailers. The United States accounts for the substantial majority of regional demand, reflecting both its large vehicle parc and its position as home to leading used vehicle e-commerce platforms and auction operators.
Canada and Mexico contribute additional regional volume through cross-border used vehicle trade and growing domestic demand. Continued growth in vertically integrated digital used-vehicle retail models, combining online sales with owned logistics and reconditioning infrastructure, further reinforces North America's position as the fastest-growing regional market for used vehicles.
Europe Used Car Market Insights
Europe constitutes a substantial regional market for used cars due to the substantial vehicle parc in Germany and its significance as an important center for the inter-border trade of used cars in the European Union. The contribution of Germany to the used car trade in Europe is attributed to the presence of a substantial vehicle parc and infrastructure for digital wholesale marketplaces for cars.
Other countries such as the United Kingdom and France add further to the demand in the region. The increasing demand for environmentally friendly policies in the European Union and the consumer demand for certified used cars are factors supporting regional demand.
MEA & Latin America Used Car Market Insights
Latin America's Used Car Market is led by Brazil, which accounts for the majority of regional demand on the strength of its large domestic vehicle fleet and its role as a regional automotive trade hub. Gradual economic development and rising vehicle ownership aspirations across Brazil and Mexico continue to support steady regional demand growth for affordable used vehicles.
The Middle East & Africa region remains a smaller contributor to global demand, with growth concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where expanding digital automotive marketplace services are improving inspection verification and financing partnerships for used vehicle buyers. South Africa continues to anchor used vehicle demand on the African continent, supported by its comparatively more developed automotive trade infrastructure.
Market Dynamics
Growth Drivers: Rising New-Vehicle Prices and Digital Marketplace Expansion
An increase in new vehicle pricing trends constitutes the main growth factor of the Used Car Market, considering that a growing proportion of customers opt for used cars as more affordable means of acquiring a vehicle with the persistence of the increase in new vehicle costs. This trend is also facilitated by the growing number of digital auto marketplaces that have enabled used car sales to evolve from a dispersed dealer-to-dealer process to an integrated digital value chain.
Greater access to financing and the increased consumer confidence in certified used car programs are additional factors facilitating demand, as these programs offer the convenience of used cars and, at the same time, include guarantees and warranties comparable to those available for new vehicles. Increased urbanization and the development of dealership networks contribute to market growth as well.
Restraints: Battery Valuation Complexity and Financing Cost Sensitivity
The uncertainty associated with the performance and valuation of batteries constitutes a major constraint in the Used Car Market concerning the electric car category, as the lack of history in relation to the degradation and cost of replacing the battery is a factor that both consumers and dealers still struggle with. This calls for the need to enhance transparency in battery diagnostics.
Higher cost of financing in particular markets makes the purchase of used cars too costly for some buyers especially in informal and private-party markets which have fewer finance choices. Economic uncertainty and variable interest rates contribute to this variability in the demand for used vehicles.
Opportunities: Electric Vehicle Resale Maturation and Digital Platform Expansion
Continued maturation of first-generation electric vehicle fleets into the resale market presents a substantial growth opportunity for the Used Car Market, as improving diagnostic transparency and warranty transfer processes gradually improve buyer acceptance of used electric vehicles. Platform operators and dealers that can develop validated, transparent electric vehicle inspection and valuation capabilities are well positioned to capture share as electric vehicle resale volumes continue to scale.
Expanding digital marketplace and peer-to-peer platform adoption presents a longer-term opportunity for both organized and unorganized sellers to improve transaction visibility and buyer access across previously underserved market segments. As digital purchasing comfort continues to expand across buyer demographics, platform operators with established technology and logistics capabilities are positioned to capture a disproportionate share of this emerging demand.
Recent Developments:
-
In January 2024, CarMax Inc. expanded its artificial intelligence-based vehicle appraisal platform across its nationwide operations to improve pricing accuracy and inventory acquisition efficiency amid fluctuating vehicle supply conditions.
-
In July 2024, Lithia Motors Inc. accelerated investment in centralized vehicle reconditioning hubs supporting omnichannel used vehicle retail expansion, targeting operational margin improvement through standardized refurbishment processes.
-
In January 2025, Dubizzle Group expanded its digital automotive marketplace services in the United Arab Emirates to strengthen inspection verification and financing partnerships for used vehicle buyers.
-
In February 2025, Cazoo Group Ltd. restructured its operating model toward marketplace-led, asset-light transactions following earlier inventory-heavy expansion challenges, emphasizing third-party dealer integration and digital financing interfaces.
Used Car Market Key Players
-
CarMax, Inc.
-
Carvana Co.
-
AutoNation, Inc.
-
Cox Automotive Inc.
-
Asbury Automotive Group, Inc.
-
Penske Automotive Group, Inc.
-
Lithia Motors, Inc.
-
Group 1 Automotive, Inc.
-
Sonic Automotive, Inc.
-
TrueCar, Inc.
-
CarGurus, Inc.
-
Cars24 Services Pvt. Ltd.
-
Auto1 Group SE
-
OLX Autos
-
Vroom, Inc.
-
Cazoo Group Ltd.
-
Mahindra First Choice Wheels Ltd.
-
Arnold Clark Automobiles Ltd.
-
Dubizzle Group
-
Cars.com Inc.
Used Car Market Report Scope:
| Report Attributes | Details | ||
|---|---|---|---|
| Market Size in 2025 | USD 1,950.00 Billion | ||
| Market Size by 2035 | USD 3,836.00 Billion | ||
| CAGR | CAGR of 7.00% From 2026 to 2035 | ||
| Base Year | 2025 | ||
| Forecast Period | 2026-2035 | ||
| Historical Data | |||
| Report Scope & Coverage | Market S
|
||
| Key Segments | • by Vehicle Type (Hatchback, Sedan, SUV, and Pickup Truck) • by Fuel Type (Petrol, Diesel, Hybrid, and Electric) • by Vendor Type (Organized and Unorganized) • by Distribution Channel (Offline and Online) |
||
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). | ||
| Company Profiles | CarMax, Inc., Carvana Co., AutoNation, Inc., Cox Automotive Inc., Asbury Automotive Group, Inc., Penske Automotive Group, Inc., Lithia Motors, Inc., Group 1 Automotive, Inc., Sonic Automotive, Inc., TrueCar, Inc., CarGurus, Inc., Cars24 Services Pvt. Ltd., Auto1, Group SE, OLX Autos, Vroom, Inc., Cazoo Group Ltd., Mahindra First Choice Wheels Ltd., Arnold Clark Automobiles Ltd., Dubizzle Group, Cars.com Inc. |
Frequently Asked Questions
Leading companies in the Used Car Market include CarMax, Carvana, AutoNation, Cox Automotive, and Lithia Motors, among others.
Key opportunities include continued maturation of first-generation electric vehicle fleets into the resale market, and expanding digital marketplace and peer-to-peer platform adoption across underserved market segments.
Rising new-vehicle prices pushing consumers toward pre-owned vehicles, combined with expanding digital automotive marketplaces improving price transparency and buyer confidence, is the major factor driving market growth.
The Petrol segment dominated the Used Car Market with approximately 43.60% share in 2025.
Asia Pacific dominated the Used Car Market in 2025 with approximately 37.50% share, reflecting the region's massive vehicle parc and growing middle-class demand for affordable vehicle ownership, led by China.
