
Clinical Alarm Management Market Report Scope & Overview:
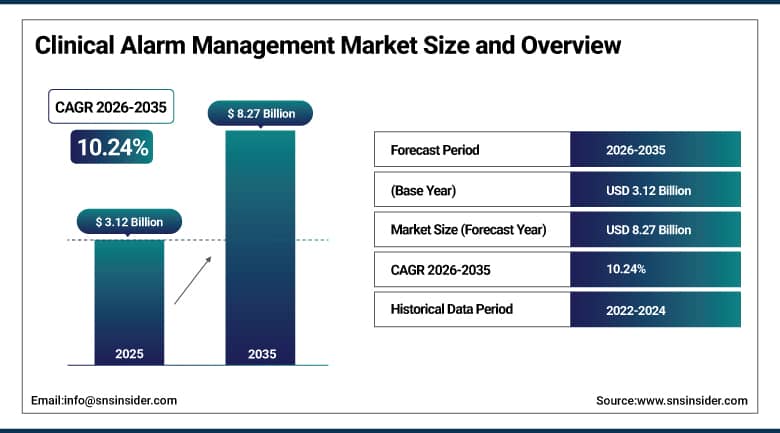
The Clinical Alarm Management Market was valued at USD 3.12 Billion in 2025 and is projected to reach USD 3.44 Billion in 2026 and USD 8.27 Billion by 2035, registering a CAGR of 10.24% over the forecast period. Growth is anchored in the need to reduce alarm fatigue, the spread of connected bedside devices, and the effort of hospitals to route only actionable alerts to the right caregiver. Buyers are moving from isolated alarm settings toward software platforms that filter, prioritize, and deliver alerts to mobile devices while recording every response for quality review.
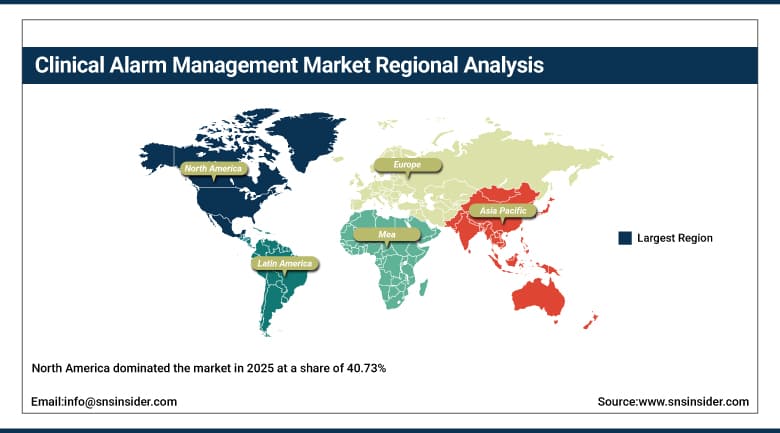
North America accounted for the largest share of the market at 40.73% in 2025, supported by strict patient safety goals, a large base of monitored beds, and early integration with electronic health record platforms. The United States leads regional demand because hospital systems tie alarm performance to safety programs and nurse retention. Asia Pacific is the fastest growing region, helped by hospital construction, rising critical care capacity, and the adoption of smart ward technologies in China, Japan, India, and South Korea. Mobile alerting and integration with record systems are the main purchasing priorities in both regions.
To Get More Information On Clinical Alarm Management Market - Request Free Sample Report
Key Report Takeaways
-
By component, solutions held a 66.27% share in 2025, while services are the fastest growing.
-
By technology, wireless alarm management systems accounted for 44.62% of the market in 2025, while mobile application-based alarm management is the fastest growing.
-
By application, patient monitoring led with a 45.92% share in 2025, while alarm notification and communication is the fastest growing.
-
By end user, hospitals represented 52.41% of the market in 2025, while long-term care and home healthcare is the fastest growing.
-
By region, North America led with a 40.73% share in 2025, while Asia Pacific is expected to expand fastest at a CAGR of 11.19%.
Market Trends and Insights
Alarm analytics is moving from reporting to prediction. Platforms now rank alarm sources by the share of non-actionable signals and suggest threshold changes, so clinical teams can retire noisy alerts before they spread across a unit.
Epic integration has become a purchasing filter. Vendors that appear in the electronic record vendor's partner catalog for alert management are shortlisted more often, since hospitals want alarms and orders to share one workflow.
Caregiver communication devices are consolidating. Wearable badges, smartphones, and ward-level displays are being combined with nurse call and virtual care, which lets one platform deliver alarms, messages, and video consults.
Alarm management is extending beyond intensive care. Step-down units, telemetry floors, long-term care homes, and remote monitoring programs are adopting the same filtering and escalation rules that intensive care units use.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Rising alarm fatigue and patient safety requirements |
+2.64% |
North America, Europe |
Short term (2 years or less) |
|
Expansion of connected bedside devices and remote monitoring |
+2.21% |
Global |
Medium term (2 to 4 years) |
|
Integration with electronic health records and clinician mobile devices |
+1.87% |
North America, Europe |
Medium term (2 to 4 years) |
|
Adoption of artificial intelligence for alarm filtering |
+1.52% |
North America, Asia Pacific |
Long term (4 years or more) |
|
Nurse staffing shortages and retention pressure |
+1.14% |
Global |
Medium term (2 to 4 years) |
Rising Alarm Fatigue and Patient Safety Requirements
A single monitored patient can generate hundreds of alerts in a day, and most do not need a clinical response. Staff who hear constant tones may delay or miss the alarms that matter, which makes alarm fatigue a recognized patient safety hazard. Accreditation bodies expect hospitals to set alarm priorities, review policies, and monitor performance, so safety committees now fund software that measures and reduces non-actionable alerts. For instance, in October 2024, a pilot at a large health system projected a 58% reduction in non-actionable alarms after workflow changes supported by analytics.
Expansion of Connected Bedside Devices and Remote Monitoring
Hospitals are connecting more ventilators, infusion pumps, physiological monitors, and bed sensors to networks, and each device adds its own alarm sounds and thresholds. Remote monitoring and virtual nursing programs add further streams that must be reviewed by staff who are not at the bedside. A central platform that collects these signals, removes duplicates, and sends a single prioritized message is easier to manage than separate device alarms. Growth in connected equipment therefore creates a direct and recurring need for alarm management software and integration services.
Integration with Electronic Health Records and Clinician Mobile Devices
Alarm platforms are most useful when they link patient context, orders, and staff assignments with the alert itself. Integration with electronic health records lets the system route a message to the nurse responsible for a patient, include recent vital signs, and document the response. Smartphones and wearable badges allow caregivers to receive alerts away from the nursing station. Vendors that are listed in electronic record partner catalogs shorten procurement and implementation, which has made integration depth a central point of competition among alarm management suppliers.
Adoption of Artificial Intelligence for Alarm Filtering
Machine learning models can compare alarm patterns across thousands of patients and identify combinations of signals that rarely lead to intervention. Hospitals use these insights to adjust default limits, add short delays before an alert is sent, or suppress signals during known activities such as turning a patient. Predictive models can also escalate a deteriorating patient earlier than a single threshold would. As evidence accumulates that filtering reduces noise without missing critical events, clinical leaders become more willing to approve automated suggestions, supporting steady growth in analytics modules and service contracts.
Nurse Staffing Shortages and Retention Pressure
Persistent nurse shortages mean each caregiver covers more patients, so interruptions from unnecessary alarms carry a higher cost. Hospital leaders link noisy units to burnout and turnover, and they increasingly view quieter wards as a retention benefit as well as a safety measure. Mobile alerting, smart routing, and hands-free communication help smaller teams respond faster and avoid unnecessary walks to the bedside. Budget holders are therefore able to justify alarm management projects through staffing and satisfaction metrics, and not only through clinical safety indicators.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High implementation cost and integration complexity |
-1.42% |
Global |
Short term (2 years or less) |
|
Lack of alarm standardization across device makers |
-1.08% |
Global |
Medium term (2 to 4 years) |
|
Cybersecurity and data privacy concerns around connected alerting |
-0.76% |
North America, Europe |
Medium term (2 to 4 years) |
|
Clinician resistance and change management burden |
-0.58% |
Global |
Long term (4 years or more) |
High Implementation Cost and Integration Complexity
An alarm management project usually involves wireless network upgrades, interfaces to monitors and nurse call systems, device purchases, and extended staff training. Smaller hospitals and facilities in developing regions often lack the capital and the technical staff for such work. Subscription pricing lowers the initial outlay, yet total cost still rises with the number of beds and connected devices. Long implementation periods also delay the return on investment, which leads some finance committees to postpone projects in favor of urgent equipment replacement.
Lack of Alarm Standardization Across Device Makers
Monitors, ventilators, and pumps from different manufacturers use their own alarm sounds, priorities, and data formats. Platforms must build and maintain separate interfaces for each device family, and hospitals with mixed fleets find it difficult to apply uniform rules. Differences in how devices describe alarm severity can also cause confusion when alerts are consolidated. Until open standards for alarm data are widely used, integration will remain slow and expensive, and some hospitals will keep manual practices that limit the benefit of central software.
Cybersecurity and Data Privacy Concerns Around Connected Alerting
Alarm platforms sit between clinical devices and staff communication networks, so they handle patient identifiers and carry messages that clinicians depend on for safety. A breach or outage could delay critical alerts, which makes information security teams cautious about adding new connections. Hospitals ask vendors for software bills of materials, penetration testing results, and clear incident procedures. These reviews lengthen purchasing cycles, and organizations with limited security resources may postpone projects until risk assessments are fully complete and approved by committees.
Clinician Resistance and Change Management Burden
Changing alarm limits and routing rules alters long-standing habits, and some clinicians worry that suppressed alerts could lead to missed events. Without strong clinical leadership and a careful review process, projects may stall or return to prior settings. Training takes time from busy teams, and benefits appear only after several months of data collection. Vendors therefore need to supply clinical consultants and governance templates, which adds cost and extends deployment schedules, particularly in organizations that lack a dedicated alarm safety committee.
Clinical Alarm Management Market Segment Analysis
By Component, Solutions Dominate Clinical Alarm Management Market; Services to Register Fastest Growth.
Solutions held a 66.27% share in 2025 because hospitals first purchase the software platforms, middleware, and notification devices that collect, filter, and route alarms. These products carry license fees tied to the number of beds and connected devices, and they form the base of every deployment. Vendors also bundle analytics dashboards and mobile applications within the same contract, which raises the value of each installation and keeps product revenue ahead of service revenue across mature health systems today.
Services are expected to expand at a CAGR of 10.96% from 2026 to 2035, driven by the need for assessment, integration, training, and ongoing optimization. Hospitals often lack internal engineers who can map every device interface or tune alarm limits safely. Vendors and consultants therefore sell clinical advisory packages, managed analytics, and support contracts. As installed bases mature, recurring optimization work becomes a larger part of revenue, and providers value outside expertise when they extend programs to more units.
By Technology, Wireless Alarm Management Systems Dominate Clinical Alarm Management Market; Mobile Application-Based Alarm Management to Register Fastest Growth.
The wireless alarm management system comprised 44.62% of the market share in 2025 because hospitals can issue alerts without any need for wiring their ward or depending upon fixed screens. In the wireless network, monitors, nurse call stations, and handheld devices are connected across an entire building, making escalation possible when the initial caregiver fails to respond. As the installed base of wireless technology is extensive in acute care hospitals, implementing alarm software over the existing technology would be more affordable and quicker than installing a whole new system for alarms.
The mobile application-based alarm management segment is forecasted to witness the growth rate of 12.84% during 2026 and 2035 due to the ability of hospitals to allow clinicians to utilize secured smartphones and wearable badges as their alarm devices. Applications have the potential to track the patient's trend, provide response options in just a single touch, and transfer the process to another caregiver in case of their availability. The low-cost of hardware, bring-your-own-device strategy, and user-friendliness are encouraging hospitals to adopt such solutions.
By Application, Patient Monitoring Dominates Clinical Alarm Management Market; Alarm Notification and Communication to Register Fastest Growth.
Patient monitoring held a 45.92% share in 2025 because bedside and telemetry monitors generate the largest number of alarms in a hospital. Intensive care units, step-down wards, and emergency departments have the heaviest alarm burden, and they were the first to adopt management software. Accreditation expectations for alarm safety focus on physiological monitoring, which keeps this application at the center of purchasing decisions and funds the earliest analytics projects in most health systems and across many different hospital types.
Alarm notification and communication is expected to record a CAGR of 11.72% from 2026 to 2035 as hospitals extend software beyond monitors to nurse call, bed exit, infusion pumps, and ventilators. A unified notification layer allows alerts from many sources to follow the same escalation rules and reach the right person on a single device. Staffing pressure and interest in virtual nursing add further demand, because remote staff depend on consistent routing and clear acknowledgment tracking for every alert sent.
By End User, Hospitals Dominate Clinical Alarm Management Market; Long-Term Care and Home Healthcare to Register Fastest Growth.
Hospitals represented 52.41% of the market in 2025 because they operate the largest number of monitored beds, face the strictest safety oversight, and employ clinical engineering teams able to manage complex projects. Large systems purchase enterprise platforms that cover many facilities, and academic centers often act as early adopters that publish results. Their budgets for patient safety and nursing workflow give vendors a stable customer base, and reference sites strongly influence other buyers considering similar investments in other hospitals.
Long-term care and home healthcare is projected to expand at a CAGR of 12.09% between 2026 and 2035, as older adults receive more monitored care outside acute hospitals. Skilled nursing facilities adopt wearable sensors, fall detection, and remote vital sign programs, all of which generate alerts that must be filtered and routed to small teams. Cloud-based platforms with simple setup suit these operators, and payer interest in reducing readmissions supports further investment in monitoring and alert management tools.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
89.74% |
|
Europe |
Germany |
24.37% |
|
Asia Pacific |
China |
31.84% |
|
Middle East & Africa |
Saudi Arabia |
34.27% |
|
Latin America |
Brazil |
44.19% |
North America Clinical Alarm Management Market
North America dominated the market in 2025 at a share of 40.73%, driven by patient safety objectives that entail the management of alarm systems, monitored bed presence, and wide use of electronic health records. The US provides the bulk of regional demand, with 2025 value forecasted at USD 1.14 Billion, growing with a CAGR of 10.65% until 2035. Alarm committees are formally set up within health systems, while purchasing has been evolving towards enterprise platforms that bring together devices, staff communication, and analytics.
Regional purchase decisions are strongly affected by collaborations with vendors of the record. For instance, Ascom declared in September 2026 that its alarm and alert platform became available on Epic Toolbox for alert management, providing an easy pathway for acute care hospitals to integrate alarms into clinical workflows. Canada generates stable demand through its regional investments in connected monitoring. Nurse shortage pressures are driving hospitals to prefer mobile alerting solutions and virtual nurses. Regional pilots and academic medical centers publish their outcomes impacting peer hospitals.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Clinical Alarm Management Market
Europe comprised the second biggest market share, with Germany being the most requested country for alarms due to its developed hospital infrastructure and medical devices industry. Besides, the United Kingdom, France, and the Nordic countries have alarms integrated into digital hospital systems for use in telemetry and intensive care units. Buyers prefer vendors with products that can provide multiple language interfaces, nurse call compliance, and reliable data protection, thus making a regional company competitive to multinational ones in the tendering process. Buyers from the Nordics are the leaders in digitalization and interoperability.
Regulations shape how products are developed and distributed. European hospitals need to be compliant with the medical devices regulation, which includes some kinds of alarms in the medical device category, and with the data protection regulation that regulates how patient data are processed. These factors favor companies with an established quality system and local hosting capabilities. Public tenders now require vendors to demonstrate how they reduce alarm burden, ensure interoperability with national record keeping standards, and update cybersecurity regularly during contract lifetime.
Asia Pacific Clinical Alarm Management Market
Asia Pacific is the fastest growing region, with a projected CAGR of 11.19% from 2026 to 2035. China holds the largest national share, driven by new hospital construction, expanding intensive care capacity, and strong domestic monitoring manufacturers. Japan has a mature market with high bed density and advanced nurse call systems, while India and South Korea are investing in digital hospitals and smart ward programs. Rising health spending widens the number of facilities that can afford alarm software. Private hospital chains add further demand.
Many hospitals in the region are building monitoring infrastructure for the first time, which lets them design alarm routing at the start instead of retrofitting older networks. Manufacturers that supply monitors and software together can offer integrated packages at competitive prices. Government programs to upgrade critical care capacity, along with growing interest in telemedicine and remote intensive care, are creating additional demand. Training staff and adapting products to local languages remain important conditions for success. Local distribution partnerships help foreign suppliers enter.
Latin America Clinical Alarm Management Market
Latin America accounted for 5.41% of the market in 2025, with Brazil representing the leading national market. Large private hospital groups in Sao Paulo and other major cities are adopting central monitoring and mobile alerting to improve safety scores and attract international accreditation. Mexico, Chile, and Colombia follow with investments in intensive care capacity. Public hospitals adopt more slowly because of tight budgets, and imported equipment priced in foreign currency can delay purchases when exchange rates are unfavorable. Interest is rising.
Distribution partnerships are the main route to market, since local integrators handle installation, language support, and service contracts. Cloud-based and subscription offerings help hospitals avoid large upfront costs. Interest is strongest in intensive care, neonatal units, and emergency departments, where alarm volume is highest. Health ministries and accreditation programs in several countries are encouraging better patient safety practices, which should raise awareness of alarm fatigue and support gradual adoption of management platforms. Regional conferences and professional societies are also spreading best practices among nurses and hospital administrators.
Middle East & Africa Clinical Alarm Management Market
The Middle East and Africa represented the smallest share at 5.22% in 2025. Saudi Arabia leads the regional market, supported by national health transformation programs, new hospital projects, and growing intensive care capacity. The United Arab Emirates and Qatar follow with early adoption in flagship hospitals and medical cities that seek international accreditation. Gulf governments tend to prefer integrated technology packages from established suppliers, creating opportunities for vendors that offer training, implementation, and long-term service support. Medical tourism also raises quality expectations.
South Africa provides most of the demand in Africa, where private hospital groups invest in monitoring and nurse communication tools. Elsewhere on the continent, adoption is limited by funding, power reliability, and a shortage of biomedical engineers. Donor-supported intensive care projects and public-private partnerships are therefore important routes to market. Simple systems that work over existing networks and require minimal maintenance are better suited to these conditions than complex enterprise platforms that need specialized staff. Local training remains essential for long-term success.
Competitive Landscape
The Clinical Alarm Management Market shows a moderately consolidated structure. Patient monitoring manufacturers, medical technology groups, and clinical communication specialists compete for hospital contracts, and several record vendors have added alert management to their platforms. Large suppliers hold the biggest installed bases because alarm software is often sold with monitors, while specialist firms win projects by offering faster deployment, deeper analytics, and neutral integration across device brands. Hospitals increasingly prefer one platform that connects alarms with communication and virtual care.
Vendors follow four main strategic lines. Product launches add analytics and mobile features to existing platforms, partnerships connect alarm software to electronic records and virtual care providers, acquisitions bring communication tools and wearable devices into larger portfolios, and artificial intelligence is being used to filter alerts and predict deterioration. Companies also invest in clinical advisory services, since hospitals need help with governance and threshold design before technology can deliver a measurable reduction in non-actionable alarms.
Clinical Alarm Management Market Industry Leaders
1. Koninklijke Philips N.V.: Supplier of patient monitoring systems and telemetry platforms with integrated alarm management and clinical analytics.
2. GE HealthCare: Provider of patient monitoring and mobile clinical applications that deliver prioritized alarms to caregiver devices.
3. Stryker Corporation: Owner of Vocera communication badges and a growing smart hospital platform linking alarms to caregivers.
4. Ascom Holding AG: Specialist in hospital communication and clinical alarm and alert management with deep nurse call integration.
5. Spok Holdings, Inc.: Provider of clinical communication and alert routing software used by hospitals across North America.
Companies Covered in this Report
-
Koninklijke Philips N.V.
-
GE HealthCare
-
Stryker Corporation
-
Ascom Holding AG
-
Spok Holdings, Inc.
-
Masimo Corporation
-
Medtronic plc
-
Baxter International Inc.
-
Drägerwerk AG & Co. KGaA
-
Nihon Kohden Corporation
-
Mindray Medical International Limited
-
TigerConnect, Inc.
-
Connexall USA
-
AirStrip Technologies, Inc.
Recent Industry Developments
-
May 2025: AirStrip introduced AirStrip Alarm Management, a platform designed to reduce non-actionable alerts delivered to clinicians.
-
July 2025: Connexall became available in the Epic Toolbox as an alert manager integration solution for hospitals using Epic.
-
September 2025: Philips and Masimo renewed their multi-year strategic collaboration to integrate Masimo monitoring technologies into Philips patient monitoring platforms.
-
October 2025: Nihon Kohden launched AlarmSense, an analytics platform that helps hospitals study and reduce alarm burden.
-
December 2025: TigerConnect Alarm Management received Epic Toolbox designation in the alert manager category.
-
March 2026: Stryker launched its SmartHospital Platform to connect caregivers, devices, and clinical communication workflows.
-
September 2026: Ascom listed its clinical alarm and alert management platform in the Epic Toolbox for alert manager integration.
Scope and Research Methodology
This study defines the Clinical Alarm Management Market as the software, services, and communication devices used to collect, filter, prioritize, and deliver alarms and alerts from patient monitors, infusion pumps, ventilators, nurse call systems, and other clinical equipment to caregivers. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are expressed in USD. The market is segmented by component, technology, application, end user, and region, and each segment is reported with its 2025 share and its forecast growth rate. Regional coverage spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with country-level detail for the leading national markets in each region.
The research program combines secondary and primary work. Secondary research draws on company annual reports, investor presentations, regulatory filings, accreditation standards, government health statistics, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with executives, product and business heads, clinical engineers, nurse informaticists, procurement managers, and hospital technology leaders across the value chain. These conversations validate assumptions on adoption rates, pricing, deployment models, and integration practices. Interview findings are compared across respondent groups so that vendor views are tested against buyer experience, and conflicting answers are resolved through follow-up discussions before they are accepted.
Market engineering follows a bottom-up build from vendor revenue, installed base, and adoption data, which is then cross-checked top-down against hospital technology spending, monitored bed counts, and sector indicators. Triangulation across these routes narrows differences before figures are finalized. Forecasts take into account patient safety policy, device connectivity trends, technology cost curves, staffing conditions, and macroeconomic factors in each region. Every estimate passes a structured analyst quality review for consistency across segments and regions before it is released in the report. Estimates are refreshed as new regulatory decisions, company disclosures, and procurement data become available during the research cycle.
Clinical Alarm Management Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.12 Billion |
| Market Size by 2035 | USD 8.27 Billion |
| CAGR | CAGR of 10.24% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Solutions and Services) • By Technology (Wired Alarm Management Systems, Wireless Alarm Management Systems, and Mobile Application-Based Alarm Management) • By Application (Patient Monitoring, Alarm Notification and Communication, and Other Applications) • By End User (Hospitals, Ambulatory Surgical Centers and Clinics, and Long-Term Care and Home Healthcare) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Koninklijke Philips N.V., GE HealthCare, Stryker Corporation, Ascom Holding AG, Spok Holdings, Inc., Masimo Corporation, Medtronic plc, Baxter International Inc., Drägerwerk AG & Co. KGaA, Nihon Kohden Corporation, Mindray Medical International Limited, TigerConnect, Inc., Connexall USA, AirStrip Technologies, Inc. |

Frequently Asked Questions
The market was valued at USD 3.12 Billion in 2025 and is expected to reach USD 3.44 Billion in 2026 and USD 8.27 Billion by 2035.
The market is projected to grow at a CAGR of 10.24% from 2026 to 2035.
North America leads with a 40.73% share in 2025, supported by patient safety requirements and widespread electronic record integration.
Asia Pacific is expected to grow fastest, at a CAGR of 11.19% from 2026 to 2035.
Solutions, wireless alarm management systems, patient monitoring, and hospitals lead their respective segments. Services, mobile application-based alarm management, alarm notification and communication, and long-term care and home healthcare are the fastest growing.
Koninklijke Philips N.V., GE HealthCare, Stryker Corporation, Ascom Holding AG, and Spok Holdings, Inc. are among the major players.
Implementation cost, lack of alarm standardization, cybersecurity concerns, and clinician resistance are the main challenges.
