
Cloud Logistics Market Report Scope & Overview:
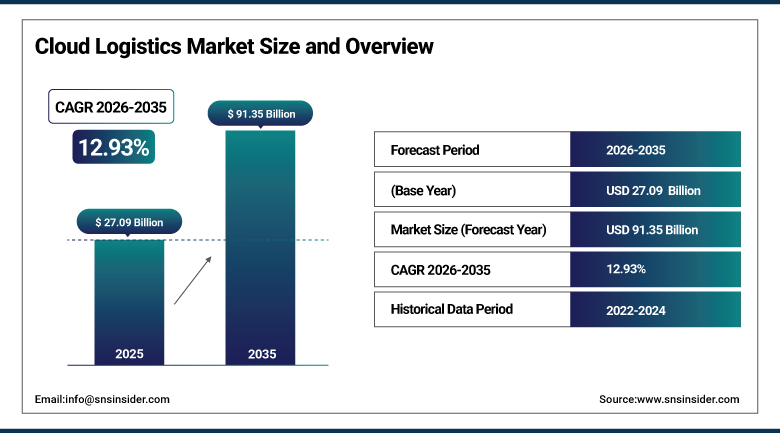
The Cloud Logistics Market was valued at USD 27.09 Billion in 2025 and is expected to reach USD 91.35 Billion by 2035, growing at a CAGR of 12.93% from 2026-2035.
The Cloud Logistics Market covers cloud-based software and platforms that plan, execute and track the movement and storage of goods, including transportation management, warehouse management, freight visibility, route optimization and last-mile delivery. Shippers, carriers and logistics providers use these tools to gain real-time visibility, cut cost and respond to disruption. E-commerce growth, complex global trade routes and pressure to reduce emissions are pushing adoption. Artificial intelligence agents and Internet of Things data now sit on top of these platforms. Data security concerns and integration with older systems slow some deployments. Subscription pricing makes advanced tools reachable for smaller firms.
⮞In October 2026, the World Trade Organization forecast world merchandise trade volume growth of 3.9% for 2026, up from 1.9% in its March outlook, and 4.1% for 2027. A stronger trade outlook raises the volume of goods that logistics platforms must coordinate.
To Get more information Cloud Logistics Market - Request Free Sample Report
Cloud Logistics Market Trends
-
AI agents embedded in transportation and warehouse management platforms
-
Real-time freight visibility networks connecting shippers and carriers
-
Consolidation of logistics software providers through acquisitions
-
Sustainability reporting and emissions calculation inside logistics software
-
Growth of cloud tools for small and mid-sized shippers and carriers
U.S. Cloud Logistics Market Outlook
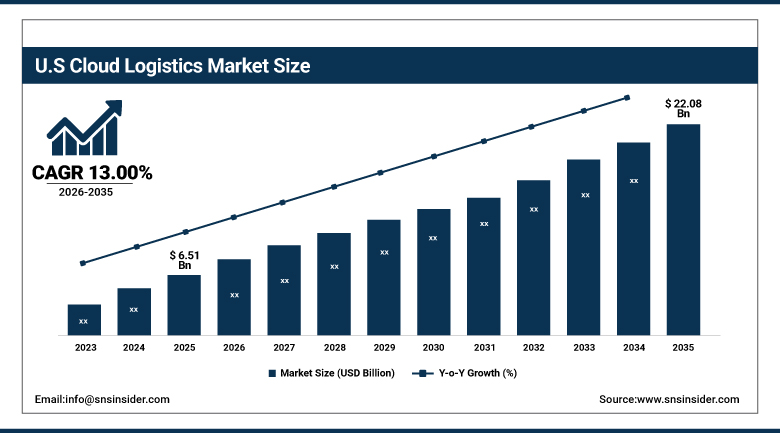
The U.S. Cloud Logistics Market was valued at USD 6.51 Billion in 2025 and is expected to reach USD 22.08 Billion by 2035, growing at a CAGR of 13.00% from 2026-2035.
The U.S. Cloud Logistics Market is the largest domestic market owing to freight transport infrastructure, e-commerce environment, and numerous software providers in the logistics field. The shippers use cloud technology for trucking, rail, marine, and parcel transports, while carriers employ it for dispatch, tracking, and billing. Freight tariff issues, port congestion, and driver shortages force organizations to seek for technologies providing visibility and flexibility. Online retailers and manufacturers update their old systems with cloud technologies. Security and integration costs are the key challenges. Financial support is derived from venture capital and private equity funding.
⮞In September 2026, the U.S. Bureau of Transportation Statistics reported that its Freight Transportation Services Index for July 2026 was 135.7, down 0.7% from June and 2.0% below July 2025. The index shows the changing freight volumes that logistics systems must manage.
Cloud Logistics Market Segment Analysis
-
By Deployment, the Public Cloud segment dominated the Cloud Logistics Market with approximately 36.58% share in 2025, while the Private Cloud segment is the fastest growing with a CAGR of approximately 14.11%.
-
By Enterprise Size, the Large Enterprises segment dominated the Cloud Logistics Market with approximately 65.34% share in 2025, while the Small & Medium Enterprises segment is the fastest growing with a CAGR of approximately 14.38%.
-
By Service Type, the Transportation Management segment dominated the Cloud Logistics Market with approximately 35.50% share in 2025, while the Supply Chain Analytics segment is the fastest-growing, with a CAGR of approximately 15.20%.
-
By End Use, the Retail & E-Commerce segment dominated the Cloud Logistics Market with approximately 24.08% share in 2025, while the Healthcare segment is the fastest growing with a CAGR of approximately 16.73%.
-
By Operating System, the Web-Based segment dominated the Cloud Logistics Market with approximately 55.43% share in 2025, while the Native segment is the fastest growing with a CAGR of approximately 13.81%.
By Deployment, Public Cloud Dominates the Cloud Logistics Market and Private Cloud Grows Fastest
Public cloud leads because it offers low upfront cost, quick setup and easy scaling during seasonal peaks. Shippers and carriers can start using transportation and warehouse tools within weeks and pay only for what they use. Vendors host the software on large cloud platforms, update it often and connect it to partner networks. Many firms prefer to avoid running their own data centers. Public deployments also make it simple to share data with carriers, suppliers and customers, which is central to modern logistics collaboration.
Private cloud is the fastest growing deployment as large shippers, government-linked firms and regulated industries seek tighter control over sensitive shipment, customer and pricing data. Private setups allow custom security, data residency and integration with older systems. Hybrid models are gaining popularity as companies keep core records in private environments and use public services for analytics and visibility. Rising cyber risk and data localization rules are encouraging this move toward controlled environments.
⮞In July 2026, SAP reported that its cloud revenue rose 22% in the second quarter and that current cloud backlog reached EUR 22.9 billion, up 27%. The numbers show how strongly enterprise supply chain software is moving to the cloud.
By Enterprise Size, Large Enterprises Dominates the Cloud Logistics Market and Small & Medium Enterprises Grows Fastest
Large enterprises dominate because they run complex systems having many warehouses, carriers, and clients and have the resources to afford themselves integrated systems. The global retailers, manufacturers, and logistics service providers need visibility in real time in various countries and means of transport. They enter into contracts at an enterprise level with large software companies. The larger companies benefit most from analysis and automation because even small gains in route planning and inventory placement make huge cost savings.
Small and medium enterprises are the fastest growing group as subscription pricing and simple interfaces lower the barrier to entry. Sellers that are online, regional carriers, and local distributors have access to solutions that were only previously available to large organizations. E-commerce solutions have been providing integrated solutions to include shipping and tracking solutions, hence exposing small merchants to cloud logistics solutions. Merchants are making lighter products, templates and partnering markets, and there is an increased number of cross border sales online.
⮞In February 2026, Eurostat reported that 84.7% of large EU enterprises paid for cloud services in 2025, compared with 66.8% of medium and 49.3% of small enterprises. The gap shows room for growth among smaller firms.
By Service Type, Transportation Management Dominates the Cloud Logistics Market and Supply Chain Analytics Grows Fastest
The Transportation Management segment was leading in the Cloud Logistics Market in 2025. This leadership is attributed to the increasing demand for optimal route planning, reduced freight charges, improved delivery reliability, and enhanced shipment visibility. The cloud-based transportation management systems help organizations manage their transportation activities by coordinating carriers, dispatching, tracking shipments, among others. Increasing e-commerce activity, expanding global trade, and rising demand for efficient last-mile delivery continue to encourage adoption among manufacturers, retailers, distributors, and third-party logistics providers.
It is expected that the Supply Chain Analytics segment will witness high growth in the Cloud Logistics Market. This is because of the rise in the need for data-based logistics planning, predictive forecasting, visibility and real-time decision making. Cloud-based analytics solutions assist organizations to find out any inefficiencies, predict disruptions, measure performance of logistics and optimize their inventory as well as transport networks. With the advancement of artificial intelligence, machine learning and predictive analytics, the above-mentioned factors have been further enhanced.
By End Use, Retail & E-Commerce Dominates the Cloud Logistics Market and Healthcare Grows Fastest
Retail and e-commerce lead because online orders create huge volumes of small shipments that need fast, accurate handling. Retailers use cloud platforms for order routing, inventory placement, carrier selection and last-mile delivery. Customer expectations for same-day or next-day delivery and easy returns force companies to rely on real-time data. Peak seasons require elastic capacity that the cloud provides. Marketplaces and direct-to-consumer brands also depend on fulfillment networks that run on cloud software.
Healthcare is the fastest growing end use as pharmaceutical, medical device and diagnostic companies need cold chain monitoring, traceability and compliance in distribution. Temperature-sensitive biologics, vaccines and clinical trial supplies require continuous tracking and audit trails. Regulations on serialization and good distribution practice push firms to adopt digital platforms. Manufacturing, automotive and food and beverage also expand use as they seek supply chain resilience and visibility across tiers of suppliers.
⮞In August 2026, the U.S. Census Bureau reported that second quarter 2026 e-commerce sales reached USD 340.2 billion, or 17.1% of total retail sales, up 12.2% from a year earlier. The growth underpins retail demand for cloud logistics.
By Operating System, Web-Based Dominates the Cloud Logistics Market and Native Grows Fastest
Web-based platforms lead because they run in any browser, need no installation and are easy to update across users in many locations. Planners, dispatchers, warehouse managers and customers can access dashboards from desktops and tablets. Vendors can roll out new features and security fixes centrally. Web access also simplifies partner onboarding, since a carrier or supplier only needs a login. These advantages have made web delivery the default for most logistics software.
Native applications are the fastest growing type as drivers, warehouse staff and field teams use mobile devices for scanning, proof of delivery, navigation and inspection. Native apps integrate well with device functionalities like cameras, bar code scanners, and GPS capabilities, and they function well even in low connectivity zones. There is also vendor support for creating mobile apps that increase efficiency and lower mistakes. With frontline staff using smartphones and durable devices, native logistics apps are gaining momentum.
⮞In September 2026, Descartes Systems Group reported revenue of USD 201.1 million for the quarter ended July 31, 2026, up about 12%. The result reflects steady demand for cloud-delivered logistics software.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
70.08 |
|
Europe |
Germany |
22.74 |
|
Asia Pacific |
China |
29.73 |
|
Latin America |
Brazil |
44.19 |
|
Middle East & Africa |
Saudi Arabia |
26.57 |
North America Cloud Logistics Market Insights
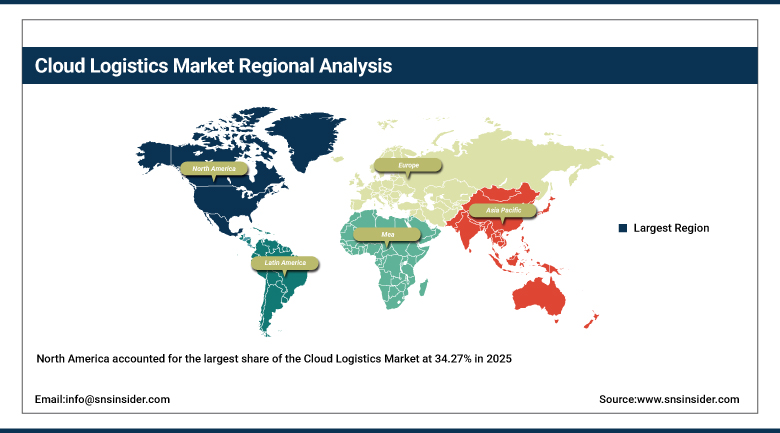
North America accounted for the largest share of the Cloud Logistics Market at 34.27% in 2025, led by the United States. The region has a large e-commerce sector, a dense freight network and many leading vendors of transportation and warehouse software. Canada adds demand through cross-border trade and resource shipments, and Mexico is growing as manufacturing moves closer to U.S. customers. Large shippers and third-party logistics firms are early adopters of AI-enabled tools.
Several forces shape demand. Tariff changes, port congestion and driver shortages push companies to seek greater visibility and flexibility. Venture and private equity investment funds new platforms, and acquisitions are consolidating the vendor base. Cybersecurity concerns are rising, and shippers increasingly ask providers for strong data protection. Regulations on emissions reporting in some states and provinces are also encouraging use of software that calculates carbon footprints.
⮞In September 2026, the Port of Los Angeles reported August volume of 955,907 TEU and a record stretch of more than 2.9 million TEU from June to August. The throughput shows the scale of goods flows that shippers must manage.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Cloud Logistics Market Insights
Europe held significant share of the Cloud Logistics Market in 2025 and is led by Germany, the United Kingdom, France, the Netherlands and Italy. The region has dense trade networks, major ports in Rotterdam, Antwerp and Hamburg and large logistics operators. Cross-border trucking and rail traffic create strong demand for platforms that match loads, track shipments and manage customs documents. Large European carriers and forwarders are also replacing regional systems with shared cloud platforms.
Adoption is affected by policy and sustainability. Emission regulations, and reporting requirements put forward by the European Union lead to the quantification of carbon in logistics operations, whereas data protection laws influence the storage of information on the platform. Digital bill of lading is used in the European Union, which is favorable for the cloud. The port industry is responding to the change in container traffic. Language and rule differences between countries remain a challenge for pan-European roll-outs.
⮞In July 2026, the Port of Rotterdam Authority reported that first-half 2026 container throughput was roughly flat, down 0.1% in TEU, while North American traffic rose 13%. The shifts in trade lanes raise the need for dynamic planning tools.
Asia Pacific Cloud Logistics Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 15.04% during 2026-2035. China, Japan, India, South Korea and Southeast Asia lead. The region is the center of global manufacturing and export, and its e-commerce markets are among the largest in the world. Logistics firms are digitizing quickly, and platforms that coordinate warehouses, trucking and parcel delivery are in strong demand.
The government initiatives and fast pace of development are facilitating the usage of technology. China is striving for digitalization of its logistics and warehousing activities, India is developing a system that would enable integration of multiple transport methods, whereas the Southeastern countries are focusing on development of their ports infrastructure and customs clearance procedure. E-commerce on the international scale increases the number of packages and requires their tracking in real time. The competition among local software providers and foreign suppliers is fierce.
⮞In July 2026, China's Federation of Logistics and Purchasing reported that total social logistics value reached CNY 181.1 trillion in the first half of 2026, up 5.1%. The scale shows the size of the region's logistics economy.
MEA & Latin America Cloud Logistics Market Insights
Latin America and the Middle East and Africa together hold stronger share of the Cloud Logistics Market. In Latin America, Brazil, Mexico, Argentina and Chile lead, with e-commerce, agriculture exports and cross-border manufacturing driving demand. Long distances, road conditions and customs delays make visibility valuable. Local logistics startups and global vendors are building platforms to serve retailers and carriers. Digital payments and mobile commerce are widening the base of shippers who need tracking.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Egypt and South Africa lead. Logistics parks, free zones, and customs modernization projects are included in the economic policies of the Gulf countries. The port authorities and airlines use cloud computing solutions to connect their trading partners. Mobile computing services and trade agreements provide early opportunities for Africa, despite problems with power, connectivity, and funding.
⮞In April 2026, the Panama Canal Authority reported 6,288 transits and 254 million PC/UMS tons of cargo in the first half of fiscal 2026, up about 5% in tonnage. The traffic highlights the role of regional chokepoints in global supply chains.
Growth Drivers: E-Commerce Growth and Supply Chain Volatility Drive Growth in the Cloud Logistics Market
The two major factors behind the demand for cloud logistics services include the rise in e-commerce and the resulting uncertainty in the supply chain. E-commerce provides high volume shipments with very short lead times that require careful coordination. The uncertainties created by changes in trade regulations and port delays have highlighted the costs of lack of visibility. Shippers invest to protect service levels and reduce cost, and carriers adopt the same tools to win business and improve utilization.
The benefits of technology improvements and cost savings provide further fuel for growth. Agents of artificial intelligence can create routes, match loads, and deal with exceptions using minimal human intervention, and Internet of Things sensors provide ongoing data. The subscription-based model reduces the initial cost outlay and offers superior technology to smaller companies. The aim for sustainability will be beneficial too as platforms can assess and monitor emissions. Vendor consolidation is another trend that helps customers implement solutions.
⮞In September 2025, the United Nations Conference on Trade and Development reported that ton-miles in seaborne trade rose nearly 6% in 2024, a record, as rerouting lengthened voyages. Longer routes raise the value of visibility and planning tools.
Restraints: Cyber Risk and Integration Complexity Restrain Growth in the Cloud Logistics Market
Cyber risk restrains growth. Logistics platforms hold sensitive information on shipments, customers, routes and prices, and an attack can halt operations across a network. Ransomware has hit carriers, ports and software providers in recent years, so boards press vendors for strong security and proof of resilience. Concern about data leaving company control makes some shippers hesitant, and regulations on data location add compliance work for global programs.
Integration complexity and cost add further limits. Many companies run older transportation, warehouse and enterprise systems that do not connect easily with cloud tools. Customization takes time and requires specialists. Carriers have different systems and some smaller carriers may lack technical capabilities. Also, change management becomes difficult as the planning team and drivers have to learn new processes. All this can lead to delays and reduced benefits, especially for companies that have low margins.
⮞In April 2026, the FBI's Internet Crime Complaint Center reported USD 20.88 billion in cybercrime losses for 2025, up 26% from 2024, and 3,611 ransomware complaints, up from 3,156 in 2024. The figures show the scale of risk that logistics firms face.
Opportunities: AI Agents and Small Business Adoption Create Opportunities in the Cloud Logistics Market
The biggest area of opportunity lies with the use of AI agents. AI software agents will be able to read through the documents, quote and book the loads, track shipments and handle exceptions on their own without human intervention thus saving several hours. Consumers will not mind paying for any tools that help them get rid of the repetitive coordinating activity. The vendors who can provide the services in an accurate and secure way can even charge for results.
Small business adoption and emerging markets present further potential. Millions of small shippers, carriers and sellers still use spreadsheets and phone calls, and simple cloud tools can bring them online. Pricing by shipment or by truck keeps entry costs low. Marketplaces, banks and telecom firms can distribute logistics software as part of broader services. Growth in India, Southeast Asia, the Gulf and Latin America opens new customers, and sustainability reporting rules create demand for emissions tracking features.
⮞In July 2026, Manhattan Associates reported cloud subscription revenue of USD 126.7 million, up from USD 100.4 million a year earlier. The growth shows strong buyer appetite for cloud supply chain software.
Recent Developments:
-
In October 2026, SAP SE expanded Joule assistants and AI agents for supply chain activities, including planning, manufacturing, and logistics.
-
In August 2026, Oracle Corporation announced further cloud supply chain management capabilities and was recognized in Gartner's 2026 Supply Chain Management Suites Magic Quadrant.
-
In October 2026, Blue Yonder, Inc. updated its Network capabilities covering partner onboarding, data quality, transaction processing, and ecosystem connectivity.
Cloud Logistics Market Key Players
-
SAP SE
-
Oracle Corporation
-
Blue Yonder, Inc.
-
The Descartes Systems Group Inc.
-
project44, Inc.
-
FourKites, Inc.
-
WiseTech Global Limited (E2open)
-
Trimble Inc. (Transporeon)
-
C.H. Robinson Worldwide, Inc.
-
A.P. Moller - Maersk A/S
-
DHL Group
-
Kuehne+Nagel International AG
-
Uber Freight
-
Flexport, Inc.
-
Infor
-
Korber Supply Chain Software
-
MercuryGate International
-
3GTMS
Cloud Logistics Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 27.09 Billion |
| Market Size by 2035 | USD 91.35 Billion |
| CAGR | CAGR of 12.93% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Deployment (Public Cloud, Private Cloud, and Hybrid Cloud) • By Enterprise Size (Large Enterprises and Small & Medium Enterprises) • By Service Type (Transportation Management, Warehouse Management, Fleet Management, and Supply Chain Analytics) • By End Use (Retail & E-Commerce, Manufacturing, Healthcare, Automotive, Food & Beverage, and Others) • By Operating System (Web-Based and Native) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | SAP SE, Oracle Corporation, Manhattan Associates, Inc., Blue Yonder, Inc., The Descartes Systems Group Inc., project44, Inc., FourKites, Inc., WiseTech Global Limited (E2open), Trimble Inc. (Transporeon), C.H. Robinson Worldwide, Inc., Samsara Inc., A.P. Moller - Maersk A/S, DHL Group, Kuehne+Nagel International AG, Uber Freight, Flexport, Inc., Infor, Korber Supply Chain Software, MercuryGate International, 3GTMS |

Frequently Asked Questions
Key players include SAP, Oracle, Manhattan Associates, Blue Yonder, Descartes Systems Group, project44, FourKites, WiseTech Global (E2open), Trimble (Transporeon), C.H. Robinson, Samsara, Maersk, DHL Group, Kuehne+Nagel, Uber Freight and Flexport.
Key opportunities include AI agents for planning and exceptions, adoption by small shippers and carriers, emissions reporting tools and growth in emerging markets.
E-commerce growth and supply chain volatility are the main growth factors, since they raise the need for real-time visibility and flexible planning.
By Deployment, the Public Cloud segment dominated the market in 2025 with an estimated 36.58% share, supported by low upfront cost and easy scaling.
North America dominated the market with a share of 34.27% in 2025, driven by a large e-commerce sector, a dense freight network and many leading software vendors.
