
Commercial Vehicle (CV) Active Power Steering Market Report Scope & Overview:
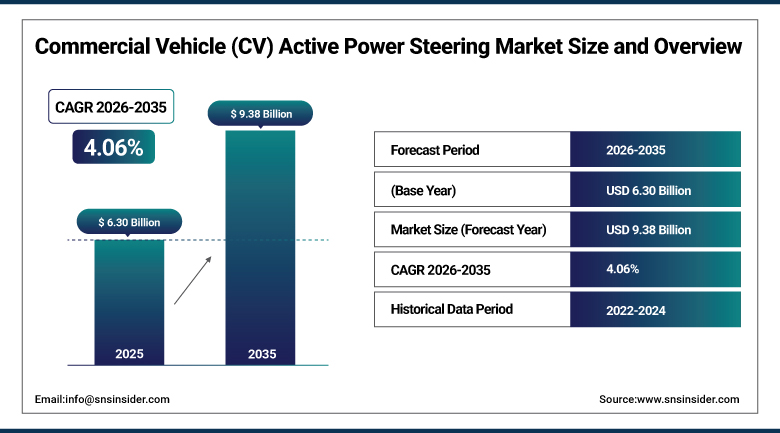
The Commercial Vehicle (CV) Active Power Steering Market was valued at USD 6.30 Billion in 2025 and is expected to reach USD 9.38 Billion by 2035, growing at a CAGR of 4.06% from 2026-2035.
The Commercial Vehicle (CV) Active Power Steering Market is experiencing a paradigm change with CV owners and OEMs shifting focus from entirely hydraulic assisted steering to electric or electro-hydraulic steerings which will help in lowering engine loading, saving fuel consumption, and ease of integration into advanced driving assistance systems. The growth in the market is supported by the continued need for heavy commercial vehicles and logistics trucks where the performance of the steering systems directly impacts the fatigue of drivers, vehicle maneuverability, and cost of ownership of the vehicle. The regulatory push in this regard has prompted suppliers to work on electronically controlled steers that will satisfy the ISO 26262 safety standards. In Europe, there is an EU General Safety Regulation mandating installation of Steering Assistance Systems and Emergency Lane Keeping Systems for new trucks and buses from July 2024 onwards.
In February 2025, ZF Friedrichshafen introduced next-generation steer-by-wire and electric power steering systems with integrated ADAS support, reduced response times, and modular design, with the rollout targeting improved vehicle handling, driver safety, and operational efficiency across light-duty trucks, vans, and crossovers. The launch reflects a broader supplier strategy of extending passenger-vehicle steering innovation into commercial platforms, where the combination of tightening safety regulation and fleet operators' growing appetite for ADAS-compatible steering hardware is expanding the addressable market for suppliers capable of certifying electronically controlled systems to commercial duty-cycle standards.
To Get more information Commercial Vehicle (CV) Active Power Steering Market - Request Free Sample Report
Commercial Vehicle (CV) Active Power Steering Market Trends
- Continued transition from hydraulic to electric and electro-hydraulic steering architectures across heavy-duty truck platforms.
- Accelerating integration of ADAS-compatible steering hardware to comply with EU Steering Assistance System mandates.
- Rising development of steer-by-wire systems eliminating mechanical linkage between steering wheel and front axle.
- Growing supplier investment in modular steering column and rack designs supporting broader vehicle compatibility.
- Expanding regional manufacturing capacity to serve electrification-driven demand in China's commercial vehicle sector.
U.S. Commercial Vehicle (CV) Active Power Steering Market Outlook
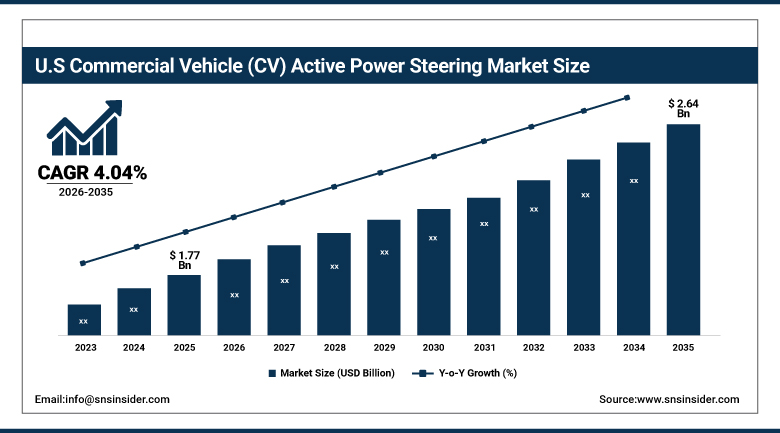
The U.S. Commercial Vehicle (CV) Active Power Steering Market was valued at USD 1.77 Billion in 2025 and is expected to reach USD 2.64 Billion by 2035, growing at a CAGR of 4.04% from 2026-2035.
The U.S. Commercial Vehicle (CV) Active Power Steering Market growth continues to be reinforced by sustained heavy-duty truck production and a logistics sector that depends on maneuverable, low-fatigue steering systems for long-haul and regional freight operations. Domestic demand is increasingly weighted toward electric power steering as fleet operators prioritize fuel efficiency and compatibility with driver-assistance systems now standard on newer truck platforms. Nexteer Automotive, headquartered in Saginaw, Michigan, remains a central supplier to North American truck OEMs, supporting the domestic shift toward electronically controlled steering across both light-duty and heavier commercial applications.
In April 2025, Nexteer Automotive launched its High Output Column-Assist EPS system with torque capability up to 110 Nm, extending electric steering assistance into heavier-duty applications that had previously relied exclusively on hydraulic systems. The launch illustrates how domestic suppliers are closing the torque-capability gap that has historically confined electric power steering to lighter commercial vehicles, a development that is directly expanding the addressable heavy-duty segment for electric steering suppliers competing against entrenched hydraulic system providers.
Commercial Vehicle (CV) Active Power Steering Market Segment Analysis
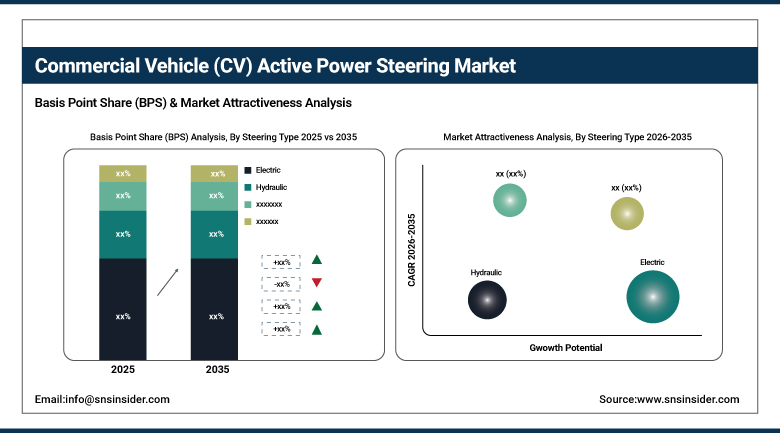
- By Steering Type, the Electric Power Steering segment dominated the Commercial Vehicle (CV) Active Power Steering Market with approximately 61.32% share in 2025, while the Electric segment is the fastest growing with a CAGR of approximately 18.45%.
- By Equipment, the Steering Racks segment dominated the Commercial Vehicle (CV) Active Power Steering Market with approximately 38.60% share in 2025, while the Steering Columns segment is the fastest growing with a CAGR of approximately 9.85%.
- By Vehicle Type, the Heavy Duty Trucks segment dominated the Commercial Vehicle (CV) Active Power Steering Market with approximately 52.40% share in 2025, while the Light Duty Trucks segment is the fastest growing with a CAGR of approximately 7.20%.
- By Application, the Logistics segment dominated the Commercial Vehicle (CV) Active Power Steering Market with approximately 34.75% share in 2025, while the Construction segment is the fastest growing with a CAGR of approximately 8.10%.
- By Distribution Channel, the OEM segment dominated the Commercial Vehicle (CV) Active Power Steering Market with approximately 72.60% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 6.85%.
By Steering Type, Electric Power Steering dominates, and Electric grows fastest
Electric power steering continues to be the most prevalent steering system in the CV Active Power Steering Market owing to the advantages that this system enjoys over its rivals in terms of being fuel-efficient and having reduced parasitic loads. Electric power steering has become increasingly affordable with decreasing costs of electric motors and control systems, putting it on par with hydraulic systems.
Electric power steering is emerging rapidly as suppliers pursue full electronic control of steering input, driven by demand for weight savings, packaging flexibility, and compatibility with higher levels of vehicle automation. As commercial fleets prioritize automation readiness, this segment focuses strongly on redundant fail-operational architectures that satisfy functional safety standards, positioning it as a critical enabler of next-generation autonomous and semi-autonomous commercial platforms.
By Equipment, Steering Racks dominate, and Steering Columns grow fastest
Steering racks remain the dominant equipment category, characterized by their function as the primary mechanical interface translating steering input into wheel movement across nearly every hydraulic and electric power steering architecture deployed in commercial vehicles today. This segment benefits from broad compatibility across vehicle platforms and established manufacturing processes refined over decades of commercial vehicle production.
Steering columns are emerging as the fastest-growing equipment category, driven by supplier investment in column-assist EPS designs capable of extending electric assistance into higher-torque heavy-duty applications. As manufacturers pursue modular column architectures adaptable across multiple truck platforms, this segment focuses strongly on integrating torque sensors and control units directly within the column assembly, thus reducing overall system complexity and installation cost.
By Vehicle Type, Heavy Duty Trucks dominate, and Light Duty Trucks grow fastest
The heavy duty truck segment continues to dominate in terms of its size, being fuelled by the strong demand for freight and construction, which necessitates a durable steering system able to accommodate higher axle weights. The segment will benefit from ongoing cycles of fleet renewal as the old hydraulic steering trucks are replaced by electrically assisted versions that comply with new safety standards.
Light duty trucks are experiencing the most rapid growth, driven by expanding last-mile delivery and e-commerce logistics fleets that favor lighter, more fuel-efficient electric steering architectures already proven in passenger vehicle platforms. As delivery fleet operators prioritize total cost of ownership, this segment focuses strongly on adapting passenger-vehicle EPS technology for commercial-grade durability, positioning light duty trucks as an increasingly attractive entry point for electric steering suppliers.
By Application, Logistics dominates, and Construction & Mining grows fastest
Logistics remains the dominant application segment, with the large volumes of long-distance and regional cargo transportation activities depending on fatigue-free steer-by-wire systems to enable lengthy hours of driving and continuous maneuvering within the logistics hubs. Such an industry segment benefits greatly from the focus of fleet managers on retaining their drivers due to the importance of comfortable steering systems for the safety of their drivers.
Construction is now one of the fastest-growing application areas as a result of continuous investment in infrastructure and the tough off-road nature of operations that necessitates steering solutions designed to withstand more torque production and robustness compared to traditional on-road applications. Fleet managers of construction equipment are keen on electro-hydraulic systems that can withstand tough environmental conditions.
By Distribution Channel, OEM dominates, and Aftermarket grows fastest
OEM remains the dominant distribution channel, characterized by steering systems being specified and installed during original vehicle production to meet increasingly stringent regulatory safety requirements that mandate specific steering assistance and lane-keeping functionality on newly manufactured trucks and buses. This segment benefits from close, long-term supplier relationships with truck manufacturers embedded across multiple vehicle platform generations.
Aftermarket is emerging as the fastest-growing distribution channel, driven by the need to retrofit or replace steering components on an aging global commercial vehicle fleet that continues to operate well beyond typical passenger-vehicle service lives. As fleet operators prioritize extending vehicle service life amid elevated new-truck prices, this segment focuses strongly on expanding replacement part availability for both hydraulic and electric steering systems.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
81.10 |
|
Europe |
Germany |
33.75 |
|
Asia Pacific |
China |
42.90 |
|
Middle East & Africa |
United Arab Emirates |
35.60 |
|
Latin America |
Brazil |
47.85 |
North America Commercial Vehicle (CV) Active Power Steering Market Insights
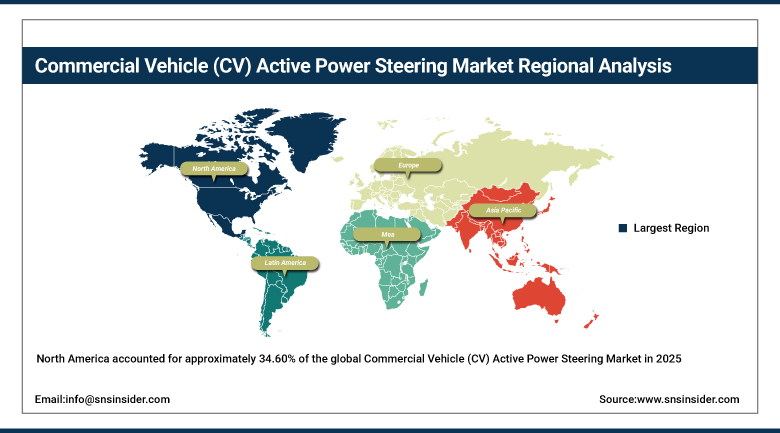
North America accounted for approximately 34.60% of the global Commercial Vehicle (CV) Active Power Steering Market in 2025, remaining the largest regional market on the strength of a mature heavy-duty truck manufacturing base and an established supplier network serving both OEM and aftermarket channels. The USA remains a major player in regional demand, due to continuous manufacturing of Class 8 trucks along with logistics industry, wherein fleet owners prefer electric power steering in order to cut down on fuel consumption.
Truck manufacturers operating in the region continue to source steering systems from established Tier 1 suppliers including Nexteer Automotive and ZF Friedrichshafen, both of which maintain dedicated commercial vehicle engineering and testing capability within North America. Canada contributes additional regional demand through its own freight and resource-extraction vehicle fleets, which similarly depend on rugged, high-torque steering systems suited to extended operating conditions.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Commercial Vehicle (CV) Active Power Steering Market Insights
Asia Pacific is projected to expand at a CAGR of approximately 8.60% from 2026 to 2035, the fastest of any region, driven by China's dual position as the world's largest commercial vehicle production base and a rapidly electrifying truck fleet under national new-energy vehicle policy. The case of ZF Friedrichshafen increasing its manufacturing facilities for electric power steering systems by 3,700 square meters at the end of 2024 in Anting, Shanghai, is one example that shows how suppliers are increasing regional capacity to address Chinese fleet electrification.
India has recorded one of the highest growth rates for an individual nation in the region owing to the growing commercial vehicle manufacturing industry in India as well as the government investment programs in infrastructure, which are helping increase truck registrations. Japan and South Korea, on the other hand, have contributed additional demand from the region due to the presence of truck manufacturing industries that use electric and electro-hydraulic steering systems.
Europe Commercial Vehicle (CV) Active Power Steering Market Insights
Europe represents a mature Commercial Vehicle (CV) Active Power Steering Market, shaped decisively by the EU General Safety Regulation's mandate for Steering Assistance Systems and Emergency Lane Keeping Systems on newly manufactured trucks and buses beginning in July 2024. Germany will remain the primary regional market driven by a significant presence of heavy truck OEMs and steering system suppliers like ZF Friedrichshafen and thyssenkrupp that have significant engineering facilities for commercial vehicles in Germany.
France and Italy will be among the other regions driving demand for commercial vehicles manufactured in their respective countries, and further compliance with the General Safety Regulation across all new trucks and buses will drive continuous demand for advanced steering systems in the forecast period.
MEA & Latin America Commercial Vehicle (CV) Active Power Steering Market Insights
The Middle East & Africa Commercial Vehicle (CV) Active Power Steering Market is expanding as Gulf Cooperation Council states invest in logistics and construction infrastructure tied to broader economic diversification programs, with the United Arab Emirates driving regional demand given its position as a major freight transshipment hub requiring extensive heavy-duty truck fleets.
Latin America is led by Brazil, where a substantial domestic commercial vehicle manufacturing base and sustained agricultural and mining freight activity continue to drive demand for both hydraulic and electric power steering systems. Mexico contributes additional regional demand through its growing role as a nearshore manufacturing and logistics hub serving North American supply chains.
Market Dynamics
Growth Drivers: Regulatory Mandates and Fleet Electrification
The EU General Safety Regulation that required new trucks and buses to be equipped with Steering Assistance System (SAS) and Emergency Lane Keeping System (ELKS) starting from July 2024 is considered the sole factor driving the Commercial Vehicles (CV) Active Power Steering market, thus forcing manufacturers to develop more rapidly electronically assisted power steering solutions that can comply with the functional safety requirements on tough CV cycles.
Parallel electrification of commercial vehicle fleets, particularly in China under national new-energy vehicle policy, is reinforcing this driver by creating natural demand for electric and electro-hydraulic steering architectures that integrate more efficiently with electric powertrains than legacy hydraulic pump systems, which impose a continuous parasitic load regardless of vehicle propulsion type.
Restraints: High System Cost and Heavy-Duty Torque Limitations
The higher upfront cost of electric and steer-by-wire steering systems relative to conventional hydraulic assistance remains a meaningful restraint, particularly for cost-sensitive fleet operators purchasing high volumes of heavy-duty trucks where incremental per-unit steering system cost accumulates significantly across large fleet orders.
Historical constraints regarding torque production from electric power steering compared with hydraulic power steering limited its use in the most heavy-duty applications, such as class 8 trucks for long-haul transport and construction machinery, where higher steering force was necessary in these situations because of load, while fuel consumption was less efficient.
Opportunities: ADAS Integration and Emerging Market Fleet Expansion
The continued introduction of ADAS into commercial vehicle steering is a lucrative opportunity for suppliers, as fleet owners continue to seek more of lane-keeping assistance, autonomous emergency steering, and other safety systems, which can only be provided by electronics-driven steering components and not the conventional hydraulics.
Expansion into emerging commercial vehicle markets with steering solutions tailored to local fleet requirements presents a further opportunity, particularly in regions where rising freight and construction activity is driving new truck registrations. Suppliers developing cost-optimized electric steering variants suited to these markets are positioned to capture incremental demand as emerging-market fleets gradually transition away from purely mechanical and hydraulic steering systems.
Recent Developments:
- 2026: JTEKT named its steer-by-wire system Syncusteer and began proposing the technology to customers as part of its next-generation mobility strategy, strengthening its portfolio of advanced steering systems.
- 2026: Schaeffler presented new chassis and body technologies covering steering, braking, sensors and force-feedback actuators, highlighting integrated and connected chassis technologies for next-generation vehicles.
- 2025: TRW Automotive unveiled upgraded hydraulic and electro-hydraulic steering lines for pickup trucks and light commercial vehicles, emphasizing higher precision, durability, and reduced driver effort. The initiative targets fleet operators, OEMs, and premium vehicle manufacturers seeking enhanced steering performance and reliability.
Commercial Vehicle (CV) Active Power Steering Market Key Players are:
- Robert Bosch GmbH
- JTEKT Corporation
- ZF Friedrichshafen AG
- thyssenkrupp AG
- Mando Corporation
- Schaeffler AG
- Nexteer Automotive Corporation
- NSK Ltd.
- China Automotive Systems, Inc.
- Hitachi Astemo, Ltd.
- Mitsubishi Electric Corporation
- Knorr-Bremse AG
- R. H. Sheppard Co., Inc.
- Ognibene Power S.p.A.
- Pailton Engineering Ltd.
- TRW Automotive
- Global Steering Systems LLC
- ST System Truck S.p.A.
- Mahindra & Mahindra Ltd.
- Denso Corporation
Commercial Vehicle (CV) Active Power Steering Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 6.30 Billion |
| Market Size by 2035 | USD 9.38 Billion |
| CAGR | CAGR of 4.06% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Steering Type (Hydraulic, Electric, Electro-Hydraulic) • By Equipment (Steering Racks, Steering Columns, Steering Wheels, Torque & Angle Sensors, Steering Actuators, Others) • By Vehicle Type (Heavy Duty Trucks, Medium Duty Trucks, Light Duty Trucks, Buses) • By Application (Logistics, Construction, Mining, Public Transit, Others) • By Distribution Channel (OEM, Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Robert Bosch GmbH, JTEKT Corporation, ZF Friedrichshafen AG, thyssenkrupp AG, Mando Corporation, Schaeffler AG, Nexteer Automotive Corporation, NSK Ltd., China Automotive Systems, Inc., Hitachi Astemo, Ltd., Mitsubishi Electric Corporation, Knorr-Bremse AG, R. H. Sheppard Co., Inc., Ognibene Power S.p.A., Pailton Engineering Ltd., TRW Automotive, Global Steering Systems LLC, ST System Truck S.p.A., Mahindra & Mahindra Ltd., Denso Corporation. |
Frequently Asked Questions
Key players in the Commercial Vehicle (CV) Active Power Steering Market include Robert Bosch GmbH, JTEKT Corporation, ZF Friedrichshafen AG, thyssenkrupp AG, and Mando Corporation, among others.
Key opportunities lie in integrating ADAS-compatible steering hardware to meet fleet safety demands, and in expanding into emerging commercial vehicle markets with cost-optimized electric steering solutions tailored to local fleets.
The EU General Safety Regulation's mandate for Steering Assistance Systems on newly manufactured trucks and buses, combined with parallel commercial fleet electrification, is the major growth factor.
By Steering Type, the Electric Power Steering segment dominated the Commercial Vehicle (CV) Active Power Steering Market with approximately 61.32% share in 2025.
North America dominated the Commercial Vehicle (CV) Active Power Steering Market with approximately 34.60% share in 2025, supported by a mature heavy-duty truck manufacturing base.
