
Connected Infrastructure Market Report Scope & Overview:
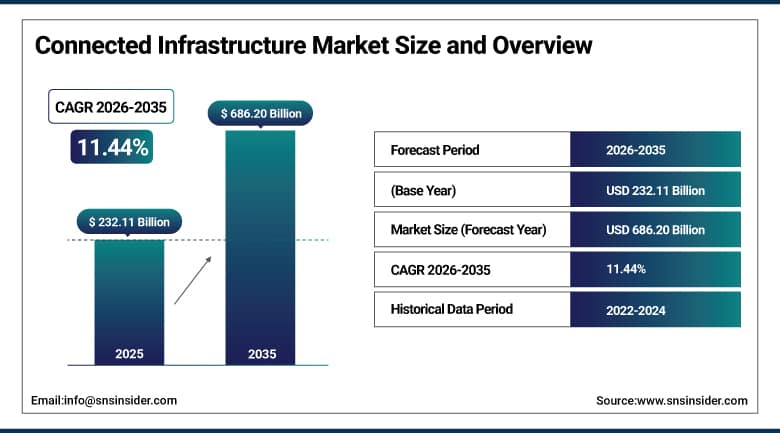
The Connected Infrastructure Market was valued at USD 232.11 Billion in 2025 and is expected to reach USD 686.20 Billion by 2035, growing at a CAGR of 11.44% from 2026 to 2035.
The Connected Infrastructure Market is growing significantly owing to factors such as rising urbanization, increased investment in smart city projects, and widespread adoption of emerging digital technologies including IoT, Artificial Intelligence, 5G, and cloud computing. There is a continuous trend of developing new-age infrastructure in sectors like transport, energy, healthcare, and security. Rising requirements for connectivity, automation, and decision-making based on data analysis are fueling the expansion of the global market. Moreover, emphasis on energy management, predictive maintenance, infrastructure resiliency, and digital transformation is leading to the implementation of connected solutions.
Honeywell completed its acquisition of LenelS2 in 2026 for approximately USD 4.95 billion, strengthening its Honeywell Forge building automation platform with expanded access control and security system capabilities, reflecting the accelerating pace of consolidation among leading connected infrastructure and building automation vendors.
Market Size and Forecast
-
Market Size in 2026E: USD 258.70 Billion
-
Market Size by 2035: USD 686.20 Billion
-
CAGR: 11.44% from 2026 to 2035
-
Fastest Growing Region: Asia Pacific
-
Largest Region: North America
To Get More Information On Connected Infrastructure Market - Request Free Sample Report
Connected Infrastructure Market Trends
-
Rising integration of AI-driven predictive maintenance is transforming connected infrastructure from reactive monitoring toward proactive asset management.
-
Growing deployment of digital twin platforms is enabling real-time simulation and optimization of buildings, grids, and transportation networks.
-
Expanding 5G network rollout is accelerating demand for connected sensors, edge computing platforms, and intelligent transportation systems.
-
Increasing consolidation among leading building automation and infrastructure software vendors is reshaping the competitive landscape through acquisitions.
-
Rising emphasis on grid resilience and electrification is driving demand for connected microgrid and smart energy management solutions.
U.S. Connected Infrastructure Market Outlook
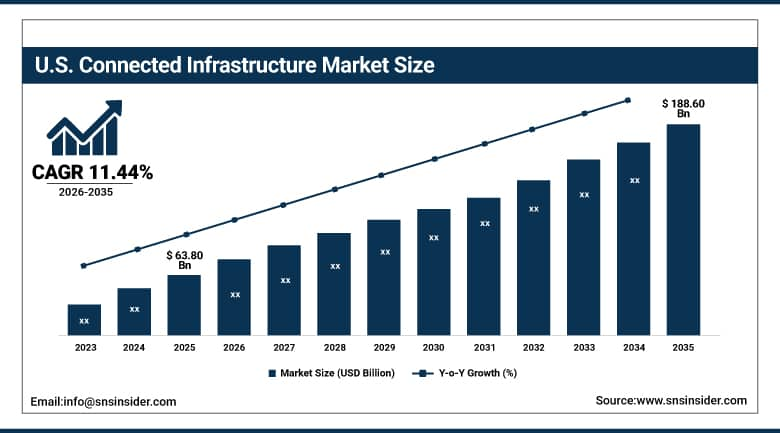
The U.S. Connected Infrastructure Market was valued at USD 63.80 Billion in 2025 and is projected to reach USD 188.60 Billion by 2035, growing at a CAGR of 11.44% during 2026-2035.
A large number of investment dollars from the federal and state government in the digitization of the infrastructure, along with the presence of key players in building automation and connectivity solutions, have made sure that the demand for connected infrastructure remains strong in the United States. Organizations in the commercial real estate, utilities, and transportation segments are still emphasizing investments in connected infrastructure to cut down their operating costs and report compliance effectively. The increasing number of smart city programs, along with the expansion of 5G networks, has strengthened the demand for connected infrastructure solutions.
Siemens acquired Brightly Software in 2025 for approximately USD 1.575 billion, expanding its Building X digital twin and asset management platform with expanded facility and infrastructure management capabilities for connected infrastructure customers across educational, government, and commercial real estate markets in the United States.
Connected Infrastructure Market Segment Analysis
-
By Technology, Internet of Things (IoT) segment dominated the Connected Infrastructure Market in 2025 with 31% share; Artificial Intelligence (AI) segment is the fastest growing segment.
-
By Deployment, Cloud-Based segment dominated the market in 2025 with 52% share; Hybrid segment is the fastest growing segment.
-
By Infrastructure Type, Smart Transportation segment dominated the market in 2025 with 24% share; Smart Healthcare segment is the fastest growing segment.
-
By End User, Government & Public Sector segment dominated the market in 2025 with 34% share; Commercial Enterprises segment is the fastest growing segment.
By Technology, Internet of Things (IoT) Segment Dominated the Market, While Artificial Intelligence (AI) Segment Is the Fastest Growing
The Internet of Things (IoT) segment dominated the Connected Infrastructure Market in 2025 as IoT has been considered the key driver for the connection of physical entities, sensors, and communication networks that comprise infrastructure systems. IoT supports constant data collection, remote monitoring of assets, predictive maintenance, and automated operations, which increase efficiency while decreasing operating costs. The deployment of IoT on a broad scale within transportation, utilities, buildings, and public infrastructure made IoT an essential technology for developing connected infrastructure on a large scale.
The Artificial Intelligence (AI) segment is the fastest growing in the Connected Infrastructure Market due to the need for analytical abilities, automation, and predictive decision making of enterprises. AI processes large amounts of infrastructure data to increase efficiency in traffic management, energy consumption, asset maintenance, and public safety operations. Investments into the development of smart cities, digital transformation, and autonomous infrastructure management have boosted AI adoption.
By Deployment, Cloud-Based Segment Dominated the Market, While Hybrid Deployment Segment Is the Fastest Growing
The Cloud-Based segment dominated the Connected Infrastructure Market in on account of its features such as scalability, centralization of data and cost-effectiveness. Cloud-based systems allow users to store, analyze, gather, process, monitor and connect infrastructure data remotely from different places. This segment leads as a result of its ability to incorporate IoT devices, AI applications and analytics in an organization without having substantial infrastructure within the enterprise.
The Hybrid deployment segment is the fastest growing due to the increasing need of combining cloud scalability with on-site data control by organizations. Hybrid architecture enables companies and organizations to manage infrastructure information locally and simultaneously use cloud services for storage and management of applications. The increase in cyber security threats and demands for regulatory compliance in the digital infrastructure have contributed to the increased use of hybrid deployment models.
By Infrastructure Type, Smart Transportation Segment Dominated the Market, While Smart Healthcare Segment Is the Fastest Growing
The Smart Transportation segment dominated the Connected Infrastructure Market in 2025 owing to increased investments in smart traffic management, connected mobility solutions, and upgrading of public transport. Connected sensors, traffic monitoring systems, and communications networks have been deployed to minimize congestion, ensure safety on the roads, and increase transportation efficiency. Expansion of smart cities and connected vehicle ecosystem has contributed towards the dominance of the segment in infrastructure development.
The Smart Healthcare segment is the fastest growing driven by continuous adoption of connected technology in healthcare institutions for improved patient care, operational efficiencies, and hospital administration. The connected medical devices, remote patient monitoring systems, artificial intelligence-based diagnostics and healthcare infrastructure facilitate faster clinical decision-making and optimal use of resources. Increasing digital transformation in healthcare, expanding telemedicine services, and rising investments in smart hospitals drive the adoption of connected healthcare infrastructure.
By End User, Government & Public Sector Segment Dominated the Market, While Commercial Enterprises Segment Is the Fastest Growing
The Government & Public Sector segment dominated the Connected Infrastructure Market in 2025 since government agencies have been consistently spending a lot on smart cities, transport, utilities, and public safety. Governments prefer connected infrastructure to enable better urban planning, effective emergency responses, enhanced service delivery, and operational efficiencies. Modernization plans, supportive policies on digital infrastructure, and investments made by governments will continue driving wide deployment of connected infrastructure technology within national infrastructures.
The Commercial Enterprises segment is the fastest growing owing to the increasing uptake of connected infrastructure technology for enhancing operational efficiencies and sustainability, business continuity. Businesses are deploying smart buildings, intelligent energy, connected manufacturing facilities, and automated workplaces to cut down expenses and optimize the use of assets. Digital transformation plans, real-time operational visibility needs, and IoT and artificial intelligence (AI) technology adoption will speed up the adoption of connected infrastructure technologies in the market.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
Germany |
22.70% |
|
Asia Pacific |
China |
40.80% |
|
Middle East & Africa |
UAE |
26.30% |
|
Latin America |
Brazil |
32.60% |
North America Connected Infrastructure Market Insights
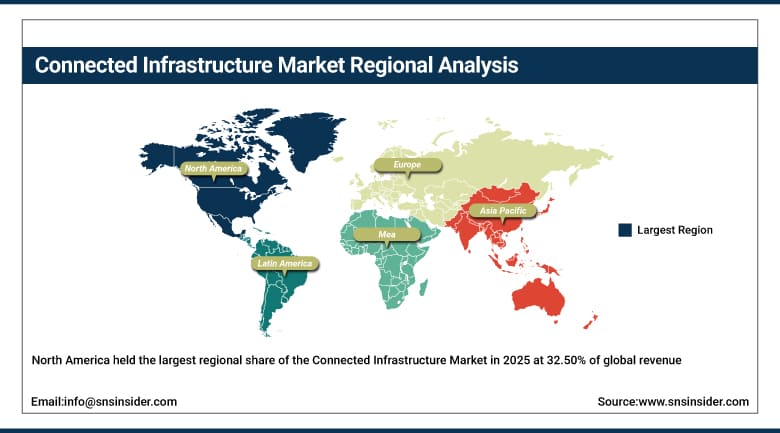
North America held the largest regional share of the Connected Infrastructure Market in 2025 at 32.50% of global revenue, anchored by strong government and enterprise investment in digital infrastructure modernization and a dense concentration of leading connectivity and building automation vendors. Substantial federal infrastructure funding programs, combined with widespread commercial real estate adoption of connected building systems, continue to reinforce the region's leadership position across the broader connected infrastructure landscape.
The United States accounted for approximately 84.60% of the North American market in 2025, reflecting its large commercial real estate base, substantial infrastructure funding programs, and concentration of leading connected infrastructure vendors. Canada is contributing to regional growth through provincial smart city investment and expanding utility modernization programs supporting broader national infrastructure resilience initiatives.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Connected Infrastructure Market Insights
Europe represented a significant share of the global Connected Infrastructure Market in 2025, as the result of aggressive EU regulations promoting sustainability and energy efficiency, which is leading to the development of connected buildings and grids across major members of the European Union. Regulatory pressure around carbon reduction in Europe is making businesses and governments in Europe prioritize investments in connected infrastructure in both Western European markets and Eastern European infrastructure expansion.
Germany had a 22.70% regional share in 2025 due to its strong industrial economy and substantial investments in digital infrastructure improvement by the government. The UK, France, and Nordic countries also play an important role in the regional market as well, due to ambitious sustainability goals and smart cities infrastructure development.
Asia Pacific Connected Infrastructure Market Insights
The Asia Pacific region is expected to have the fastest CAGR in the forecast period 2026-2035 owing to increasing urbanization, massive smart city investments from governments, and increasing connectivity and sensors manufacturing capabilities in China, India, and Southeast Asia regions. The growing middle class and increasing investments in digital infrastructure continue to sustain the strong growth trend of this region compared to other developed markets such as North America and Europe.
In 2025, the Asia Pacific region was led by China at about 40.80% due to its massive investments in national smart cities and digital infrastructure, as well as a fast-growing connectivity manufacturing industry. Japan, South Korea, and India are some of the countries contributing to the growth of this region through massive investments in 5G networks, industrial automation, and smart city programs.
Middle East & Africa and Latin America Connected Infrastructure Market Insights
Connected infrastructure market in Middle East & Africa and Latin America are relatively in earlier stages but show stable growth on account of government diversification policies and urbanization that encourage investments in digital infrastructure. In particular, Middle Eastern countries are building connected infrastructure as a part of smart cities and giga projects, which are being built due to large sovereign investments in digital infrastructure transformation.
The UAE was the leader in the Middle East & Africa market with 26.30% regional share in 2025 owing to large sovereign investments in smart city and digital infrastructure as part of its economic diversification strategy. Brazil accounted for 32.60% of the Latin American market in 2025, owing to increased municipal infrastructure investments. Mexico is also contributing to the growth of the region through nearshoring-led industrial infrastructure development.
Growth Drivers: Smart City Investment and 5G Expansion Driving Market Growth
The main factors behind the growth of the Connected Infrastructure Market include the growing expenditure on modernization initiatives of cities, buildings, utilities, expansion of 5G networks, and decreasing costs of sensors and connectivity hardware. Both public and private organizations see connected infrastructure not as a luxury but a must-have investment for improving efficiency, reducing costs, and ensuring compliance with regulations.
Increasing usage of AI-enabled predictive analytics is adding more value to connected infrastructure by turning it from simple monitoring into proactive asset management and cost optimization. Growing sustainability ambitions of companies and strict energy efficiency requirements push enterprises to invest in connected buildings and grids infrastructure. The consolidation of the leading infrastructure software providers via strategic acquisitions is also contributing to the rapid advancement of platforms' capabilities.
Restraints: High Deployment Costs and Integration Complexity Limiting Market Expansion
Though the demand environment is favorable, there are significant constraints that the market will have to contend with, including the high amount of capital necessary for the deployment of connected infrastructure. Small companies or constrained municipalities find themselves without enough capital resources to engage in comprehensive modernization and settle for more limited deployment strategies, which increase their time to full-scale implementation significantly relative to other customers.
The complexities of integration between older infrastructure and the new connected systems have remained difficult, usually calling for expensive middleware solutions or replacement of legacy infrastructure instead of upgrades. With the increased concern about cybersecurity with the rising number of connected physical infrastructure, companies will have to make significant investments towards security monitoring and threat prevention in connected infrastructure.
Opportunities: AI-Driven Analytics and Emerging Market Expansion Creating New Growth Avenues
There is significant opportunity in the ongoing development of AI-based predictive analytics and digital twin technologies, which can turn connected infrastructure into an actively managed and autonomous system that can deliver quantifiable savings. Those vendors who can prove their value by reducing maintenance expenses and improving asset management will be well-placed to drive adoption past today’s regulatory-driven standards.
New developing markets such as Asia Pacific, Middle East, and Latin America are another source of opportunities due to increasing urbanization and government spending on infrastructure. Finally, 5G networks expansion and declining connectivity hardware prices are opening up new segments among rural and secondary cities within developed and developing countries.
Recent Developments
-
2026: Honeywell completed its acquisition of LenelS2 for approximately USD 4.95 billion, strengthening its Honeywell Forge building automation platform with expanded access control and security capabilities.
-
2025: Siemens acquired Brightly Software for approximately USD 1.575 billion, expanding its Building X digital twin and asset management platform for connected infrastructure customers.
-
2026: Johnson Controls acquired Nantum AI, adding autonomous building operations capability to its OpenBlue platform running natively on Microsoft Azure.
-
2026: Schneider Electric expanded its EcoStruxure platform through the acquisition of an 80% stake in Planon, strengthening integrated facility and infrastructure management software capabilities.
Connected Infrastructure Market Key Players
-
Cisco Systems
-
Siemens AG
-
Schneider Electric
-
Honeywell International Inc.
-
ABB Ltd.
-
Huawei Technologies Co., Ltd.
-
Ericsson
-
Nokia Corporation
-
IBM Corporation
-
Microsoft Corporation
-
Amazon Web Services, Inc.
-
Oracle Corporation
-
Hitachi, Ltd.
-
Dell Technologies
-
Intel Corporation
-
Qualcomm Technologies, Inc.
-
Advantech Co., Ltd.
-
SAP SE
Connected Infrastructure Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 232.11 Billion |
| Market Size by 2035 | USD 686.20 Billion |
| CAGR | CAGR of 11.44% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Internet of Things (IoT), Artificial Intelligence (AI), 5G Networks, Cloud Computing, Big Data Analytics, Edge Computing, Blockchain) • By Deployment (On-Premises, Cloud-Based, Hybrid) • By Infrastructure Type (Smart Transportation, Smart Energy & Utilities, Smart Buildings, Smart Water Management, Smart Healthcare, Smart Public Safety, Others) • By End User (Government & Public Sector, Transportation & Logistics, Energy & Utilities, Healthcare, Commercial Enterprises, Industrial, Residential) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Cisco Systems, Siemens AG, Schneider Electric, Honeywell International Inc., Johnson Controls, ABB Ltd., Huawei Technologies Co., Ltd., Ericsson, Nokia Corporation, IBM Corporation, Microsoft Corporation, Amazon Web Services, Inc., Oracle Corporation, Hitachi, Ltd., Bosch Group, Dell Technologies, Intel Corporation, Qualcomm Technologies, Inc., Advantech Co., Ltd., SAP SE |
Frequently Asked Questions
The Connected Infrastructure Market is expected to grow at a CAGR of 11.44% from 2026 to 2035.
The Connected Infrastructure Market was valued at USD 232.11 Billion in 2025.
The market is driven by rising government and enterprise investment in smart city, building, and utility modernization programs, expanding 5G network rollout, and falling sensor costs.
The Cloud-Based segment dominated the Connected Infrastructure Market in 2025.
The North America region dominated the Connected Infrastructure Market in 2025.
