
Digestive Health Products Market Report Scope & Overview:
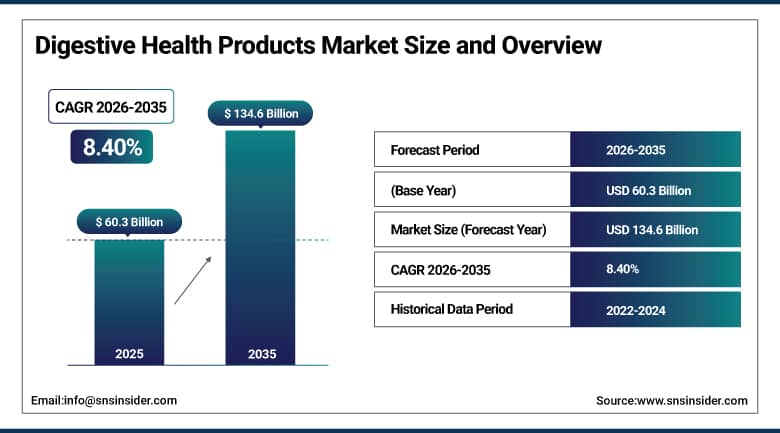
The Digestive Health Products Market was valued at USD 60.3 Billion in 2025 and is expected to reach USD 134.6 Billion by 2035, growing at a CAGR of 8.40% from 2026 to 2035.
There is a huge demand for digestive health products, with the industry showing high growth rate due to increasing awareness about gut-microbiota health association among consumers, thanks to scientific communication from government organizations and evidence sharing from the corporations. Digestive health products include probiotics, prebiotics, fortified food and drinks, digestive enzyme supplements, medical nutrition, and unique ingredients that improve gut health, gut microbiota balance, and nutrient absorption. There are also other factors such as the emphasis placed by the national institutes of health and the U.S. food and drug administration on the role of gut microbiota in enhancing immunity, metabolism, and mental health.
The World Health Organization recommends at least 400 grams of fruit and vegetables per day and at least 25 grams of naturally occurring dietary fiber per day for adults, with such institutional guidance continuing to strengthen consumer trust in clinically validated probiotics, prebiotics, digestive enzymes, and fiber supplements across the broader digestive health products category worldwide.
To Get More Information On Digestive Health Products Market - Request Free Sample Report
Digestive Health Products Market Trends
- Rising demand for clinically supported probiotics and digestive enzyme formulations is driving growth beyond traditional food-based solutions.
- Growing personalization and health-monitoring technologies are enabling more targeted digestive health formulations.
- Increasing adoption of plant-based diets is supporting vegan-friendly prebiotic and probiotic products.
- Expanding clean-label positioning and digital visibility are strengthening demand for probiotic-enriched digestive health products.
- Strategic partnerships are supporting development of diverse, application-specific digestive health product portfolios.
The U.S. Digestive Health Products Market Outlook
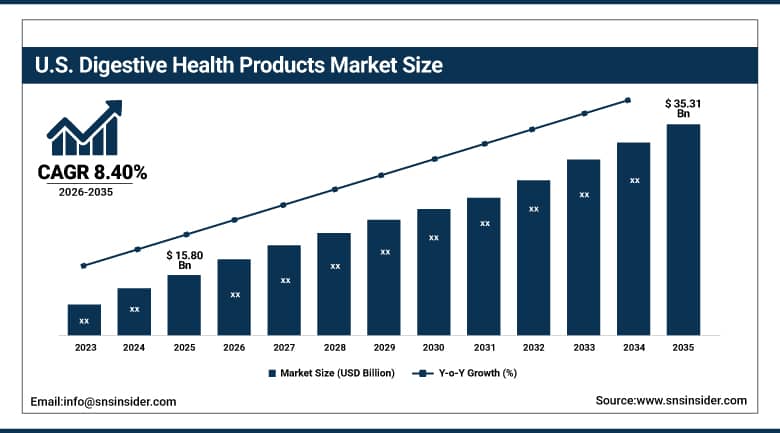
The U.S. digestive health products market was valued at USD 15.80 Billion in 2025 and is projected to reach USD 35.31 Billion by 2035, growing at a CAGR of 8.40% during 2026–2035.
The top producers of food, beverages, and dietary supplements in the nation have not only been developing more products targeting digestive health but are being encouraged by consumers' increasing understanding of the link between gut and overall body health. The growing trust of consumers towards the products regulated by the FDA, which includes strain-specific probiotics, enzyme mixtures, and prebiotic fibers, has not only increased but is supported by the continuous development of products with probiotics, clean label, and immunity.
Seed Health increased its market reach within the United States through the launch of its clinically proven DS-01 Daily Synbiotic and DS-01 14 Day Gut Reset throughout the 450 Sprouts Farmers Market stores in 24 states in June 2025 along with their online presence, indicating the increasing trend towards science-based digestive health products and omnichannel marketing.
Digestive Health Products Market Segment Analysis
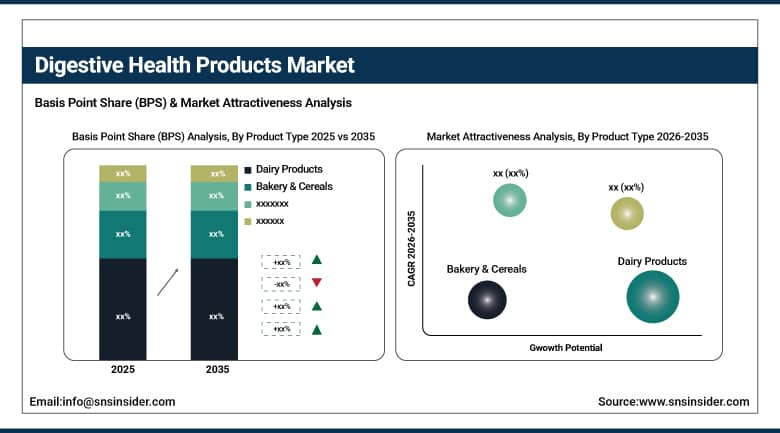
- By Product Type, dairy products dominated the digestive health products market with a 73.80% share in 2025, while functional foods & beverages is the fastest-growing product type segment with a CAGR of 9.20% from 2026–2035.
- By Ingredient Type, prebiotics dominated the digestive health products market with a 49.60% share in 2025, while food enzymes is the fastest-growing ingredient type segment with a CAGR of 9.40% from 2026–2035.
- By Distribution Channel, supermarkets/hypermarkets dominated the digestive health products market with a 54.60% share in 2025, while online retail is the fastest-growing distribution channel segment with a CAGR of 9.80% from 2026–2035.
- By Age Group, adult dominated the digestive health products market with a 62.60% share in 2025, while geriatric is the fastest-growing age group segment with a CAGR of 9.60% from 2026–2035.
By Product Type, dairy products dominated the digestive health products market, while functional foods & beverages is the fastest-growing segment.
According to the types of products, the digestive health dairy products category accounted for the highest market share of 73.80% in 2025. The dairy products continue to be the leading category due to the consumer acceptance of such products as a delivery system for probiotics and prebiotics. Among these, yogurt, kefir, and milk products are the most consumed digestive health products.
The functional foods & beverages segment is expected to register the fastest CAGR of 9.20% during the forecast period 2026-2035. By product type, the functional foods and beverages segment will lead the market as increasing prevalence of digestive problems and rising willingness to spend on gut health continue driving strong demand for fortified, non-dairy digestive health product formats.
By Ingredient Type, prebiotics dominated the digestive health products market, while food enzymes is the fastest-growing segment.
In 2025, prebiotics hold a dominating position within the market with more than 49.60% of shares within the digestive health products market in terms of ingredients. This domination was mainly due to increasing usage of prebiotics fibers within daily food, drinks, and dietary supplements that aim at maintaining natural gut health, as customers preferred prebiotics owing to the simplicity of ingredients involved.
The food enzymes segment is anticipated to grow at a CAGR of 9.40% from 2026 to 2035. The multipurpose applications of food enzymes, coupled with an increase in the demand for enzyme cultures by the food and beverages industry, is expected to fuel segment growth owing to the inclusion of digestive enzyme mixtures in functional foods and dietary supplements.
By Distribution Channel, supermarkets/hypermarkets dominated the digestive health products market, while online retail is the fastest-growing segment.
Based on distribution channel, the supermarkets and hypermarkets segment is dominated the market with an enormous share in 2025, driven by convenience shopping and several consumer and retail incentives. Supermarkets and hypermarkets remain the dominant channel owing to their broad product assortment spanning dairy, functional food, and supplement categories, offering consumers convenient access to digestive health products across a single shopping trip.
The Online Retail segment is expected to witness the fastest CAGR of 9.80% during the forecast period 2026-2035. Consumer confidence in buying digestive health supplements and functional foods online along with the increasing adoption of subscription models is contributing to exponential growth in online distribution as more consumers are now doing their research online to buy strain-specific probiotics.
By Age Group, adult dominated the digestive health products market, while geriatric is the fastest-growing segment.
Based on age group, the adult group is the largest in terms of market share in 2025, based on increased awareness about gut health. The adults are the largest age group in terms of category, due to wide purchasing capability and health management practices, making them the largest and most reliable consumer category.
The Geriatric segment is expected to register the fastest CAGR of 9.60% during the forecast period 2026-2035. Key drivers such as increasing health awareness and the aging population are propelling growth, particularly in the probiotics and chewable segments, as older consumers increasingly seek digestive health support addressing age-related gastrointestinal and nutrient absorption changes.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
68.10% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
China |
44.60% |
|
Middle East & Africa |
UAE |
25.60% |
|
Latin America |
Brazil |
37.70% |
North America Digestive Health Products Market Insights
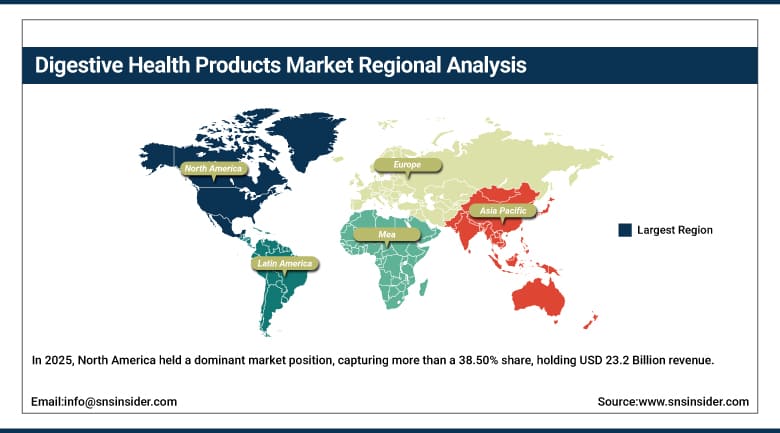
In 2025, North America held a dominant market position, capturing more than a 38.50% share, holding USD 23.2 Billion revenue. Digestive health products have moved from a niche wellness segment into a broader preventive-nutrition space as leading health authorities frame digestive health through everyday diet quality.
The US was the leading country within the North America digestive health products market in 2025, driven by rising consumer awareness of the gut-systemic health connection reinforced by NIH and FDA scientific communication. Canada is contributing to regional growth through its own expanding natural health product retail sector and growing consumer interest in gut microbiome wellness.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Digestive Health Products Market Insights
The Europe digestive health products market was a major contributor in 2025. This has been attributed to the existence of stringent regulatory frameworks that favor health claims on functional foods in the region, increasing consumer demands for clean label probiotics and prebiotics, and an increasing aged population who need digestion health support.
Germany is one of the key markets in Europe due to the presence of a strong base for milk and functional food processing industry and the increasing demand from consumers for gut health-related products. Other countries include France, known for the high manufacturing activity of probiotic yogurts by Danone, and the United Kingdom.
Asia Pacific Digestive Health Products Market Insights
Asia Pacific dominated the digestive health market with a market share of 46.48% in a related market scope, with the region's growth supported by high product demand in countries like China, India, and Japan, and strong daily sales performance from established probiotic brands. Asia-Pacific is considered the fastest-growing region in the broader digestive health products market.
China is one of the main growth drivers in the Asia Pacific digestive health products market, owing to its massive consumer base and rapidly expanding functional food and dairy manufacturing capacity. Japan, home to Yakult Honsha's globally recognized probiotic beverage brand, and India are also contributing to regional growth through expanding health-conscious consumer bases.
Middle East & Africa and Latin America Digestive Health Products Market Insights
Middle East & Africa and Latin American regions are gradually expanding digestive health product adoption as functional food and dietary supplement retail infrastructure develops and consumer awareness of gut health benefits grows across both regions.
Brazil is set to be a prominent Latin American market fueled by growing dairy and functional food manufacturing capacity and rising consumer demand for gut health-positioned products. The Middle East & Africa region has UAE and Saudi Arabia investing in modern retail infrastructure that is gradually expanding access to digestive health product categories, including probiotic dairy and enzyme supplement offerings.
Market Dynamics
Growth Drivers: Rising gut-health awareness and institutional scientific communication driving market growth
Rising consumer awareness of the gut-systemic health connection, reinforced by government-published scientific communication and corporate evidence-sharing, is among the primary drivers of the digestive health products market. Government bodies like the National Institutes of Health via its Human Microbiome Project, as well as the U.S. Food and Drug Administration through its initiatives, have stressed the significance of gut microbiota in ensuring immunity, metabolic function, and mental wellness, thus boosting consumer confidence in clinically proven products.
Gastrointestinal disorders being more prevalent, higher awareness levels, aging populations, as well as greater willingness to invest in gastro intestinal wellness remain crucial growth drivers of the market. In addition, higher demand for nutritive and functional ingredients in food, movement of the product category from a specialty wellness offering to that of prevention and nutrition, as well as higher prevalence of digestive disorders resulting from lifestyles and lactose intolerance are fueling demand.
Restraints: High product development costs and regulatory complexity limiting market expansion
One of the main barriers to market growth is the high cost associated with clinically validating strain-specific probiotic and enzyme formulations, requiring substantial research investment that can constrain smaller manufacturers' ability to compete against established digestive health brands with deeper scientific validation resources.
Additionally, stringent regulatory requirements governing health claims for probiotics, prebiotics, and digestive enzyme products continue to complicate product development and marketing across different international jurisdictions. The technical complexity of maintaining probiotic strain viability and stability throughout product shelf life further requires substantial formulation and packaging investment for manufacturers seeking to deliver consistent, effective digestive health products.
Opportunities: Expansion of personalized nutrition and next-generation probiotics creating new growth avenues
The digestive health supplements industry is projected to grow significantly, driven by rising consumer demand for concentrated, clinically supported solutions beyond traditional food-based formats, creating substantial opportunities for manufacturers developing next-generation strain-specific probiotic and enzyme supplement products.
There is a considerable growth opportunity in the continued development of personalized digestive health solutions supported by technology integration in health monitoring. The expansion of functional food and dietary supplement manufacturing capacity in emerging markets across Asia Pacific and Latin America is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
- 2025: Inner Brightness launched its Akkermansia Probiotic, a next-generation gut supplement combining pasteurized Akkermansia muciniphila, digestive enzymes, and B vitamins to support digestion, nutrient absorption, and microbiome balance.
- 2025: BASF's Nutrition & Care segment reported strong sales performance, with its Nutrition & Health division contributing significant revenue, reflecting the company's expanding presence in digestive health ingredient supply.
- 2026: Chr. Hansen, now part of Novonesis, expanded its probiotic strain production capacity, strengthening its ability to supply growing global demand for digestive health-focused functional food and supplement ingredients.
- 2026: Danone launched an updated Activia probiotic yogurt product line with enhanced strain diversity, targeting consumers seeking clinically supported gut health benefits through everyday dairy consumption.
Digestive Health Products Market key players are:
- Nestle S.A.
- Danone S.A. (Cie Gervais Danone)
- Procter & Gamble Co.
- The Kraft Heinz Company
- Bayer AG
- Yakult Honsha Co., Ltd.
- Novonesis (Chr. Hansen Holding A/S)
- Pfizer Inc.
- Align Technology, Inc.
- Sanofi S.A.
- The Clorox Company
- Reckitt Benckiser Group plc
- dsm-firmenich (DSM Nutritional Products Ltd.)
- Church & Dwight Co., Inc.
- The Nature's Bounty Co.
- Unilever PLC
- Abbott Laboratories
- GSK plc
- BASF SE
- Inner Brightness
Digestive Health Products Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 60.3 Billion |
| Market Size by 2035 | USD 134.6 Billion |
| CAGR | CAGR of 8.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Dairy Products, Functional Foods & Beverages, Bakery & Cereals, Supplements) • By Ingredient Type (Prebiotics, Probiotics, Food Enzymes, Others) • By Distribution Channel (Supermarkets/Hypermarkets, Online Retail, Hospital Pharmacies) • By Age Group (Adult, Geriatric, Pediatric) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Nestle S.A., Danone S.A. (Cie Gervais Danone), Procter & Gamble Co., The Kraft Heinz Company, Bayer AG, Yakult Honsha Co., Ltd., Novonesis (Chr. Hansen Holding A/S), Pfizer Inc., Align Technology, Inc., Sanofi S.A., The Clorox Company, Reckitt Benckiser Group plc, dsm-firmenich (DSM Nutritional Products Ltd.), Church & Dwight Co., Inc., The Nature's Bounty Co., Unilever PLC, Abbott Laboratories, GSK plc, BASF SE, Inner Brightness. |
Frequently Asked Questions
The Digestive Health Products Market is expected to grow at a CAGR of 8.40% from 2026 to 2035.
The Digestive Health Products Market was valued at USD 60.3 Billion in 2025.
The market is driven by rising consumer awareness of the gut-systemic health connection, reinforced by government-published scientific communication and corporate evidence-sharing.
The Dairy Products segment dominated the Digestive Health Products Market, accounting for approximately 73.80% market share.
The North America region dominated the Digestive Health Products Market in 2025 with more than a 38.50% share, holding USD 23.2 Billion revenue.
