
Digital Radiology Market Report Scope & Overview:
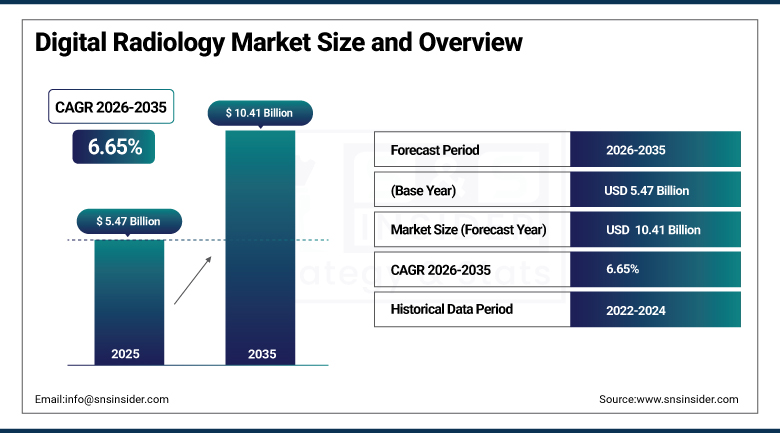
The Digital Radiology Market was valued at USD 5.47 Billion in 2025 and is expected to reach USD 10.41 Billion by 2035, growing at a CAGR of 6.65% from 2026-2035.
Digital radiology constitutes a foundational category within diagnostic imaging, integrating flat-panel detectors, image processing software, and AI-enabled workflow tools that have largely replaced film-based radiography across hospitals and imaging centers. Rising incidence of chronic and orthopedic conditions, expanding dental and cardiovascular imaging volumes, and growing integration of artificial intelligence into radiology workflows continue to broaden the clinical base requiring these systems. Hospitals, diagnostic imaging centers, and an expanding base of specialty clinics rely on digital radiology to deliver faster image acquisition, lower radiation dose, and improved diagnostic accuracy across a wide range of clinical applications. Sustained growth is being shaped by continued advancement in AI-enabled image processing, rising adoption of portable and point-of-care systems, and expanding replacement of legacy analog and computed radiography installations, reinforcing this market's position as a durable, technology-led segment of the wider medical imaging industry.
On July 24, 2025, GE HealthCare announced commercial availability of Definium Pace Select ET, an advanced floor-mounted digital X-ray system designed to deliver high image quality and optimize efficiency in high-throughput clinical environments. The company stated the system brings automation and AI-enabled Helix image processing typically reserved for premium overhead tube suspension systems into the more affordable floor-mounted category.
To Get more information On Digital Radiology Market - Request Free Sample Report
Digital Radiology Market Trends:
-
Growing integration of AI-enabled image processing improving consistency and reducing repeat exposures.
-
Rising adoption of portable and mobile digital radiology systems supporting point-of-care imaging.
-
Expanding replacement of legacy computed radiography installations with direct digital radiography.
-
Increasing manufacturer investment in dose-reduction technology addressing patient safety priorities.
-
Rising demand for cost-effective floor-mounted systems extending advanced imaging to broader facility types.
-
Growing use of digital radiology in dental and orthopedic imaging supporting implant and trauma care.
-
Expanding vendor partnerships with cloud computing providers supporting scalable AI model deployment.
U.S. Digital Radiology Market Overview:
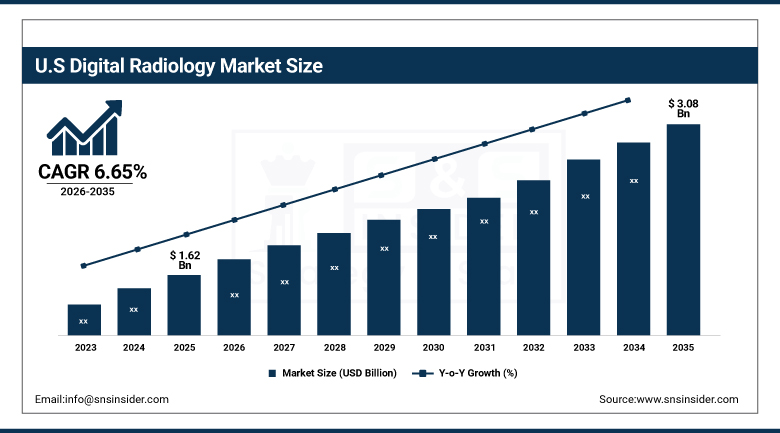
The U.S. Digital Radiology Market was valued at USD 1.62 Billion in 2025 and is expected to reach USD 3.08 Billion by 2035, growing at a CAGR of 6.65% from 2026-2035.
Domestic demand continues to be underpinned by sustained hospital and diagnostic imaging center capital investment alongside rising adoption of AI-enabled and portable digital radiology systems across the country's healthcare infrastructure. Leading manufacturers continue expanding their mobile and floor-mounted system portfolios, including automation features designed to reduce technologist workload and improve consistency, while continued investment in dose-reduction technology keeps strengthening domestic competitive positioning. Growing replacement of aging analog and computed radiography installations further supports domestic market expansion as hospitals and imaging centers work to modernize diagnostic capability across a broad range of clinical settings nationwide.
In November 2025, Canon Medical Systems began sales of Mobirex i9 Smart Edition, a high-end mobile X-ray system featuring enhanced radiographic support functions designed for demanding inpatient and emergency imaging environments. The company stated the launch reflects continued investment in portable imaging technology supporting point-of-care diagnostic workflows.
Digital Radiology Market Segment Analysis:
-
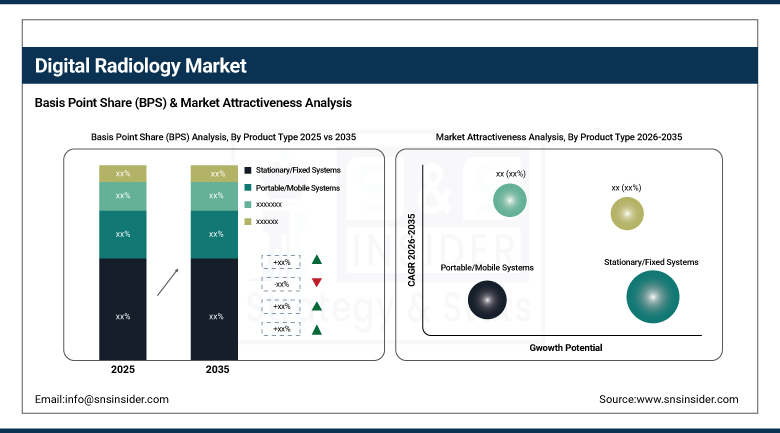
By Product Type, the Stationary/Fixed Systems segment dominated the market with a 54.60% share in 2025, while the Portable/Mobile Systems segment is the fastest growing with a CAGR of 8.40% during 2026-2035.
-
By Technology, the Direct Digital Radiography segment dominated the market with a 58.20% share in 2025, and is also the fastest growing with a CAGR of 8.10% during 2026-2035.
-
By Application, the Dental Imaging segment dominated the market with a 28.60% share in 2025, while the Cardiovascular Imaging segment is the fastest growing with a CAGR of 7.90% during 2026-2035.
-
By End User, the Hospitals segment dominated the market with a 48.60% share in 2025, while the Diagnostic Imaging Centers segment is the fastest growing with a CAGR of 7.60% during 2026-2035.
By Product Type, Stationary/Fixed Systems Dominates the Market and Portable/Mobile Systems Grows Fastest
Stationary/Fixed Systems dominated the market in 2025, a position built on their superior image quality, higher patient throughput capacity, and suitability for the full range of radiographic examinations performed within dedicated hospital and imaging center radiology departments. Facility operators favour this product category precisely because it delivers the consistent, high-resolution imaging performance required across general radiography, orthopedic, and chest imaging applications, a combination that continues to make fixed installations the default specification across established radiology departments worldwide, even as portable systems continue to expand around it for bedside and point-of-care applications. Fixed systems also benefit from lower per-exposure operating costs at high patient volumes, reinforcing their continued dominance across large hospital networks and dedicated imaging centers that process substantial daily examination volumes.
Portable/Mobile Systems are projected to be the fastest-growing product category over the forecast period. Rising demand for bedside imaging across intensive care units, emergency departments, and surgical suites continues to expand the addressable application base for this product category as clinicians increasingly require diagnostic imaging capability without transporting critically ill or immobile patients. As manufacturers continue improving image quality, battery life, and automation features on mobile platforms, portable systems continue closing the gap with fixed installations in overall market demand, particularly across facilities prioritizing flexible deployment and reduced patient transport risk.
By Technology, Direct Digital Radiography Dominates the Market and Grows Fastest
Direct Digital Radiography dominated the market in 2025, reflecting its rapid image acquisition, immediate availability of images for diagnosis, and superior ability to manipulate images for enhanced visualization relative to computed radiography's cassette-based, two-step workflow. Radiology departments favour this technology precisely because it delivers dramatically faster turnaround and lower dose exposure than legacy computed radiography systems, a combination that continues to make direct digital radiography the default specification across new and replacement installations worldwide.
Direct Digital Radiography is also projected to be the fastest-growing technology category over the forecast period, with its market share expected to continue climbing as computed radiography installations reach end of life and are replaced. Continued advancement in flat-panel detector cost and performance continues to accelerate this transition, as facilities that previously found direct digital radiography systems cost-prohibitive increasingly find replacement economics favourable. As this technology continues expanding its addressable market at the expense of computed radiography, direct digital radiography is positioned to sustain its leadership across both current market share and forward growth.
By Application, Dental Imaging Dominates the Market and Cardiovascular Imaging Grows Fastest
Dental Imaging applications dominated the market in 2025, reflecting the exceptionally large scale at which digital radiography is used within dental radiology practice, spanning routine bitewing and periapical examinations through panoramic and cone-beam imaging supporting implant planning. This high-volume, high-frequency examination pattern continues to sustain dental imaging as the largest application category by a clear margin, as dental practices worldwide continue transitioning from film-based to fully digital radiographic workflows supporting both diagnostic and treatment-planning needs across general and specialty dental practice.
Cardiovascular Imaging applications are projected to expand fastest over the forecast period. Rising global incidence of cardiovascular disease continues to drive demand for digital radiography supporting cardiac catheterization, vascular intervention, and chest imaging applications requiring high temporal resolution and low-dose fluoroscopic capability. As interventional cardiology procedure volumes continue climbing worldwide, cardiovascular imaging applications continue closing the gap with dental imaging in overall market demand, supported by continued advancement in dose-efficient flat-panel detector technology suited to cardiac catheterization laboratories.
By End User, Hospitals Dominates the Market and Diagnostic Imaging Centers Grows Fastest
Hospitals dominated the market in 2025. The scale and diversity of imaging services required to support inpatient care, emergency medicine, and surgical services continues to require the broadest and most comprehensive digital radiology infrastructure of any single facility type, spanning general radiography through specialized cardiovascular and orthopedic imaging suites. This breadth of clinical capability, combined with the sheer examination volume that major hospital networks process daily, continues to sustain hospitals as the clear leading end-user category across the broader market.
Diagnostic Imaging Centers are expected to be the fastest-growing end-user category over the forecast period. A steady shift of routine and specialized imaging examinations toward outpatient settings continues pulling demand away from hospital-based radiology departments, as both providers and payers increasingly favour the lower cost structure independent and hospital-affiliated imaging centers typically offer relative to full hospital-based examination. As standalone and multi-site imaging center networks continue expanding their digital radiology capability, this end-user category continues to close the gap with hospitals in overall market demand.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 |
|
North America |
United States |
78.34% |
|
Asia Pacific |
China |
41.27% |
|
Europe |
Germany |
32.85% |
|
Latin America |
Brazil |
44.19% |
|
Middle East & Africa |
United Arab Emirates |
28.73% |
North America Digital Radiology Market Insights
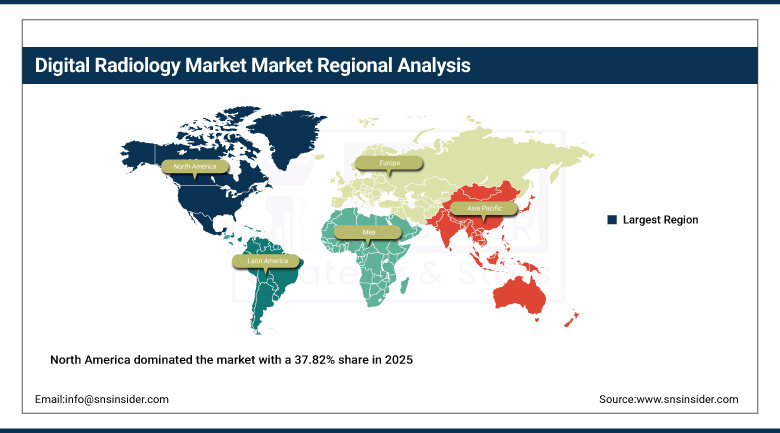
North America dominated the market with a 37.82% share in 2025. The region's advanced healthcare infrastructure, dense concentration of leading digital radiology manufacturers, and sustained hospital capital investment continue to anchor this leadership position across both hospital and diagnostic imaging center settings. The United States shapes regional demand through its concentration of leading equipment developers and its role as a proving ground for AI-enabled radiology workflow innovation, with manufacturers routinely launching next-generation systems in domestic facilities before broader international rollout.
Canada contributes additional regional demand through its participation in North American healthcare capital equipment procurement and provincial imaging modernization programs. Continued domestic investment in AI-enabled and portable digital radiology technology is expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets building out diagnostic imaging infrastructure from a considerably smaller existing base.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Digital Radiology Market Insights
Asia Pacific is projected to be the fastest-growing region, registering a CAGR of 7.90% during 2026-2035, supported by rising healthcare spending, expanding hospital infrastructure, and growing replacement of legacy analog radiography across the region's substantial and rapidly ageing population base. China continues to anchor regional demand as hospital networks and dental practices expand digital radiology capability across both established urban medical centers and rapidly developing regional healthcare facilities, supported by sustained government investment in modernising the country's broader healthcare infrastructure.
India's expanding hospital infrastructure and rising dental care access continue adding meaningful regional growth as domestic providers extend digital radiology capability into previously underserved areas. Japan and South Korea contribute further depth through established, technically advanced healthcare systems, with regional manufacturers notably active in cost-competitive system development, positioning the wider region to sustain the fastest percentage growth of any global market through 2035.
Europe Digital Radiology Market Insights
Europe holds a meaningful share of the global market, underpinned by a dense concentration of established digital radiology manufacturers and continued advancement in AI-enabled and dose-efficient imaging technology developed for hospital and dental applications. Germany's substantial hospital and dental practice base anchors regional demand, supported by a well-developed reimbursement framework that continues to favour early adoption of next-generation digital radiology technology across both public and private healthcare providers operating throughout the country and neighbouring markets.
The United Kingdom, France, and other major European markets contribute consistent demand as national health systems keep extending advanced digital radiology technology into routine clinical practice. Continued price sensitivity across parts of the region has prompted competitively priced vendors to gain share, reflecting the region's role as both an established manufacturing base and a mature, price-conscious end market for digital radiology technology.
MEA & Latin America Digital Radiology Market Insights
The Middle East & Africa market is supported by growing healthcare infrastructure spending across the United Arab Emirates and Saudi Arabia, where rising hospital and dental clinic investment continues to lift demand for modern digital radiology equipment across both public hospital networks and an expanding private healthcare sector. Regional governments continue channeling substantial investment into expanding diagnostic imaging access, including dedicated radiology centres designed to reduce reliance on overseas treatment for complex cases.
Latin America's market is anchored by Brazil, where a sizeable domestic healthcare sector sustains steady equipment demand across both public and private hospital systems. Mexico contributes further incremental growth as healthcare access continues to widen across the broader region, though adoption of the most advanced AI-enabled digital radiology platforms across Latin America as a whole still lags meaningfully behind more established markets in North America and Europe.
Market Dynamics:
Growth Drivers: Chronic Disease Burden and AI-Enabled Workflow Adoption
Rising incidence of chronic and orthopedic conditions stands as a primary growth driver, reinforced by expanding healthcare spending, an ageing population, and growing rates of dental and cardiovascular disease that continue widening the patient pool requiring digital radiology examinations worldwide. This demographic shift translates directly into a larger base of patients requiring regular diagnostic imaging across both developed and emerging healthcare systems alike, sustaining recurring capital investment in imaging infrastructure across hospital networks and dental practices globally.
Growing adoption of artificial intelligence in radiology workflows represents a second major driver, supported by hospital capital investment and rising clinician demand for tools improving image consistency and reducing repeat exposures. Increasing replacement of legacy analog and computed radiography installations, paired with rising demand for portable systems capable of supporting point-of-care imaging, continues to reinforce sustained market expansion across both established Western healthcare systems and rapidly developing markets.
Restraints: High Equipment Costs and Reimbursement Pressure
The high equipment cost is still a real constraint to growth in the market since the most sophisticated digital radiography devices, with integrated artificial intelligence processing capabilities and expensive detectors, will still have very significant capital costs that are hard for smaller facilities and cost-conscious markets to justify due to the financial constraints they operate under. The problem of high capital costs is more likely to affect smaller facilities like those located in developing markets since the cost involved in purchasing such sophisticated machines will be greater than their budget allocation.
Reimbursement pressure presents a further restraint, as ongoing policy debates around diagnostic imaging payment rates continue to create uncertainty around long-term revenue predictability for providers operating on tighter margins. This pressure particularly affects independent diagnostic imaging centers operating in markets with less favourable payer mix, where reimbursement rate reductions can meaningfully exceed what many smaller operators can reasonably absorb without impacting service capacity or continued capital reinvestment. Currency fluctuation and cross-border supply chain complexity add a further layer of cost unpredictability for manufacturers serving multiple international markets simultaneously, particularly given the concentration of component sourcing among a handful of specialty detector and electronics suppliers.
Opportunities: AI Workflow Integration and Cost-Competitive System Development
Continued integration of artificial intelligence into radiology workflows offers a substantial opportunity, as manufacturers developing tools improving diagnostic accuracy and reducing technologist workload stand to capture meaningful new demand from facilities seeking more consistent clinical outcomes. Hospitals increasingly view these platforms not as a novelty feature but as a genuine operational necessity capable of reducing repeat exposures while improving overall diagnostic throughput for facilities managing high patient volumes.
The continued development of cost-competitive, floor-mounted digital radiology systems presents a further avenue for growth, as manufacturers work to extend advanced imaging capability to facilities that previously found premium overhead tube suspension systems cost-prohibitive. This innovation pathway continues to open new addressable demand across community hospitals and outpatient imaging centers while giving manufacturers a genuine differentiator relative to conventional, premium-only product portfolios.
Recent Developments:
-
2026, Carestream Healthcare International launched the CARESTREAM STARVIEW Digital Radiography System, a floor-mounted digital radiography solution designed for routine X-ray imaging. The system supports digital image acquisition, examination management, image review, and flexible connected or standalone workflows.
-
2026, Teledyne Technologies agreed to acquire Varex Imaging for approximately USD 1.1 billion. Varex develops X-ray sources, digital X-ray detectors, photon-counting detectors, and imaging software used across medical diagnostic imaging and other applications.
-
2026, Ekoscan Integrity Group agreed to acquire Carestream’s U.S.-based NDT Digital business, including its computed radiography, digital radiography detectors, and imaging software portfolio. The transaction expands Ekoscan’s digital inspection capabilities across aerospace, defense, energy, and industrial applications.
-
2026, Sectra completed its acquisition of Oxipit, adding autonomous AI-based radiology capabilities to its medical imaging IT portfolio. The acquisition includes ChestLink, an AI solution designed to autonomously identify and clear high-confidence normal chest X-rays from radiologists’ worklists.
Digital Radiology Market Key Players:
-
Siemens Healthineers AG
-
GE HealthCare Technologies Inc.
-
Koninklijke Philips N.V.
-
Canon Medical Systems Corporation
-
Fujifilm Holdings Corporation
-
Carestream Health, Inc.
-
Agfa-Gevaert Group
-
Shimadzu Corporation
-
Hologic, Inc.
-
Konica Minolta, Inc.
-
Samsung Electronics Co., Ltd.
-
Hitachi, Ltd.
-
Mindray Medical International Limited
-
DRGEM Corporation
-
Villa Sistemi Medicali S.p.A.
-
Swissray International, Inc.
-
iCAD, Inc.
-
Del Medical Imaging Corporation
-
Allengers Medical Systems Limited
-
OXOS Medical, Inc.
Digital Radiology Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.47 Billion |
| Market Size by 2035 | USD 10.41 Billion |
| CAGR | CAGR of 6.65% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Stationary/Fixed Systems, Portable/Mobile Systems, and Retrofit Systems) • By Technology (Direct Digital Radiography and Computed Radiography) • By Application (Chest Imaging, Dental Imaging, Orthopedic Imaging, Cardiovascular Imaging, Digital Mammography, and Others) • By End User (Hospitals, Diagnostic Imaging Centers, Specialty Clinics, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Siemens Healthineers AG, GE HealthCare Technologies Inc., Koninklijke Philips N.V., Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Carestream Health, Inc., Agfa-Gevaert Group, Shimadzu Corporation, Hologic, Inc., Konica Minolta, Inc., Samsung Electronics Co., Ltd., Hitachi, Ltd., Mindray Medical International Limited, DRGEM Corporation, Villa Sistemi Medicali S.p.A., Swissray International, Inc., iCAD, Inc., Del Medical Imaging Corporation, Allengers Medical Systems Limited, OXOS Medical, Inc. |
Frequently Asked Questions
Key players include Siemens Healthineers, GE HealthCare, Philips, Canon Medical Systems, Fujifilm, Carestream Health, Agfa-Gevaert, Shimadzu, Hologic, and Konica Minolta, among others.
Continued integration of artificial intelligence into radiology workflows and the continued development of cost-competitive, floor-mounted digital radiology systems represent the two most significant opportunities shaping the market's next phase of growth.
By Technology, Direct Digital Radiography dominated the market with a 58.20% share in 2025, reflecting its rapid image acquisition and superior workflow relative to computed radiography.
Growth is primarily driven by rising incidence of chronic and orthopedic conditions, combined with growing adoption of artificial intelligence in radiology workflows.
North America dominated the market with a 37.82% share in 2025, supported by the region's advanced healthcare infrastructure and dense concentration of leading manufacturers.
