
Home Healthcare Devices Market Report Scope & Overview:
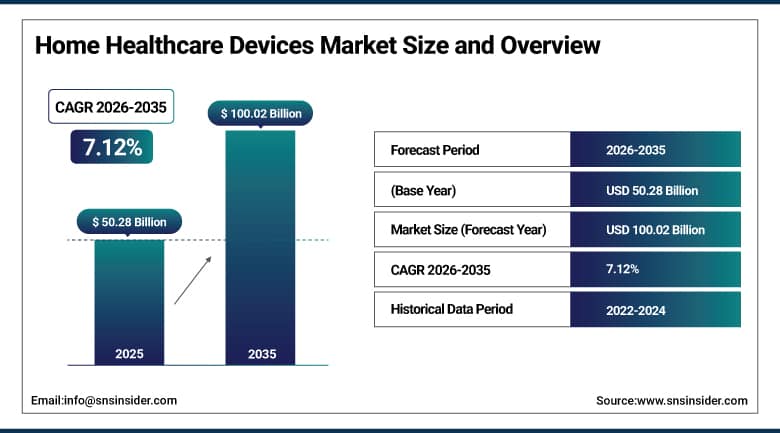
The Home Healthcare Devices Market size stood at USD 50.28 billion in 2025 and is forecasted to be worth USD 53.86 billion in 2026. Further, it is expected to grow up to USD 100.02 billion by 2035, posting a CAGR of 7.12% during 2026 and 2035. The market encompasses the sale of monitoring devices, therapeutic devices, and mobility aids that people use when they are not in hospitals, such as blood pressure monitors, glucose monitors, oxygen concentrators, and powered wheelchairs. A growing number of elderly people, increasing prevalence of chronic conditions, and attempts to reduce costs by moving care away from expensive facilities are driving the demand for patient-operable devices.
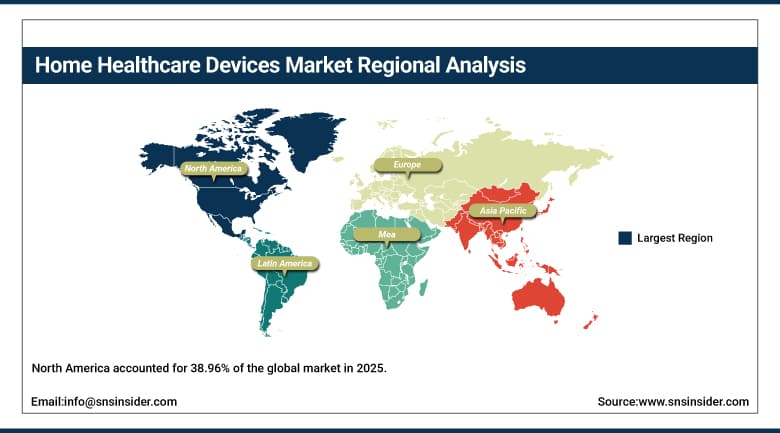
North America was the largest regional market in 2025 with a market share of 38.96%, due to the presence of good reimbursement channels, high prevalence of chronic conditions, and early adoption of connected devices. The European region is next, driven by robust public spending on home healthcare devices. However, Asia Pacific will see the fastest growth during the forecast period, since the region is home to Japan, China, India, and South Korea, all countries experiencing rapid population aging, expanding insurance coverage, and manufacturing of low-cost monitoring and respiratory devices.
To Get More Information On Home Healthcare Devices Market - Request Free Sample Report
Key Report Takeaways
- By product type, monitoring and diagnostic devices held a 44.37% share in 2025, while mobility assist and patient support devices are the fastest growing.
- By application, diabetes care accounted for a 35.18% share in 2025, while neuro-rehabilitation is the fastest growing.
- By sales channel, retail medical stores represented a 39.12% share in 2025, while online retailers are the fastest growing.
- By end user, elderly and assisted-living users commanded a 34.04% share in 2025, while chronic-disease home care is the fastest growing.
- By region, North America led with a 38.96% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
Continuous monitoring is replacing spot checks. Wearable glucose sensors, patch-based vital sign monitors, and cuffless blood pressure devices are moving from clinical trials into consumer channels, and care teams increasingly receive streaming data rather than occasional readings recorded in a patient diary. This shift supports earlier intervention and fewer avoidable admissions.
Over-the-counter access is widening the buyer base. Regulators have cleared several sensors that consumers can buy without a prescription, and retailers are placing diagnostic and monitoring products in online stores and pharmacy aisles. Patients who once relied on clinics for testing now manage routine checks themselves, which expands demand beyond people with a formal diagnosis.
Manufacturers are pairing hardware with software and services. Subscription apps, remote coaching, and clinician dashboards are bundled with devices to improve adherence and create recurring revenue.
Hospital-at-home programs are formalizing the home as a site of acute care. Health systems are sending monitoring kits, infusion equipment, and oxygen supplies to patients' residences, which creates larger and more predictable orders for suppliers.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Aging Population and Chronic Disease Burden |
+3.18% |
Global, strongest in North America, Europe, and Japan |
Short term (2 years or less) |
|
Shift to Home-Based Care and Hospital-at-Home Policy |
+2.46% |
North America and Europe |
Medium term (2 to 4 years) |
|
Remote Monitoring and Connected Device Advances |
+2.12% |
North America, Europe, and Asia Pacific |
Medium term (2 to 4 years) |
|
Regulatory Clearances for Over-the-Counter and Consumer Devices |
+1.34% |
United States and Europe |
Medium term (2 to 4 years) |
|
Strategic Investment and Product Innovation |
+0.86% |
Global |
Long term (4 years or more) |
Aging Population and Chronic Disease Burden
The number of people aged 60 and older is increasing quickly, and the World Health Organization expects one in six people worldwide to be in this age group by 2030. Older adults live with diabetes, hypertension, heart failure, and respiratory disease, all of which require regular measurement and therapy at home. Families and health plans prefer devices that reduce clinic visits, and caregivers rely on mobility and bathing aids to keep older relatives independent. This demographic pressure creates steady, repeat demand for monitors, test strips, oxygen equipment, and mobility products across every region.
Shift to Home-Based Care and Hospital-at-Home Policy
Health systems are moving care out of expensive facilities and into residences, and policy has followed. In February 2026 the United States extended the Medicare hospital-at-home waiver for five years, which gives hospitals and suppliers the stability needed to invest in monitoring kits, infusion equipment, and logistics. European and Asian health authorities are testing similar models for early discharge and chronic disease management. Suppliers that can deliver, install, and support equipment at scale benefit directly from this shift in the site of care.
Remote Monitoring and Connected Device Advances
Advances in sensors, batteries, wireless communication, and analysis are increasing the accuracy and ease of use of home devices. The continuous glucose monitor, the blood pressure cuff that transmits its readings wirelessly, the intelligent inhaler, and the wearable sensor patch are some examples of devices transmitting data to doctors on their own, which means that action can be taken by care providers before the situation deteriorates further. Increased smartphone ownership and widespread availability of broadband reduce the cost of using such technology, and patients are also more likely to adhere to treatment when they see their results.
Regulatory Clearances for Over-the-Counter and Consumer Devices
Regulators are creating pathways for devices that consumers can buy without a prescription. In January 2026 the U.S. Food and Drug Administration updated its general wellness guidance, easing the route to market for non-invasive wearables that make no disease claims. Cleared over-the-counter glucose sensors and cuffless blood pressure monitors now reach consumers directly through pharmacies and online stores. Faster clearances encourage manufacturers to launch new products and widen the potential buyer base. These steps lower barriers for new entrants and encourage rapid product iteration.
Strategic Investment and Product Innovation
Large medical technology companies, specialist developers, and investors are putting capital into home-focused products. Acquisitions of at-home testing and therapy providers give respiratory and sleep suppliers new channels, while public offerings and venture rounds finance wearable and patch-based monitoring start-ups. Manufacturers also invest in smaller, quieter, and longer-lasting devices designed for non-clinical users. This steady flow of capital and design effort improves product quality and keeps competitive pressure high. Competition among well-funded firms also drives lower prices and better usability, which benefits patients and health plans.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Reimbursement Pressure and Competitive Bidding |
-0.96% |
United States and Europe |
Medium term (2 to 4 years) |
|
Regulatory Uncertainty and Short-Term Policy Extensions |
-0.74% |
North America and Europe |
Medium term (2 to 4 years) |
|
Wellness-Versus-Medical Claims Ambiguity |
-0.62% |
United States and Europe |
Long term (4 years or more) |
|
Out-of-Pocket Cost and Digital Access Gaps |
-0.52% |
Latin America, Middle East & Africa, and rural areas |
Long term (4 years or more) |
Reimbursement Pressure and Competitive Bidding
Payment rates for home equipment and services are under review in several health systems. A Medicare rule effective in January 2026 restarted the competitive bidding program for durable medical equipment and moved certain glucose monitors and insulin pumps to bundled monthly rental payments. Suppliers face tighter margins, more administrative work, and pressure to cut prices, which can slow investment in new products and limit service quality for patients who depend on equipment in their homes. Smaller suppliers may exit unprofitable categories altogether.
Regulatory Uncertainty and Short-Term Policy Extensions
Home care programs depend on waivers and telehealth flexibilities that have often been extended for only short periods. Before the five-year hospital-at-home extension was passed, operators had to plan under repeated deadlines, and at least one program reportedly closed because of that uncertainty. Suppliers hesitate to commit to large inventories and service networks when payment rules may change, and privacy and cybersecurity obligations for connected devices add further compliance work. Patients may therefore face delays in receiving equipment or switching to newer technologies.
Wellness-Versus-Medical Claims Ambiguity
The boundary between consumer wellness products and regulated medical devices is becoming harder to define. Updated guidance in January 2026 lets some wearables measure blood pressure, oxygen saturation, or glucose-related signals without being cleared, as long as they avoid disease claims. Clinicians may question the accuracy of such products, patients may rely on them wrongly, and cleared device makers must compete with lower-cost alternatives that face lighter evidence requirements. Clearer rules on claims and evidence would help buyers distinguish validated products from general wellness tools.
Out-of-Pocket Cost and Digital Access Gaps
In many emerging markets, patients pay for home devices themselves, and insurance coverage for monitors and respiratory equipment is limited. Low incomes, weak broadband, and limited digital skills restrict the use of connected products, particularly among older adults in rural areas. Even in advanced markets, consumables such as sensors and test strips create ongoing costs. These barriers slow adoption and keep many patients dependent on clinic-based monitoring. Manufacturers must therefore offer simpler, lower-priced models and training support to reach these groups effectively.
Home Healthcare Devices Market Segment Analysis
By Application, Diabetes Care Dominates Home Healthcare Devices Market; Neuro-Rehabilitation to Register Fastest Growth.
Diabetes Care leads in its share due to the number of patients who need to measure their glucose levels every day at home, and deliver insulin. The continuous glucose monitors, metering devices, insulin pens, and infusion pumps have well-documented clinical guidance and are covered for reimbursement. Obese patients with lifestyle diseases are becoming more and more every year. 35.18% was the share of diabetes care in 2025. Innovative sensors that make less finger pricking possible, and which can be connected to smartphones, attract many more patients, including those with type 2 diabetes.
There are millions of stroke cases and patients with movement disorders in the US, who have a high chance of developing complications. Early and effective rehabilitation after the stroke improves the prognosis and helps prevent any serious complications. Neuro-rehabilitation has the highest growth rate because the therapy continues even after the patient leaves the hospital. Wearable robotic exoskeletons, electrical stimulation units, and exercise machines with sensory feedback are used to supervise the rehabilitation process at home. Clinical evidence gives the opportunity to see a CAGR of 9.47% during 2026-2035.
By Product Type, Monitoring and Diagnostic Devices Dominate Home Healthcare Devices Market; Mobility Assist and Patient Support Devices to Register Fastest Growth.
Monitoring and diagnostic devices lead because chronic disease management starts with measurement. Blood glucose meters, continuous glucose monitors, blood pressure cuffs, pulse oximeters, and thermometers are bought repeatedly, and consumables generate recurring sales. Clinicians and payers support home testing as a way to detect problems early and reduce visits. Monitoring and diagnostic devices accounted for 44.37% of the market in 2025. Home use is also supported by simple designs, clear displays, and apps that store readings for later review.
Mobility assist and patient support devices are growing fastest as aging populations seek to remain independent at home. Walkers, powered wheelchairs, lift systems, hospital-style beds, and bathroom safety products are in demand from families and assisted-living operators. Product design is improving, and online sales make purchasing easier. This segment is projected to advance at a CAGR of 9.12% from 2026 to 2035. Continued innovation in lightweight materials and battery-powered lift systems should keep widening the range of available products.
By Sales Channel, Retail Medical Stores Dominate Home Healthcare Devices Market; Online Retailers to Register Fastest Growth.
The retail medical stores have an edge over their competitors since patients prefer professional consultations, customization, and the option of seeing equipment before purchasing. The pharmacies and specialized stores have many varieties of monitors, supports, and mobility devices available for purchase. Additionally, they are certified vendors for most insurance schemes. They enjoy referrals from doctors to bring in more customers. In 2025, the retail medical stores had a market share of 39.12%. The manufacturers also provide training and demonstrations as well as other programs for their pharmacists, technicians, and store personnel in various regions.
The online retailers are witnessing the fastest growth in the industry owing to consumer trust in buying health care equipment through the web platform. Low prices, doorstep delivery, refills, reviews and over-the-counter clearance of sensors ensure the purchase of medical products on this platform. The manufacturers also have their own direct-to-consumer websites. It is expected that sales through online stores will grow at a CAGR of 11.86% during 2026-2035. Competitive pricing among the platforms makes price-conscious consumers switch brands frequently.
By End User, Elderly and Assisted-Living Users Dominate Home Healthcare Devices Market; Chronic-Disease Home Care to Register Fastest Growth.
The elderly and the assisted-living category come first since elderly people need more monitoring, breathing assistance, and mobility tools than others. The assisted-living facilities make purchases in large numbers and require products that are easy to use, robust, and simple to clean. The family caregivers also make frequent purchases and mostly buy safety and mobility items. This segment accounted for 34.04% of the market in 2025. Hospitals providing discharge services to the elderly people recommend the same standard set of products that include monitors, mobility tools, and safety items.
Home health chronic disease management is the fastest-growing segment since people who are suffering from heart failure, COPD, kidney diseases, and diabetes are being enrolled into the remote care programs by payers. It is beneficial for payers to keep them out of hospitals, and with the help of connected devices, care teams can get the necessary information. It will grow with the CAGR of 8.73% during 2026-2035. Companies are providing clinicians with dashboards and alerts to analyze multiple patient readings quickly.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.37% |
|
Europe |
Germany |
27.31% |
|
Asia Pacific |
China |
38.94% |
|
Middle East & Africa |
Saudi Arabia |
31.76% |
|
Latin America |
Brazil |
45.28% |
North America Home Healthcare Devices Market
North America accounted for 38.96% of the global market in 2025. The region has a large population of older adults, a high prevalence of diabetes and cardiovascular disease, and established distribution networks that connect manufacturers, pharmacies, and suppliers. Health plans and Medicare cover many categories of home equipment, and consumers are quick to adopt connected products. Strong clinician awareness, widespread pharmacy networks, and active patient advocacy groups reinforce steady and growing demand for home testing and therapy products across the region.
The United States contributed USD 16.53 Billion in 2025 and is projected to grow at a CAGR of 6.58% from 2026 to 2035. Hospital-at-home programs, over-the-counter sensor clearances, and strong online retail activity support demand, while competitive bidding and payment reform shape supplier strategies. Canada adds growth through provincial home care programs. Regional insurers and employers also offer remote monitoring programs for members with diabetes and hypertension, which helps normalize device use at home. Pharmacy chains promote bundled starter kits for new patients.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Home Healthcare Devices Market
Europe holds the second-largest regional position, supported by public health systems that fund home care and by a population that is among the oldest in the world. Germany, France, the United Kingdom, and the Nordic countries lead adoption of remote monitoring, home dialysis, and respiratory therapy. Procurement is often managed at national or regional level. Aging populations in Italy and Spain add further pressure on health budgets, which encourages governments to favor community-based care models over long hospital stays and nursing home placements.
Regulation under the Medical Device Regulation raises the cost of bringing products to market but also builds clinician trust. European suppliers are active in mobility aids, blood pressure monitoring, and sleep therapy, and cross-border telehealth projects are helping standardize remote monitoring. Pressure on public budgets encourages home-based alternatives to hospital stays. Manufacturers also face a patchwork of reimbursement rules across countries, so launches often proceed one market at a time and rely on local distributors for training and after-sales support services.
Asia Pacific Home Healthcare Devices Market
Asia Pacific is the fastest-growing region, expected to register a CAGR of 9.84% from 2026 to 2035. Japan and South Korea already have some of the oldest populations in the world, while China and India are seeing rapid growth in diabetes and hypertension. Rising incomes and expanding insurance coverage make home devices more affordable for middle-class households. Government campaigns encouraging regular health checks, together with growing awareness of lifestyle disease, are also bringing new first-time buyers into the home device market each year.
Local manufacturers supply low-cost blood pressure monitors, glucose meters, and oxygen concentrators, and international companies are building regional distribution and service networks. Online platforms in China and India give buyers convenient access to a wide range of products. Government programs for elderly care and primary health services also support long-term demand. Telehealth platforms and health marketplaces connect patients with clinicians and suppliers, which makes it easier for people in smaller cities to obtain prescribed equipment, receive training, and replace consumables on time.
Latin America Home Healthcare Devices Market
The region has Brazil as its leader due to a big population size, growth in private insurance and development of pharmacies that enable usage of glucose meters, blood pressure and respiratory monitoring equipment. Demand also comes from Mexico, Argentina, and Colombia, where there are more people who can afford to be responsible for managing their conditions at home. Chain pharmacies in Brazil and Mexico offer health corners where clients can measure their blood pressure and glucose levels, increasing awareness about home testing and attracting new customers.
Factors such as currency fluctuations, expensive import, and limited insurance coverage impede growth of the market, especially in low-income groups. Health programs related to diabetes and hypertension management start to distribute home monitoring equipment; international companies collaborate with regional distributors of the products. Development of e-commerce will also positively impact availability of affordable equipment. Chile and Uruguay have advanced public health systems and higher rate of Internet usage, therefore they are early adopters of connected devices, whereas Argentina and Colombia are targeting the problem of chronic diseases management.
Middle East & Africa Home Healthcare Devices Market
Middle East & Africa is the smallest region, though Gulf countries are investing in private hospitals, long-term care, and digital health. Saudi Arabia and the United Arab Emirates have high rates of diabetes and national strategies that promote home care and preventive services, which supports demand for glucose monitoring and respiratory devices. Rapid growth in private hospital groups and medical tourism also encourages investment in home follow-up care, including remote monitoring kits for international patients returning to their home countries afterward.
In Africa, limited insurance coverage and weak distribution networks restrict adoption, though mobile health projects and donor-funded programs are introducing low-cost monitors. South Africa has the most developed private market. Over time, urbanization and a growing middle class should widen the customer base, although affordability remains a barrier. Governments in the Gulf are also launching national programs for diabetes screening and elderly care, and these initiatives create tender opportunities for suppliers of glucose meters, blood pressure monitors, and respiratory equipment alike.
Competitive Landscape
The market is fragmented. Diversified medical technology companies, specialist device makers, respiratory and sleep suppliers, and consumer electronics brands all compete, and no single company controls a large share of revenue. Competition depends on product accuracy, ease of use, reimbursement coverage, and distribution reach. Buyers can choose among many brands, and private-label products from retailers keep pressure on pricing.
Vendors pursue acquisitions, product launches, and partnerships. Respiratory and sleep suppliers buy testing and therapy providers to build home care platforms, glucose monitoring companies add new wearable sensors, and start-ups raise capital for cuffless and patch-based monitoring. Alliances with pharmacies, payers, and telehealth providers help manufacturers reach patients and prove clinical value.
Home Healthcare Devices Market Industry Leaders
1. Koninklijke Philips: Provider of home monitoring, sleep therapy, and respiratory devices.
2. Abbott Laboratories: Maker of FreeStyle Libre continuous glucose monitoring and other home diagnostics.
3. Medtronic: Developer of diabetes management and other home-use medical technology.
4. OMRON Healthcare: Supplier of blood pressure monitors, nebulizers, and other home health devices.
5. ResMed: Provider of sleep apnea and respiratory care devices and related digital services.
Companies Covered in this Report
- Koninklijke Philips
- Abbott Laboratories
- Medtronic
- OMRON Healthcare
- ResMed
- Dexcom
- Baxter International
- Becton, Dickinson and Company
- GE HealthCare
- Medline Industries
- Fresenius Medical Care
- A&D Company
- Inogen
- Insulet
- F. Hoffmann-La Roche
- Drive DeVilbiss Healthcare
Recent Industry Developments
- April 2025: Dexcom received FDA clearance for the Dexcom G7 15 Day continuous glucose monitoring system for adults, extending sensor wear time.
- May 2025: ResMed acquired VirtuOx, a provider of at-home sleep, respiratory, and cardiac testing services.
- July 2025: Aktiia received FDA clearance for the Aktiia G0, described as the first over-the-counter cuffless blood pressure monitor.
- September 2025: Apple received FDA clearance for hypertension notifications on the Apple Watch.
- October 2025: Simergent received FDA 510(k) clearance for the Archimedes automated peritoneal dialysis system for clinical and home use.
- November 2025: Abbott agreed to acquire Exact Sciences, the maker of the at-home Cologuard colorectal cancer screening test.
- January 2026: The U.S. Food and Drug Administration updated its general wellness and clinical decision support guidance, easing the path for non-invasive consumer wearables.
- March 2026: MiniMed, the diabetes business separated by Medtronic, priced its initial public offering.
Scope and Research Methodology
This report defines the Home Healthcare Devices Market as the commercial value of monitoring, diagnostic, therapeutic, and mobility assist devices designed for use by patients or caregivers outside clinical facilities. It covers products sold through retail stores, online channels, pharmacies, and institutional suppliers. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are stated in USD. Segmentation covers product type, application, sales channel, end user, and region. Home health services, telehealth software sold alone, and hospital-grade capital equipment are excluded from the scope. Consumables such as test strips and sensors sold for use with covered devices are included in the market value.
The research program combines secondary and primary work. Secondary research draws on company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with executives, product and business heads, distributors, and end-user stakeholders across the value chain. These conversations validate assumptions, adoption rates, and pricing, and they test how demand is expected to change by product and region. Interviews are structured around a consistent discussion guide so that responses can be compared across regions and stakeholder groups, and responses are anonymized to encourage candid views.
Market engineering follows a bottom-up build from device shipments, consumable volumes, and supplier revenue, cross-checked top-down against population, disease prevalence, and health spending data. Estimates are triangulated across these routes until the results converge within an acceptable range. Forecasts incorporate demographics, regulation, reimbursement, technology change, and macroeconomic conditions. Sensitivity checks test pricing and adoption assumptions, and senior analysts review every estimate and narrative section. Where information is limited, assumptions are documented and tested through scenario analysis. Results are then cross-checked against expert feedback before they are finalized for publication by senior analysts.
Home Healthcare Devices Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 50.28 Billion |
| Market Size by 2035 | USD 100.02 Billion |
| CAGR | CAGR of 7.12% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Monitoring and Diagnostic Devices, Therapeutic Devices, and Mobility Assist and Patient Support Devices) • By Application (Diabetes Care, Cardiovascular Care, Respiratory Care, Neuro-Rehabilitation, and Others) • By Sales Channel (Retail Medical Stores, Online Retailers, Hospital and Pharmacy Channels, and Others) • By End User (Elderly and Assisted-Living, Chronic-Disease Home Care, Post-Acute Care, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Koninklijke Philips, Abbott Laboratories, Medtronic, OMRON Healthcare, ResMed, Dexcom, Baxter International, Becton, Dickinson and Company, GE HealthCare, Medline Industries, Fresenius Medical Care, A&D Company, Inogen, Insulet, F. Hoffmann-La Roche, Drive DeVilbiss Healthcare |

Frequently Asked Questions
The market was valued at USD 50.28 Billion in 2025 and is estimated at USD 53.86 Billion in 2026. It is projected to reach USD 100.02 Billion by 2035.
The market is projected to expand at a CAGR of 7.12% from 2026 to 2035.
North America led with a 38.96% share in 2025. Asia Pacific is the fastest-growing region, with a CAGR of 9.84% from 2026 to 2035.
Monitoring and diagnostic devices, diabetes care, retail medical stores, and elderly and assisted-living users lead their axes. Mobility assist devices, neuro-rehabilitation, online retailers, and chronic-disease home care grow fastest.
Koninklijke Philips, Abbott Laboratories, Medtronic, OMRON Healthcare, and ResMed are the leading providers.
