
Digital Twins in Healthcare Market Report Scope & Overview:
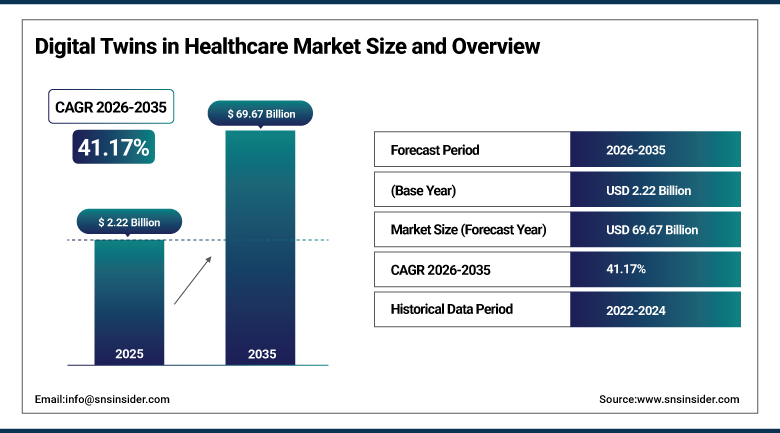
The Digital Twins in Healthcare Market was valued at USD 2.22 Billion in 2025 and is projected to reach USD 69.67 Billion by 2035, registering a CAGR of 41.17% from 2026 to 2035.
The Digital Twins in Healthcare Market is expanding rapidly as hospitals, research organizations and medical-device manufacturers adopt virtual replicas of patients, organs, equipment and care processes to simulate outcomes before committing to physical interventions. Falling sensor, computing and cloud-storage costs are making real-time physiological modeling commercially viable at a scale that was previously confined to aerospace and manufacturing. Growing clinician comfort with AI-assisted decision support is reinforcing demand for digital-twin platforms that can continuously ingest patient data and refine predictive accuracy over time.
As digital twins specific to patients become commonplace in precision medicine and drug discovery efforts, there will be reduced time frames and lower late-stage failure rates in trials. Process-level digital twins have also become commonplace within operations teams in hospitals as an aid to optimizing asset utilization, staff levels, and patient throughput. There is greater cooperation between technology firms and health care organizations, which is helping accelerate platform validation processes.
To Get more information Digital Twins in Healthcare Market - Request Free Sample Report
⮞In 2026, Siemens Healthineers showcased digital-twin and AI-driven workflow innovations at the European Congress of Radiology, supporting imaging workflow optimization and personalized treatment planning across healthcare settings.
Digital Twins in Healthcare Market Trends
-
Hospitals continue adopting process-level digital twins to optimize patient flow, staffing and high-value equipment utilization.
-
Drug developers continue incorporating patient-specific digital twins to shorten clinical trial timelines and reduce late-stage failure rates.
-
Cloud-based digital-twin platforms continue lowering the upfront infrastructure cost of deployment for mid-sized health systems.
-
Growing regulatory clarity around software-as-a-medical-device frameworks continues easing commercialization pathways for new applications.
-
AI-enabled predictive modeling continues improving the accuracy and clinical relevance of patient-specific digital twins.
-
Medical-device manufacturers continue embedding digital-twin capabilities directly into imaging and diagnostic equipment.
U.S. Digital Twins in Healthcare Market Size Outlook
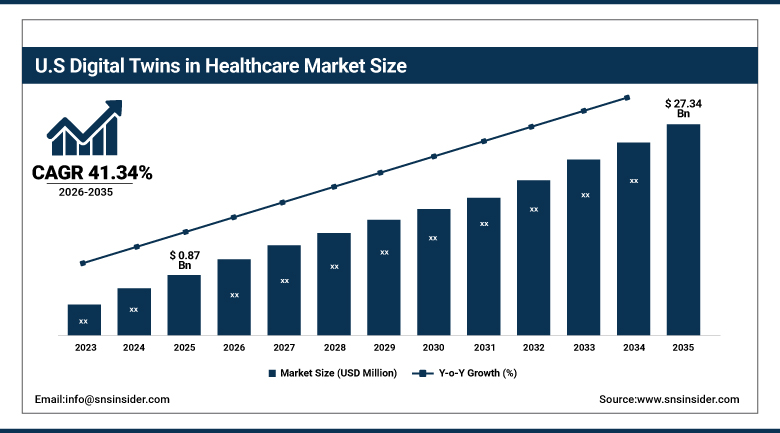
The U.S. Digital Twins in Healthcare Market was valued at approximately USD 0.87 billion in 2025 and is projected to reach approximately USD 27.34 billion by 2035, registering a CAGR of approximately 41.34% from 2026 to 2035.
Demand across the United States continued to be shaped by a dense concentration of leading health systems, academic medical centers and technology vendors willing to pilot early-stage digital-twin applications across imaging, therapy planning and hospital operations. Rising venture and strategic investment in precision-medicine and AI-enabled care platforms continued strengthening the country's position as the largest national market tracked in this report. Growing collaboration between hospital networks and cloud-computing providers added further layers of sustained demand, with payers and providers increasingly prioritizing predictive, data-driven care models alongside traditional diagnostic and treatment workflows.
⮞In February 2026, Microsoft updated its Azure Health Data Services documentation, highlighting capabilities for integrating clinical records, medical imaging and device data to support healthcare analytics and AI development.
Digital Twins in Healthcare Market Segment Analysis
-
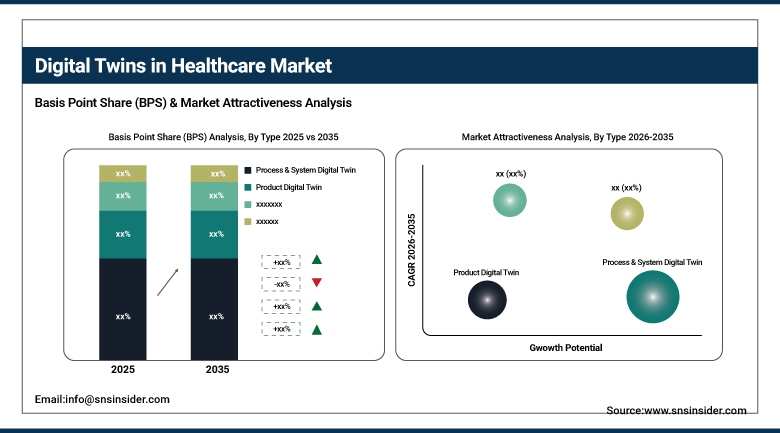
By Type, the Process & System Digital Twin segment dominated the Digital Twins in Healthcare Market in 2025 with 62.87% share; the Product Digital Twin segment is the fastest growing segment with a CAGR of approximately 42.34%.
-
By Application, the Personalized Medicine segment dominated the Digital Twins in Healthcare Market in 2025 with 41.56% share; the Drug Discovery segment is the fastest growing segment with a CAGR of approximately 43.28%.
-
By End-use, the Hospitals and Clinics segment dominated the Digital Twins in Healthcare Market in 2025 with 38.92% share; the Clinical Research Organizations segment is the fastest growing segment with a CAGR of approximately 42.67%.
By Type, Process & System Digital Twin Dominates the Digital Twins in Healthcare Market and Product Digital Twin Grows Fastest
Process & System Digital Twin solutions dominated the market in 2025, reflecting hospitals' and health systems' early focus on operational efficiency gains that deliver measurable cost savings without requiring regulatory clearance for patient-facing clinical use. Virtual replicas of care pathways, equipment fleets and facility layouts let administrators test staffing and scheduling changes before committing to physical operational shifts. This lower-risk, faster-payback profile has made process-level twins the natural entry point for most health systems building internal digital-twin expertise, reinforcing their position as the largest revenue contributor across nearly every regional market tracked in this report.
Product Digital Twin solutions, which model individual medical devices, implants and diagnostic instruments, are forecast to grow fastest as manufacturers increasingly embed virtual counterparts into device development and post-market surveillance workflows. Growing regulatory interest in digital-twin-supported device validation is reinforcing this above-average growth trajectory, particularly for implantable and surgical devices where physical testing is costly and time-consuming. Expanding collaboration between device manufacturers and simulation-software vendors is further accelerating adoption of product-level twins across the medical-device development lifecycle. Rising demand for patient-specific implant sizing and fit simulation is additionally widening the range of devices suited to this approach.
⮞In February 2026, Germany’s Fraunhofer Institute for Material Flow and Logistics launched the Green Hospital Energy Twin (GreenHET) project to digitally model hospital energy consumption and simulate operational alternatives, targeting improved energy efficiency across hospital processes.
By Application, Personalized Medicine Dominates the Digital Twins in Healthcare Market and Drug Discovery Grows Fastest
Personalized Medicine applications dominated demand in 2025, since more health systems were using patient-specific digital twins to simulate how patients would react to different treatments in fields such as oncology, cardiology, and chronic diseases. The increasing belief in simulation-driven treatment plans by healthcare providers makes personalized medicine one of the biggest sources of income as well as increased evidence about reduced trial-and-error treatment through outcomes data. The deeper integration of electronic health records into digital twin systems is making personalized medicine an everyday practice at leading academic medical centers. Also, payers’ increasing interest in outcome-based payment models is boosting the demand for simulations.
Drug Discovery applications are forecast to grow fastest as pharmaceutical developers increasingly use patient-population digital twins to simulate trial outcomes, identify responder subgroups and reduce late-stage clinical failure rates. Growing adoption of virtual control arms and in-silico trial design is reinforcing this above-average growth trajectory across both large originator companies and smaller biotech sponsors. Expanding collaboration between drug developers and specialized simulation-software vendors is further accelerating demand for drug-discovery-focused digital-twin capacity. Rising regulatory openness to simulation-supported trial submissions is further reinforcing this application's above-average growth outlook, as agencies gain comfort with virtual-trial methodologies.
⮞In February 2026, the U.S. Defense Advanced Research Projects Agency outlined its VITAL program to develop validated cardiovascular digital twins that combine patient data and biological physics to predict treatment responses, advancing computational modeling for individualized therapeutic assessment.
By End-use, Hospitals and Clinics Dominate the Digital Twins in Healthcare Market and Clinical Research Organizations Grow Fastest
Hospitals and Clinics accounted for the largest end-use share in 2025, reflecting their position as both the primary adopters and largest potential beneficiaries of operational and patient-specific digital-twin applications. Established capital budgets for health-information-technology investment and growing administrative pressure to reduce costs continue reinforcing this segment's dominant revenue contribution. Large hospital networks with multiple facilities are particularly well positioned to justify digital-twin investment given the scale economies available across shared operational and clinical modeling platforms. Growing hospital-administrator familiarity with simulation-based planning tools is further reinforcing this segment's entrenched adoption advantage.
Clinical Research Organizations are forecast to grow fastest as CROs increasingly offer digital-twin-enabled trial design services to differentiate themselves in a competitive outsourced-research market. Growing sponsor demand for faster, lower-cost trial execution is reinforcing this above-average growth trajectory, particularly for CROs serving smaller biotech companies without in-house simulation expertise. Expanding partnerships between CROs and digital-twin technology vendors are further widening the range of trial designs that can incorporate simulation-based patient modeling. Growing numbers of sponsors requesting simulation-supported protocols are further reinforcing this segment's above-average growth outlook across the outsourced-research industry.
⮞In September 2025, Axiodis CRO, a subsidiary of Oxurion, announced a strategic initiative to develop digital twins and virtual patients for clinical trials, alongside AI modules for its Exagis electronic clinical data-capture solution, directly targeting more efficient and data-driven outsourced research.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
92.52% |
|
Europe |
Germany |
29.45% |
|
Asia Pacific |
China |
38.24% |
|
Middle East and Africa |
Saudi Arabia |
34.72% |
|
Latin America |
Brazil |
39.85% |
North America Digital Twins in Healthcare Market Insights
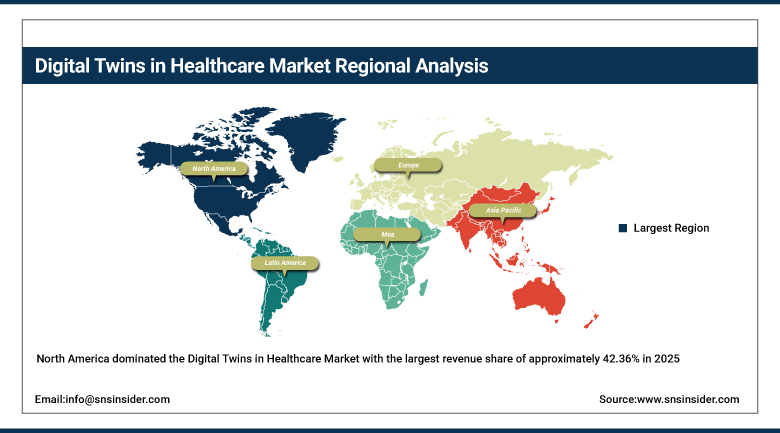
North America dominated the Digital Twins in Healthcare Market with the largest revenue share of approximately 42.36% in 2025, supported by a dense concentration of leading health systems, academic medical centers and technology vendors willing to pilot early-stage digital-twin applications. The region's deep base of cloud-computing infrastructure and AI research talent continues reinforcing its position as the leading national-market concentration tracked in this report, particularly for hospital-operations and personalized-medicine applications. Procurement groups across major health systems have also begun favoring vendors able to demonstrate validated clinical outcomes data, a preference reinforced by recent federal digital-health resilience reviews.
The United State led the regional market based on a large number of hospitals and increasing number of vendors offering digital-twin technology solutions. The contribution from Canada is lower but gradually rising as a result of use of specialized health-technology. Further investments in the development of platforms using AI technology are anticipated to help the region maintain its dominance for the remaining period of forecast, with some hospitals having plans for pilot programs in various states and provinces.
Get Customized Report as per Your Business Requirement - Enquiry Now
⮞In December 2025, GE HealthCare documented Providence Swedish’s use of its Digital Twin simulation capabilities for First Hill campus capacity-expansion planning, demonstrating how virtual hospital models can support infrastructure decisions, capacity strategy and resource allocation in U.S. healthcare systems.
Asia Pacific Digital Twins in Healthcare Market Insights
Asia Pacific is advancing at the fastest pace, growing at a CAGR of approximately 43.56% from 2026 to 2035, driven by China's and India's expanding health-technology infrastructure investment and growing government interest in digital health modernization. Rising domestic healthcare spending across both countries is additionally supporting adoption of digital-twin platforms among both public hospital systems and private health-technology companies expanding across the region. Growing availability of locally developed simulation software is further lowering adoption costs for smaller regional hospital networks.
China held the largest share of regional revenue, supported by rapid hospital-digitization investment and growing domestic AI and simulation-software capability, while India contributed substantial additional demand through government-backed digital health initiatives and a growing base of health-technology startups. Japan and South Korea added further demand through established medical-device manufacturing and research infrastructure that continues attracting digital-twin pilot programs from both domestic and international technology vendors. Growing cross-border collaboration between regional and Western technology vendors is further widening the addressable supplier base.
⮞In March 2025, Shanghai published its 2025–2027 medical AI development plan, calling for hospital digital twins that combine operational and financial data with integrated decision-support platforms, including applications for operating-room management and medicine and consumables inventory.
Europe Digital Twins in Healthcare Market Insights
Europe held a meaningful share of global revenue, supported by a long-standing medical-technology manufacturing base and continued investment in digital-health infrastructure across Germany, the United Kingdom and France. Regional regulatory harmonization under the European Medicines Agency continues to support cross-border digital-twin platform deployment within the bloc, lowering the administrative burden of serving multiple member states from a single technology platform. Deep medical-device engineering talent pools across several member states further reinforce the continent's technology competitiveness relative to lower-cost offshore alternatives, particularly for complex, research-intensive simulation platforms.
Germany continued to lead demand at roughly 29.45% of European revenue, supported by its large medical-device manufacturing base and established health-technology ecosystem, while the United Kingdom and France contributed additional demand through specialized research-institute and hospital-network adoption. Continued European investment in digital-health modernization programs should keep regional demand climbing through the forecast period, reinforced by growing EU precision-medicine policy support and coordinated national digital-health planning initiatives across the bloc's largest member states and their respective supplier ecosystems.
⮞In March 2025, Fraunhofer IGD presented its MeDiTwin work on secure medical digital twins at Berlin’s DMEA healthcare technology event, highlighting patient-controlled access to clinical information and privacy-conscious data management for digital representations used in healthcare.
MEA and Latin America Digital Twins in Healthcare Market Insights
The Middle East and Africa and Latin America both showed steady growth, driven by national healthcare-modernization programs, growing medical-technology investment, and rising government interest in digital health infrastructure across both regions. Public healthcare funding increases are creating new demand channels for hospital-operations and diagnostic digital-twin applications in both areas, with several governments setting formal digital-health modernization targets as part of broader economic-diversification agendas. Growing private-hospital investment across both regions is further widening the addressable customer base for digital-twin vendors expanding beyond their traditional core markets.
The demand within the Middle East and Africa regions was led by Saudi Arabia as a result of the country's efforts at making healthcare information digital to support the economic diversification. South Africa also played a key role through the advanced technological platform for private hospitals. In Latin America, Brazil was responsible for the leading revenues in the region whereas domestic investments in hospital technology made the demand for the digital twin platforms continue being high. México and Argentina also played an important role due to increased health technology industries in the regions.
⮞In January 2025, Saudi Arabia’s Ministry of Health announced the prequalification of companies for its Digital Twin project, identifying potential technology providers for a national initiative that reflects the country’s ongoing investment in healthcare digitalization and data-enabled service modernization.
⮞In December 2025, Brazil’s government confirmed BRICS New Development Bank financing of BRL 1.7 billion for a smart public hospital in São Paulo and announced plans for connected intensive-care services, strengthening the digital infrastructure supporting advanced analytics and technology-enabled hospital management.
Market Dynamics
Growth Drivers: AI-Enabled Care Models and Precision-Medicine Investment
The industry is driven by growing hospital investment in operational efficiency technology, expanding precision-medicine and drug-discovery applications for patient-specific simulation, and rising clinician confidence in AI-assisted decision support across aging and increasingly chronic-disease-burdened populations. As health systems prioritize both cost containment and improved clinical outcomes, demand for both operational and patient-specific digital-twin applications continues rising.
Growing cloud-computing capacity investment is reinforcing this driver by giving health systems and biotech companies flexible access to simulation infrastructure without requiring in-house capital investment. Continued government funding for digital-health modernization, particularly across North America, Europe and parts of Asia, is further widening the addressable customer base able to justify early digital-twin platform investment.
In February 2026, the U.S. Defense Advanced Research Projects Agency outlined its VITAL program to develop and validate cardiovascular digital twins integrating real-time patient data with biological physics, supporting efforts to predict individual treatment responses and strengthen data-driven clinical decision-making.
Restraints: High Implementation Costs and Data-Integration Complexity
High implementation and integration costs continue posing a restraint on faster market-wide expansion, as building accurate digital-twin models requires substantial investment in sensors, data infrastructure and specialized modeling expertise before measurable returns materialize. Many health systems, particularly smaller or resource-constrained hospitals, continue lacking the capital and technical staff needed to deploy digital-twin platforms at meaningful scale.
Data-integration complexity across fragmented electronic health record systems also complicates digital-twin deployment decisions for health systems operating multiple legacy platforms. Because validating a new digital-twin application against real-world clinical outcomes can take several years, some hospitals continue favoring narrower, lower-risk operational pilots over broader patient-specific clinical deployment.
Opportunities: Emerging-Market Digitization and Drug-Discovery Expansion
Growing digital-health infrastructure investment across India, China, Brazil and the Middle East represents a significant opportunity, as government modernization programs and rising domestic healthcare demand create new adoption channels for both operational and clinical digital-twin applications. Technology vendors positioned early in these emerging markets stand to capture meaningful share as digital-health modernization continues.
Expansion into drug-discovery and clinical-trial simulation applications offers a second substantial opportunity for digital-twin vendors able to demonstrate measurable reductions in development timelines and trial costs. Continued collaboration between pharmaceutical sponsors and specialized simulation-software vendors is expected to further accelerate this opportunity through the remainder of the forecast period.
⮞In September 2026, Japan’s Ono Pharmaceutical entered a drug-discovery partnership with Aitia to use its Gemini Digital Twin platform to identify neurological-disease drug targets, illustrating growing commercial interest in virtual patient models for therapeutic discovery and development.
Recent Developments:
-
2026, the European Union launched TWIN-X, a €15 million project coordinated by TUM Klinikum to develop digital patient twins integrating imaging, clinical records, laboratory data and pathology for personalized oncology and cardiology research.
-
2025, the EU-funded EDITH project released its European Virtual Human Twin roadmap, outlining interoperable infrastructure, ethical standards and coordinated investments to advance personalized healthcare, clinical research and digital-twin adoption across Europe.
-
2025, the European Commission initiated development of an advanced Virtual Human Twins platform, enabling researchers and clinicians to integrate, combine and validate computational models using shared resources, supercomputing and privacy-preserving synthetic data.
-
2026, the EU-funded CERTAINTY project highlighted progress toward virtual twins for personalized CAR-T cell therapy, aiming to model patient responses and support treatment decisions in cancer care, with future validation of clinical benefits planned.
Digital Twins in Healthcare Companies are:
-
Siemens Healthineers AG
-
Dassault Systèmes SE
-
GE Healthcare Technologies Inc.
-
Philips Healthcare
-
Microsoft Corporation
-
ANSYS, Inc.
-
Atos SE
-
Oracle Corporation
-
IBM Corporation
-
Unlearn.AI, Inc.
-
Twin Health, Inc.
-
Q Bio, Inc.
-
Virtonomy GmbH
-
PrediSurge
-
NVIDIA Corporation
-
Hewlett Packard Enterprise Company
-
Altair Engineering Inc.
-
InSilicoTrials Technologies, Inc.
-
Faststream Technologies
-
Cortex Labs
Digital Twins in Healthcare Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.22 Billion |
| Market Size by 2035 | USD 69.67 Billion |
| CAGR | CAGR of 41.17% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Process & System Digital Twin, Product Digital Twin) • By Application (Asset and Process Management, Personalized Medicine, Drug Discovery, Others) • By End-use (Clinical Research Organizations (CROs), Hospitals and Clinics, Research & Diagnostic Laboratories, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Siemens Healthineers AG, Dassault Systèmes SE, GE HealthCare Technologies Inc., Philips Healthcare, Microsoft Corporation, ANSYS, Inc., Atos SE, Oracle Corporation, IBM Corporation, Unlearn.AI, Inc., Twin Health, Inc., Q Bio, Inc., Virtonomy GmbH, PrediSurge, NVIDIA Corporation, Hewlett Packard Enterprise Company, Altair Engineering Inc., InSilicoTrials Technologies, Inc., Faststream Technologies, Cortex Labs |

Frequently Asked Questions
Key players include Siemens Healthineers, Dassault Systèmes, GE Healthcare, Philips Healthcare, Microsoft, IBM, Oracle and NVIDIA, among others.
Key opportunities include emerging-market digital-health infrastructure investment and expansion into drug-discovery and clinical-trial simulation applications.
The market is driven by growing hospital investment in operational efficiency technology, expanding precision-medicine applications, and rising clinician confidence in AI-assisted decision support.
The Process & System Digital Twin segment dominates the Digital Twins in Healthcare Market, accounting for approximately 62.87% share in 2025.
North America dominated the Digital Twins in Healthcare Market in 2025 with approximately 42.36% share, driven by a dense concentration of leading health systems and technology vendors.
