
Educational Audiovisual System Market Report Scope & Overview:
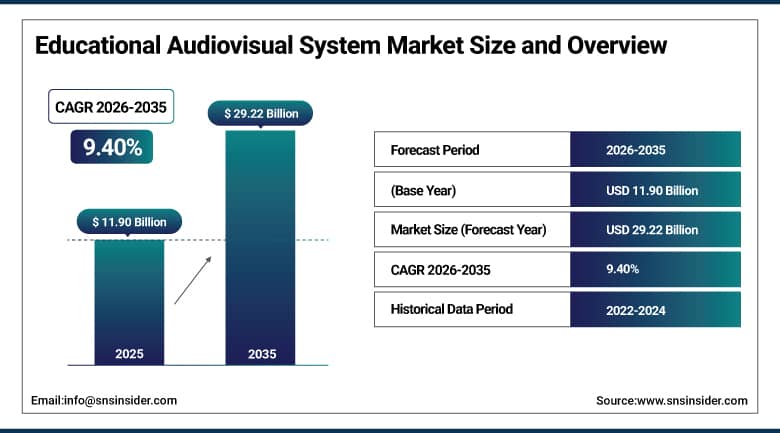
The Educational Audiovisual System Market was valued at USD 11.90 Billion in 2025 and is expected to reach USD 29.22 Billion by 2035, growing at a CAGR of 9.40% from 2026-2035.
The Educational Audiovisual Systems Market is expected to witness growth owing to the installation of systems such as projectors, displays, cameras, microphones, speakers, control equipment and software in classrooms and lecture theaters for educational purposes. This market is being propelled by intelligent classroom programs, hybrid or distance learning, investments by the government for digital infrastructure development, upgrades from older generation projector and display devices to laser and flat panels and adoption of cloud platforms and artificial intelligence in teaching aids. The organizations prefer solutions that are easily operable for the teachers, manageable for IT professionals and are compatible with existing learning platforms and video conferencing applications.
⮞In February 2026, ahead of ISE 2026 in Barcelona, Epson launched the EB-870Ei, an interactive ultra-short-throw laser projector for classrooms that adds 4K Enhancement resolution and better sound. It connects through Epson iProjection, Miracland, Wi-Fi and Ethernet, and simplifies installation with a faster wall mount, a setup app for display alignment, rechargeable interactive pens and a USB-C control box. The launch reflects demand from schools for devices that lower installation effort and maintenance.
To Get More Information On Educational Audiovisual System Market - Request Free Sample Report
Educational Audiovisual System Market Trends
-
Shift from lamp projectors to laser projectors and large interactive flat-panel displays
-
Growth of hybrid classrooms with cameras, microphones and lecture capture
-
Integration of artificial intelligence features such as auto-framing, captioning and translation
-
Standardized control and AV-over-IP systems that simplify campus-wide management
-
Adoption of augmented and virtual reality for laboratories and training
-
Bundling of hardware, cloud software and managed services under subscription plans
U.S. Educational Audiovisual System Market Outlook
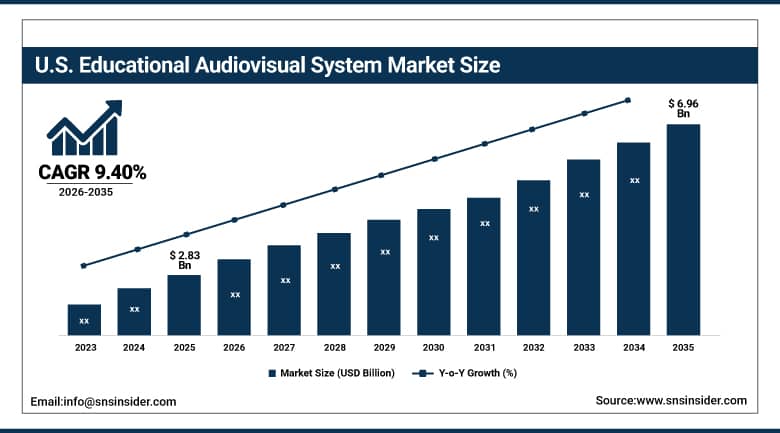
The U.S. Educational Audiovisual System Market was valued at USD 2.83 Billion in 2025 and is expected to reach USD 6.96 Billion by 2035, growing at a CAGR of 9.40% from 2026-2035.
The U.S. Educational Audiovisual System Market is the largest national market, supported by a vast base of school districts, colleges and universities, federal and state technology funding and a mature network of integrators and distributors. Districts replace projectors and whiteboards with interactive flat panels on regular refresh cycles, while universities invest in hybrid-capable lecture halls, collaboration spaces and active-learning classrooms. Procurement tends to favor equipment that can interface well with the more popular learning management systems and video conferencing systems, and cybersecurity issues, accessibility, and overall total cost of ownership become very critical considerations. The competition in the display market, as well as the video conferencing and integration markets, is fierce, and service agreements are significant sources of vendor income.
⮞In June 2026, Boxlight launched its Symphonic Series of interactive displays, which pair high-definition touchscreens with proprietary software for real-time content sharing and remote engagement. The displays include built-in audio and options to synchronize several devices, and they are designed for rooms ranging from small meeting spaces to large lecture halls, serving as a hub for digital presentations, interactive lessons and video conferencing.
Educational Audiovisual System Market Segment Analysis
-
By Equipment Type, the Projectors segment dominated the Educational Audiovisual System Market with approximately 24.00% share in 2025, while the Video Conferencing Equipment segment is the fastest growing with a CAGR of approximately 11.50%.
-
By Component, the Hardware segment dominated the Educational Audiovisual System Market with approximately 62.00% share in 2025, while the Software segment is the fastest growing with a CAGR of approximately 12.30%.
-
By End User, the Higher Education Institutions segment dominated the Educational Audiovisual System Market with approximately 28.40% share in 2025, while the K-12 Educational Institutions segment is the fastest growing with a CAGR of approximately 10.60%.
-
By Application Area, the Classroom Settings segment dominated the Educational Audiovisual System Market with approximately 41.00% share in 2025, while the Distance Learning Environments segment is the fastest growing with a CAGR of approximately 11.00%.
-
By Technology Type, the Digital Systems segment dominated the Educational Audiovisual System Market with approximately 38.60% share in 2025, while the Augmented and Virtual Reality Systems segment is the fastest growing with a CAGR of approximately 11.80%.
By Equipment Type, Projectors Lead While Video Conferencing Equipment Grows Fastest
Projectors lead because they remain the most widely installed display technology in classrooms and lecture halls, offering large images at moderate cost. Laser light sources, ultra-short-throw lenses and interactive modules have extended product life, reduced maintenance and made projection suitable for collaborative teaching. Educational institutions that have low budgetary allocations tend to favor projectors in their larger rooms, while universities make use of high-brightness projectors in their auditoriums. The main factors used by manufacturers to distinguish their products include resolution and brightness.
Video conferencing equipment is advancing fastest as hybrid and remote participation become routine. Cameras with auto-framing and speaker tracking, ceiling and table microphones, soundbars and room control units allow remote students to join lessons and lectures with good sound and picture. Institutions want solutions that work with common conferencing and learning platforms and that require little training. Interactive displays and whiteboards are also gaining share as flat panels replace projectors in classrooms, and audio reinforcement systems help students at the back hear clearly.
⮞In May 2026, ViewSonic launched its LSD500HD and LSD600W laser installation projectors, featuring third-generation laser-phosphor technology, high brightness and flexible 360-degree installation, expanding options for educational institutions seeking durable, low-maintenance large-screen display systems.
By Component, Hardware Leads While Software Grows Fastest
Hardware leads because displays, projectors, cameras, microphones, speakers, switchers and mounts make up the bulk of spending when rooms are built or refreshed. Institutions typically buy equipment in large batches funded through capital budgets, grants or bonds, and refresh cycles of five to eight years sustain demand. Quality, reliability and warranty terms are central, and integrators provide installation and commissioning. Vendors compete on picture quality, ease of use and compatibility with existing room infrastructure.
The software market is booming, thanks to the movement of value towards device management, collaboration software, lecture capture, analysis and content sharing. Cloud-based management systems allow the IT department to track thousands of devices, perform remote updates, troubleshoot problems, and teaching software offers features such as annotations, polls, screen sharing and learning management system integration. Services including design, installation, training and support are expanding as institutions seek predictable costs, and subscription models are replacing one-time purchases for many software and support offerings.
⮞In February 2025, Meta made Meta for Education generally available, combining Meta Quest headsets with managed educational services to help institutions administer immersive learning experiences and educational applications, illustrating the expansion of software platforms accompanying audiovisual hardware.
By End User, Higher Education Institutions Lead While K-12 Educational Institutions Grow Fastest
Higher education institutions lead because universities and colleges operate large numbers of lecture halls, laboratories, studios and collaboration spaces that require professional audiovisual systems. They invest in lecture capture, hybrid delivery and active-learning rooms to attract students and support online programs. Campus-wide standardization and centralized management are priorities, so universities favor integrated systems with strong control and monitoring. Budgets are comparatively large, and procurement often involves specialized integrators.
K-12 educational institutions are growing fastest as public funding for digital learning, device refresh programs and classroom connectivity reaches primary and secondary schools. Teachers adopt interactive flat panels, wireless presentation tools and audio systems that improve engagement and accessibility. Simplicity, durability and low maintenance are decisive in schools with limited technical staff. Vocational and corporate training centers form another end user group, investing in simulation, remote instruction and collaboration spaces to support workforce development.
⮞In March 2025, Brazil's Ministry of Education released a guide for planning technology adoption in schools under its National Connected Schools Strategy, providing guidance on educational-device procurement and supporting the planned integration of digital technologies into primary and secondary education.
By Application Area, Classroom Settings Lead While Distance Learning Environments Grow Fastest
Classroom settings lead because the classroom is the primary place of instruction, and each room needs at least a display or projector, sound and connectivity. Smart classroom programs are equipping rooms with interactive panels, wireless casting, document cameras and sound reinforcement, and the large number of rooms makes this the biggest volume segment. Teachers value systems that start quickly and work with their devices and learning platforms, and districts choose standardized packages to simplify training and support.
Distance learning environments are growing fastest as institutions expand online and hybrid programs, record lectures and broadcast classes to remote audiences. Studios, hybrid-ready lecture halls and teacher kits with cameras, microphones and lighting enable high-quality delivery. Lecture halls and auditoriums continue to need large displays, audio and control systems, and specialized spaces such as laboratories, libraries and maker rooms add further demand. Cloud platforms that record, caption and distribute content are becoming part of the audiovisual stack.
⮞In October 2025, India's Ministry of Electronics and Information Technology launched the NIELIT Digital University platform, offering flexible digital learning and virtual laboratories for technology-focused education, supporting demand for audiovisual-enabled online instruction and remotely accessible learning environments.
By Technology Type, Digital Systems Lead While Augmented and Virtual Reality Systems Grow Fastest
Digital systems lead because nearly all new installations use digital video, audio and control, with network-based distribution replacing legacy cabling. High-definition displays, wireless connectivity and AV-over-IP allow flexible room layouts and remote management, and they integrate easily with computers, tablets and cloud services. Institutions upgrading older analog rooms usually move straight to digital and network-connected equipment, and manufacturers have largely stopped developing new analog products.
Augmented and virtual reality systems are growing fastest from a small base as schools and universities use immersive content for science, medicine, engineering, vocational training and language learning. Headsets, projection-based immersive rooms and mixed-reality displays allow students to practice procedures and explore environments that would be costly or unsafe in real life. Costs are falling and content libraries are expanding, but teacher training and classroom management remain hurdles. Analog systems persist in some budget-constrained settings but continue to decline.
⮞In September 2026, Avantis Education launched EduverseSTEM, an immersive STEM learning suite combining ClassVR Xcelerate headsets with more than 500 curriculum-aligned experiences, expanding the use of augmented and virtual reality tools in secondary education.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
69.00 |
|
Asia Pacific |
China |
36.20 |
|
Europe |
United Kingdom |
26.30 |
|
Latin America |
Brazil |
43.70 |
|
Middle East & Africa |
Saudi Arabia |
32.40 |
North America Educational Audiovisual System Market Insights
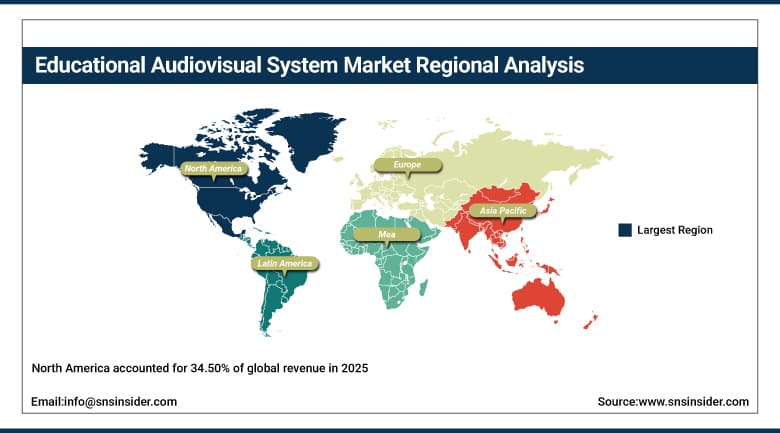
North America accounted for 34.50% of global revenue in 2025, making it the largest regional market for educational audiovisual systems. The United States leads through thousands of school districts and campuses, federal and state funding for educational technology and an extensive network of integrators and distributors. Canada contributes through provincial investment in classroom technology and university upgrades. Institutions replace equipment on regular cycles and are early adopters of interactive flat panels, hybrid-ready lecture halls and cloud device management.
The competition between companies making displays, conferencing and integrating products, and the quality of services are determining factors. Accessibility standards, cyber security considerations, and interoperability with learning management systems will determine product features. Trade shows for education professionals play an important role in bringing new products to market. The budget cycle, grants, and the expiration of pandemic money affect buying cycles, as school districts look for durable and maintenance-free products.
⮞In August 2026, the U.S. Department of Education issued guidance on responsible classroom technology use, encouraging schools to prioritize instructional value, evidence, educator judgment and student outcomes when selecting and implementing educational technologies.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Educational Audiovisual System Market Insights
Asia Pacific is projected to be the fastest-growing region, advancing at a CAGR of 11.20% from 2026-2035. China leads regional demand through national education informatization programs and a large base of schools and universities, followed by India, Japan, South Korea and Australia. Student population growth, smart campus initiatives and government attention to digital education drive the build-out of classrooms equipped with interactive displays, cameras and wireless collaboration tools. Local manufacturers compete strongly on price, and global brands partner with regional distributors.
India is a major growth market as state and national programs equip government schools with digital boards and as private institutions expand. Japan and South Korea emphasize advanced displays and high-reliability systems, while Southeast Asian countries invest in connectivity and classroom technology. Infrastructure gaps in rural areas, uneven teacher training and price sensitivity remain challenges, so rugged, simple and affordable solutions with strong after-sales support are favored.
⮞In March 2025, Brazil's National Education Council published Resolution CNE/CEB No. 2/2025, establishing national operational guidelines for digital devices in schools and integrating digital and media education into curricula, providing a policy framework for pedagogical technology adoption.
Europe Educational Audiovisual System Market Insights
Europe is a mature market with steady demand from universities, schools and training centers. The United Kingdom, Germany and France lead regional spending, supported by national digital education strategies and recovery funding for technology. The Bett show in London is a prominent venue where vendors present new classroom displays and software, and integrated ecosystems for schools and campuses are a common theme. Universities invest in hybrid teaching spaces and lecture capture, and secondary schools continue to replace projectors with interactive panels.
Energy efficiency, sustainability and data protection are important purchasing criteria, favoring laser and LED technologies with long lifetimes and devices that comply with privacy rules. Multilingual needs and varied curricula encourage flexible software. Public tenders are common, which rewards vendors with strong references and integrators with local presence. Northern and Western Europe are further advanced, while Southern and Eastern Europe are catching up with the help of European Union funding.
⮞In July 2025, the United Kingdom's Department for Education announced plans for schools and colleges to meet six digital standards by 2030, aiming to improve classroom technology reliability, safety and connectivity and reduce disparities in access to educational technology.
MEA & Latin America Educational Audiovisual System Market Insights
In the Middle East and Africa, demand is concentrated in Saudi Arabia, the United Arab Emirates, Qatar and South Africa, where governments invest heavily in education transformation, smart schools and new university campuses. Gulf states procure integrated classroom systems at scale and favor global brands with local support. In much of Africa, projects supported by donors and governments equip schools with basic digital tools, and ruggedness and low power use matter as much as features.
In Latin America, Brazil and Mexico lead consumption, supported by public programs for school connectivity, expanding private universities and growing interest in hybrid learning. Budget limits and currency volatility make financing and lower-cost options important, and distributors and integrators play a large role. International lenders and technology firms fund pilot projects and teacher training. As connectivity improves, both regions are expected to add steadily to global revenue from a smaller base.
⮞In March 2025, Brazil's National Education Council published Resolution CNE/CEB No. 2/2025, establishing national operational guidelines for digital devices in schools and integrating digital and media education into curricula, providing a policy framework for pedagogical technology adoption.
Growth Drivers: Smart Classroom Programs, Hybrid Learning and Funding
Smart classroom programs are a primary driver. Governments and school systems are equipping classrooms with interactive displays, wireless presentation, cameras and sound to support digital curricula and connected devices. These programs create large, repeating purchases because each room needs a standard package, and replacement cycles for projectors and whiteboards keep the installed base turning over. Teachers and students increasingly expect rich media and collaboration as part of everyday instruction.
Hybrid learning and funding add momentum. The universities and educational institutions still provide remote and recorded classes which need cameras, microphones, recording software and network. The public funding, bond and recovery programs enable buying technologies, while improvements in broadband infrastructure help implement cloud-based systems. The new generation of laser projectors, flat screens, wireless technologies and artificial intelligence solutions like automatic framing and live captioning makes systems better and more effective.
⮞In February 2026, the U.S. Department of Education listed its Accessible Education Video Projects grant opportunity to support audio description, open captioning and closed captioning for educational media in early-learning and K–12 settings, highlighting opportunities for accessible audiovisual content and inclusive classroom technologies.
Restraints: High Upfront Costs, Support Needs and Budget Constraints
The initial as well as follow-up costs involved act as a barrier, particularly for organizations which have limited budgetary allocations. Interactive whiteboards along with cameras and other controls are costly to procure and set up, and maintenance, licensing of software, and replacement of spares contribute to the overall costs involved. Organizations having few technical personnel find it difficult to maintain such complicated equipment, and any failure may interrupt learning sessions.
Friction is caused by skills and compatibility issues. Teachers require training to make efficient use of technology; otherwise, the equipment will not be used efficiently. A mix of old and new equipment makes managing it difficult. Issues like budget allocation to staffing, buildings, and student devices among other competing issues may slow down the process of improving audiovisual equipment.
Opportunities: Artificial Intelligence, Managed Services and Emerging Markets
Artificial intelligence offers significant opportunity, as features such as automatic framing, noise suppression, real-time captioning and translation, and attendance or engagement analytics make rooms easier to use and more inclusive. Cloud management platforms that monitor health, predict failures and automate updates reduce support burdens for institutions with small IT teams. Vendors that build open ecosystems integrating with learning platforms will capture more of the software and services spending.
There is also scope for managed services and the developing markets. Managed service model and device as a service help distribute costs and include installation, maintenance and refreshment, which is ideal for cash-strapped educational institutes. Digital learning programs funded by the government in India, South East Asia, Middle East, Africa, and Latin America result in big business for the AV industry. A partnership between audio visual vendors and e-learning companies may prove fruitful.
⮞In February 2026, the U.S. Department of Education listed its Accessible Education Video Projects grant opportunity to support audio description, open captioning and closed captioning for educational media in early-learning and K–12 settings, highlighting opportunities for accessible audiovisual content and inclusive classroom technologies.
Recent Developments:
-
2026: ViewSonic announced the showcase of next-generation ViewBoard interactive displays at Bett 2026 in London, which it said would be the first on the market to launch with Android 16. The company also planned to demonstrate an enhanced myViewBoard software suite with updated teaching and collaboration tools, along with LED displays for lecture halls and campus spaces.
-
2026: Logitech presented its 120 square meter Connected Classroom showcase at ISE 2026, featuring education offerings built around single-cable camera extensions and simpler USB deployment. The company highlighted its Rally Camera Streamline Kit as a way to streamline installation for IT staff, while supporting both live and self-paced learning for teachers.
-
2026: Sharp Display Solutions Europe previewed its LB3 Series interactive displays, extending its portfolio with 65-, 75-, and 86-inch models designed for collaborative spaces, including higher education.
Educational Audiovisual System Market Key Players are:
-
Cisco Systems, Inc.
-
NEC Display Solutions
-
Poly (HP Inc.)
-
Planar Systems, Inc.
-
Extron Electronics
-
AVI-SPL
-
CCS Presentation Systems
-
Diversified
-
Epson
-
ViewSonic Corporation
-
Logitech International S.A.
-
Boxlight Corporation
-
Promethean Limited
-
SMART Technologies
-
Samsung Electronics Co., Ltd.
-
LG Electronics Inc.
-
Panasonic Holdings Corporation
-
Biamp Systems
Educational Audiovisual System Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 11.90 Billion |
| Market Size by 2035 | USD 29.22 Billion |
| CAGR | CAGR of 9.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Equipment Type (Projectors, Interactive Displays and Whiteboards, Video Conferencing Equipment, Audio Systems, Others) • By Component (Hardware, Software, Services) • By End User (Higher Education Institutions, K-12 Educational Institutions, Vocational and Corporate Training Centers) • By Application Area (Classroom Settings, Distance Learning Environments, Lecture Halls and Auditoriums, Hybrid Learning Environments, Others) • By Technology Type (Digital Systems, Analog Systems, Augmented and Virtual Reality Systems) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Cisco Systems, Inc., NEC Display Solutions, Sony Group Corporation, Poly (HP Inc.), Planar Systems, Inc., Extron Electronics, AVI-SPL, CCS Presentation Systems, Diversified, Crestron Electronics, Inc., Epson, ViewSonic Corporation, Logitech International S.A., Boxlight Corporation, Promethean Limited, SMART Technologies, Samsung Electronics Co., Ltd., LG Electronics Inc., Panasonic Holdings Corporation, Biamp Systems |

Frequently Asked Questions
Key players include Cisco Systems, Inc., NEC Display Solutions, Sony Group Corporation, Poly (HP Inc.), Planar Systems, Inc., and Biamp Systems, among others.
Key opportunities include artificial intelligence features and cloud management, managed and subscription services, immersive learning technologies, and government-funded digital education programs in emerging markets.
The major growth factor is the expansion of smart classroom programs and hybrid learning, supported by public funding and the replacement of aging projectors and whiteboards.
By Application Area, the Classroom Settings segment dominated the market with approximately 41.00% share in 2025, as every classroom requires displays, sound and connectivity.
North America dominated the market with a share of 34.50% in 2025, supported by a large base of schools and campuses, federal and state funding and a mature integrator network in the United States.
