
Electromagnetic Weapons Market Report Scope & Overview:
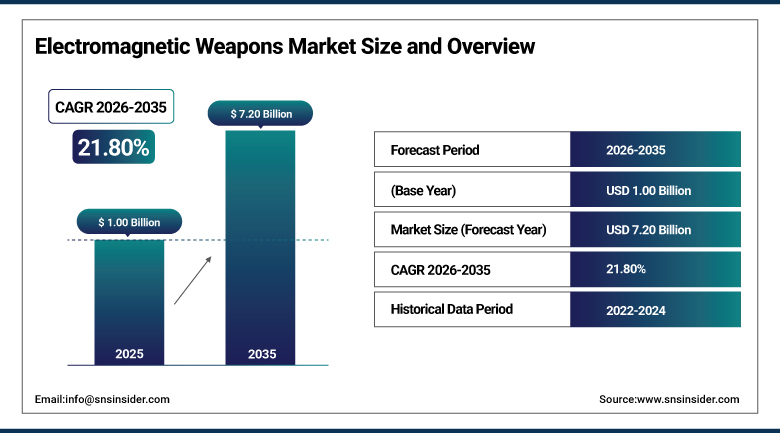
The Electromagnetic Weapons Market was valued at USD 1.00 Billion in 2025 and is expected to reach USD 7.20 Billion by 2035, growing at a CAGR of 21.80% from 2026-2035.
Growth in the Electromagnetic Weapons market is mainly influenced by the fast adoption of inexpensive unmanned aerial systems and swarm drones, which prove difficult to defend using conventional weapons, leading defense organizations to deploy technologies that utilize high-powered microwaves and directed energy that have the ability to disable many targets in a single engagement. Growing geopolitical conflicts and modernization initiatives among leading military nations keep the need for non-kinetic technologies to destroy electronic and communications systems without any associated risk of damage to civilians through conventional munitions. Artificial intelligence and software-defined weapon development are adding another dimension to these weapons, enabling them to be multi-functional, upgradeable, and reprogrammed against emerging threats through software rather than through hardwiring.
Epirus secured an additional $250 million in funding in March 2025 for its Leonidas high-power microwave weapon program, enabling the company to scale up production, expand its manufacturing footprint in the United States, and broaden its market reach to meet growing global demand for directed-energy defense systems. Company founder Joe Lonsdale described the technology as becoming determinative for the future of warfare, framing Leonidas as a shift from a traditional one-to-one defense model toward a scalable one-to-many approach capable of countering the highly networked, distributed drone threats increasingly littering modern battlefields.
To Get more information Electromagnetic Weapons Market - Request Free Sample Report
Electromagnetic Weapons Market Trends
-
Rising deployment of high-power microwave systems for counter-drone swarm defense across land, naval, and installation protection applications.
-
Growing integration of software-defined weaponeering enabling continuous system upgrades without hardware redesign.
-
Expanding naval adoption of electromagnetic weapons for countering missile and drone threats to warships.
-
Increasing partnerships between defense technology startups and established prime contractors integrating directed-energy payloads into existing platforms.
-
Growing government investment in electromagnetic launch technologies for air and missile defense applications.
-
Rising international export interest in directed-energy systems as procurement restrictions ease in select supplier countries.
U.S. Electromagnetic Weapons Market Outlook
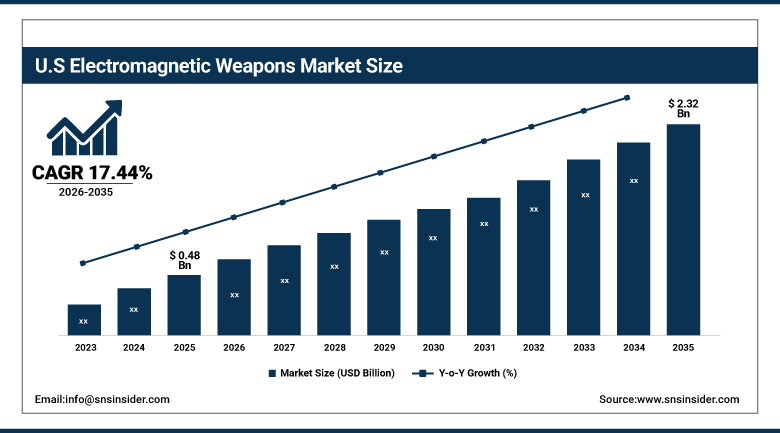
The U.S. Electromagnetic Weapons Market was valued at USD 0.48 Billion in 2025 and is expected to reach USD 2.32 Billion by 2035, growing at a CAGR of 17.44% from 2026-2035.
The U.S. Electromagnetic Weapons Market growth continues to be reinforced by sustained Department of Defense investment in directed-energy counter-drone systems, as the U.S. Army and Marine Corps have both procured operational high-power microwave systems to address the accelerating threat posed by low-cost, highly networked unmanned aerial systems. Continued Army modernization initiatives and rapid prototyping programs administered through the Rapid Capabilities and Critical Technologies Office continue to shorten the path from prototype to fielded capability, supporting sustained domestic demand across multiple electromagnetic weapon technology categories.
The U.S. Army awarded Epirus a $43 million contract in July 2025 covering two Generation II Integrated Fires Protection Capability High-Power Microwave systems, part of a development and validation phase that included testing and evaluation at the Naval Air Weapons Station China Lake in California. The Army has already purchased six Leonidas systems while the Marine Corps has acquired two, marking the first material-released directed energy counter-unmanned aerial system fielded within U.S. military service and reflecting the technology's transition from prototype demonstration into operational deployment.
Electromagnetic Weapons Market Segment Analysis
-
By Product, the Lethal Weapons segment dominated the Electromagnetic Weapons Market with approximately 67.40% share in 2025, while the Non-Lethal Weapons segment is the fastest growing with a CAGR of approximately 24.60%.
-
By Technology, the High Laser-Induced Plasma Channel segment dominated the Electromagnetic Weapons Market with approximately 61.30% share in 2025, while the Particle Beam Weapons segment is the fastest growing with a CAGR of approximately 25.80%.
-
By Platform, the Land-Based segment dominated the Electromagnetic Weapons Market with approximately 51.20% share in 2025, while the Naval segment is the fastest growing with a CAGR of approximately 24.20%.
-
By Application, the Military segment dominated the Electromagnetic Weapons Market with approximately 73.10% share in 2025, while the Homeland Security segment is the fastest growing with a CAGR of approximately 23.60%.
By Product, Lethal Weapons Dominates the Electromagnetic Weapons Market and Non-Lethal Weapons Grows Fastest
Lethal weapons continue to anchor the product segment, as defense agencies prioritize systems capable of permanently neutralizing high-value targets, including missiles, unmanned aerial systems, and armored platforms, at a fraction of the per-engagement cost conventional interceptor missiles require. This cost advantage becomes particularly significant against drone swarms, where a single lethal electromagnetic engagement can disable multiple low-cost threats simultaneously rather than requiring one expensive interceptor per incoming target, a mathematics that increasingly favors electromagnetic solutions over traditional kinetic defense. Defense budgets across multiple regions continue to prioritize lethal directed-energy procurement as a scalable answer to the growing volume of low-cost threats militaries must now defend against on a daily basis.
Non-lethal weapons represent the fastest-growing product category, driven by expanding interest in electronic disruption capabilities for crowd control, perimeter security, and scenarios where permanently destroying enemy equipment is neither necessary nor politically desirable. Homeland security and law enforcement agencies are increasingly evaluating non-lethal directed-energy options as an alternative to conventional less-lethal munitions, particularly for securing critical infrastructure and public events against unauthorized drone incursions without resorting to destructive countermeasures. Regulatory frameworks governing non-lethal weapon deployment also remain notably more permissive across civilian and homeland security applications than those governing lethal systems, which continue to require extensive military-specific authorization before fielding.
By Technology, High Laser-Induced Plasma Channel Dominates the Electromagnetic Weapons Market and Particle Beam Weapons Grows Fastest
Laser-induced plasma channel technology continues to hold dominance in the technology market due to its high engagement capability that enables the creation of a plasma channel from which electricity can be sent to a target more accurately than in other diffuse electromagnetic pulse technology options. The increased accuracy and specificity of the technology have made it very favorable for long-range targeting of high-value targets, as it does not necessarily involve area-wide effects like other directed energy weapon options. Improvement in targeting software has enabled the technology to successfully engage multiple fast-moving targets within very short intervals of time, thus increasing its application in both stationary defense facilities and mobile platforms.
The particle beam weapon technology is the fastest growing technology type in terms of value, with continuous research focused on sending charged or uncharged particles towards a target at almost the same speed as light being expected to make it even faster and more accurate compared to laser technology for certain purposes. Even though development of this technology is currently not as advanced compared to the development of high-power microwave or laser-induced plasma technology, government research grants have been crucial in enabling fast development in the technology.
By Platform, Land-Based Dominates the Electromagnetic Weapons Market and Naval Grows Fastest
Land-based platforms hold the largest share of the platform segment, reflecting the practical advantage ground-based systems offer in terms of available power generation capacity and the ability to protect fixed installations, forward operating bases, and mobile ground formations against drone swarm threats. Vehicle-mounted configurations, including systems integrated onto armored platforms, have further expanded land-based deployment flexibility, allowing directed-energy protection to accompany maneuvering ground forces rather than remaining confined to static defensive positions. Air-based platforms occupy a smaller but strategically important role within the broader platform segment, offering the ability to project directed-energy protection over wider geographic areas than fixed ground installations can typically cover.
Naval platforms represent the fastest-growing segment, as naval forces increasingly integrate electromagnetic weapons into shipboard defense systems to counter the growing threat of missile and drone swarm attacks against surface vessels. Warships offer a real power generation advantage over land-based or airborne platforms, since a vessel's propulsion and electrical systems can support the substantial power draw high-power microwave and laser-based systems require, making naval integration a particularly attractive pathway for scaling these technologies. The naval segment's rapid growth is also being reinforced by several navies' publicly stated intent to integrate directed-energy weapons as standard equipment on next-generation destroyer and frigate classes currently in design or early construction phases.
By Application, Military Dominates the Electromagnetic Weapons Market and Homeland Security Grows Fastest
Military uses have continued to dominate in the broader market in keeping with the military background of electromagnetic weapons in terms of defense research intended to deal with advanced threats from missiles, drones, and electronic warfare on the battlefield. Continuous allocation of defense budgets for research in directed-energy and non-kinetic systems has continued to emphasize this application as the most significant in the coming years. Militaries around the world are increasingly viewing electromagnetic weapons as a critical element in the layered air and missile defense system and not just as an experimental component.
Homeland security applications will be the fastest growing as homeland security agencies have come to appreciate the dangers posed by unmanned drones, which can easily infiltrate public places, critical infrastructure, and government installations. Homeland security departments are increasingly looking at electromagnetic weapons to counter drone threats. The agencies responsible for border security and the protection of critical infrastructure are increasingly testing electromagnetic weapon systems to complement other security systems, especially as the use of drones in surveillance and smuggling activities continues to grow. Technology transfer from military-originated systems to homeland security will become easier due to the collaboration between the two.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
France |
25.80% |
|
Asia Pacific |
China |
41.20% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
Israel |
32.40% |
North America Electromagnetic Weapons Market Insights
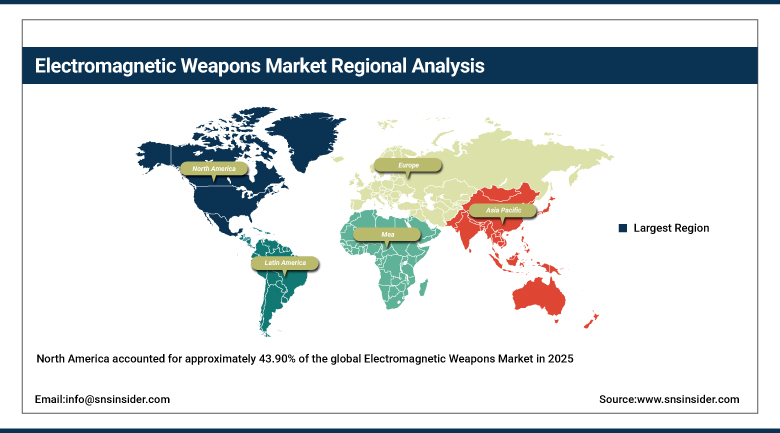
North America accounted for approximately 43.90% of the global Electromagnetic Weapons Market in 2025, making it the largest regional market, supported by sustained U.S. Department of Defense investment in directed-energy counter-drone systems and a concentration of leading electromagnetic weapons developers, including RTX Corporation, Lockheed Martin, and Northrop Grumman. Rapid prototyping programs administered through the Army's Rapid Capabilities and Critical Technologies Office continue to accelerate the transition from experimental demonstration to fielded operational capability, reinforcing the region's leading position. Sustained bipartisan congressional support for directed-energy weapons funding has further insulated procurement programs from the budget volatility that sometimes affects other defense technology categories, providing suppliers with more predictable multi-year revenue visibility.
Canada contributes additional regional demand through its participation in North American defense procurement and joint military modernization initiatives. Continued Army and Marine Corps procurement of operational high-power microwave systems, alongside growing Navy interest in shipboard directed-energy defense, further reinforces North America's position as the largest regional market, even as international export restrictions on advanced systems have historically limited the technology's availability outside the region. Domestic supplier relationships also continue to shape procurement outcomes across the region, as agencies increasingly favor established defense primes with proven delivery track records over newer entrants still building operational credibility.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Electromagnetic Weapons Market Insights
Asia Pacific region is expected to see the highest CAGR growth rate in the Electromagnetic Weapons Market in the forecast years of 2026 to 2035 owing to increasing military modernization spend in the region and increasing indigenous development of directed energy weapons in the region across several powers. Among the Asian countries, China has been contributing significantly to the market owing to increasing domestic spend in research for railgun and high power microwave in relation to naval modernization aspirations. The research spend on prototypes from large countries in Asia Pacific region is helping in narrowing the gap that exists in terms of technological expertise between the Asian nations and North America / Europe.
Other regions in Asia that have increased demand in electromagnetic weapons are India and South Korea due to the increase in defense research budget and indigenous directed-energy counter drone capability in face of rising security threats in the region. Increased defense budget in Japan for missile and drone defense technology has also contributed to the increasing market growth in the Asia Pacific region.
Europe Electromagnetic Weapons Market Insights
Europe represents a significant regional market for electromagnetic weapons, anchored by France's substantial defense research and development base and its concentration of major developers, including Thales S.A. and MBDA. France's share within the European market reflects both its deep investment in directed-energy research programs and its position as home to several of the continent's leading defense electronics manufacturers supplying NATO member states. Continued NATO-wide standardization efforts around directed-energy weapon interoperability are also gradually easing cross-border technology sharing among member states, a shift that should further support sustained European market development over the coming decade.
The United Kingdom and Germany contribute additional regional demand, supported by growing NATO-wide investment in counter-drone and directed-energy capability amid heightened regional security concerns following recent conflicts in Eastern Europe. Continued European Union defense spending increases, driven by member states' efforts to reduce reliance on non-European suppliers, support steady regional demand for domestically developed electromagnetic weapons technology. Ongoing consolidation among European defense contractors is also reshaping the competitive landscape, as several mid-sized suppliers pursue mergers aimed at achieving the scale needed to compete for large multinational directed-energy procurement contracts.
MEA & Latin America Electromagnetic Weapons Market Insights
The Middle East and Africa region reflects a strategically significant market, with Israel accounting for the largest regional contribution through its established directed-energy research ecosystem and deep experience countering rocket, drone, and asymmetric threats across contested border regions. Gulf Cooperation Council markets contribute additional regional demand through growing investment in critical infrastructure protection and counter-drone capability tied to broader security modernization programs. Growing recognition among regional governments of the strategic value directed-energy systems offer against asymmetric and drone-based threats continues to support gradual, if measured, investment across markets that have historically prioritized conventional defense procurement.
Latin America remains a smaller contributor to global demand, with Brazil accounting for the majority of regional interest on the strength of its growing domestic defense industrial base and rising investment in border security technology. Gradual expansion of regional defense budgets continues to support steady, if modest, market development relative to the more established directed-energy programs underway across North America, Europe, and the Middle East. Regional defense modernization plans across several African nations remain at an early conceptual stage relative to the more advanced programs underway in Israel and the Gulf states, suggesting the broader region's contribution to global demand will likely remain modest through much of the forecast period.
Market Dynamics
Growth Drivers: Drone Proliferation and Non-Kinetic Defense Demand
The rapid proliferation of low-cost unmanned aerial systems and drone swarms represents the principal driver of market growth, as conventional kinetic defenses struggle to counter these threats cost-effectively at the scale modern battlefields increasingly demand. This dynamic is reinforced by rising geopolitical tensions and sustained military modernization spending across major defense powers pursuing precision strike capabilities with minimal collateral damage risk. Growing collaboration between established defense primes and emerging directed-energy technology specialists is also accelerating the pace at which promising prototype systems reach operational fielding, compressing development timelines that historically spanned a decade or more.
Growing integration of artificial intelligence and software-defined weaponeering provides an additional significant source of growth, as these capabilities transform electromagnetic weapons into adaptable, continuously upgradable platforms rather than single-purpose prototypes requiring hardware redesign for each new threat profile. Rising naval demand for shipboard directed-energy defense against missile and drone swarm threats further reinforces this underlying demand trajectory. Sustained multi-year defense appropriations in leading procurement markets are further reducing the funding uncertainty that historically slowed transition from prototype demonstration to program-of-record status for emerging directed-energy technologies.
Restraints: Technical Complexity and Export Restrictions
The substantial technical complexity and capital investment required to develop operationally viable electromagnetic weapons represents a significant restraint, as achieving reliable, repeatable lethality against diverse target types requires years of research and field validation that few organizations possess the resources to sustain. This dynamic continues to limit the number of suppliers capable of competing at the industry's technical frontier. Achieving reliable power generation and thermal management at the scale operational directed-energy systems require also continues to constrain how quickly these technologies can be miniaturized for integration onto smaller vehicle and vessel platforms.
International export restrictions add a further restraint, as several leading supplier nations have historically limited the sale of advanced directed-energy systems to close allies, constraining the addressable international market even where real demand exists. Power generation and thermal management requirements for high-power microwave and laser-based systems also continue to complicate integration onto smaller platforms with limited onboard electrical capacity. Supply chain dependencies on specialized components, including high-power semiconductor switches and precision power electronics, add further complexity for manufacturers seeking to scale production beyond current prototype and low-rate initial production volumes.
Opportunities: International Export Expansion and Naval Integration
The reduction in export limitations among major suppliers of such weapons is a huge growth opportunity since a number of countries have shown an increased interest in the acquisition of directed energy weapons against drones which were not available to them before. Suppliers who have technology already approved and field tested will have the potential to earn more revenue from new international markets through such opportunities that arise due to easing export limitation rules. Defense cooperation pacts between governments will continue to include clauses on the technology transfer of directed energy weapons, thus creating a wider number of potential customers of such technologies.
Another opportunity for suppliers lies in the naval integration of such technologies because of the high amount of power generated by warships compared to other types of platforms where these weapons cannot be used due to the lack of sufficient energy supply. Suppliers who manage to approve the use of their high power microwave and laser weapon systems on ships will find themselves in a very good position to take advantage of the increasing investment by navies in multi-layered drone and missile defense system integration.
Recent Developments:
-
In July 2026, Lockheed Martin unveiled MORFIUS X-Rotor, an airborne high-power microwave counter-drone system designed to engage multiple drones during a single flight. The company is accelerating prototype production and planning additional flight tests for the reusable system.
-
In May 2026, Tonbo Imaging secured an Indian Navy contract under the ADITI 3.0 innovation framework for the integration and commissioning of a high-power microwave system for naval platforms. The development is focused on electromagnetic-energy-based counter-drone capabilities.
-
In November 2025, General Atomics Electromagnetic Systems unveiled a truck-mounted electromagnetic railgun concept, featuring a containerized architecture designed for deployment on standard tactical vehicles. The system incorporates high-energy pulsed-power technology and is intended for applications including air and missile defense.
-
In April 2025, Epirus unveiled Leonidas H2O, a high-power microwave system developed specifically for maritime environments. The company demonstrated the system's ability to disrupt electronic systems associated with manned and unmanned vessels, expanding HPM applications beyond conventional counter-drone roles.
-
In January 2026, Rheinmetall and MBDA announced plans to establish a joint venture for laser weapon systems, building on their previously tested naval laser demonstrator. The companies are developing the technology initially for naval applications, with potential expansion to land-based systems.
Electromagnetic Weapons Market Key Players
-
RTX Corporation
-
Thales S.A.
-
The Boeing Company
-
Lockheed Martin Corporation
-
BAE Systems plc
-
Northrop Grumman Corporation
-
L3Harris Technologies, Inc.
-
General Dynamics Corporation
-
Leonardo S.p.A.
-
Rafael Advanced Defense Systems Ltd.
-
Israel Aerospace Industries Ltd.
-
Elbit Systems Ltd.
-
Diehl Defence GmbH & Co. KG
-
MBDA
-
QinetiQ Group plc
-
Epirus, Inc.
-
Leidos Holdings, Inc.
-
Rheinmetall AG
-
Kord Technologies
-
Raytheon Technologies (RTX)
Electromagnetic Weapons Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.00 Billion |
| Market Size by 2035 | USD 7.20 Billion |
| CAGR | CAGR of 21.80% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product (Lethal Weapons, Non-Lethal Weapons) • by Technology (High Laser-Induced Plasma Channel, Particle Beam Weapons, Electromagnetic Railgun, High-Powered Microwave, Electromagnetic Pulse) • by Platform (Land-Based, Air-Based, Naval) • by Application (Military, Homeland Security, Research & Development, Commercial) • by End-User (Military, Law Enforcement, Civilian) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | RTX Corporation, Thales S.A., The Boeing Company, Lockheed Martin Corporation, BAE Systems plc, Northrop Grumman Corporation, L3Harris Technologies, Inc., General Dynamics Corporation, Leonardo S.p.A., Rafael Advanced Defense Systems Ltd., Israel Aerospace Industries Ltd., Elbit Systems Ltd., Diehl Defence GmbH & Co. KG, MBDA, QinetiQ Group plc, Epirus, Inc., Leidos Holdings, Inc., Rheinmetall AG, Kord Technologies, Raytheon Technologies (RTX) |

Frequently Asked Questions
Key players include RTX Corporation, Thales S.A., The Boeing Company, Lockheed Martin Corporation, BAE Systems plc, and Epirus, Inc., among other leading defense technology manufacturers.
Easing international export restrictions and expanding naval integration of directed-energy systems represent the primary opportunities.
Growth is primarily driven by the rapid proliferation of low-cost unmanned aerial systems and drone swarms combined with rising demand for non-kinetic defense capabilities.
By Product, Lethal Weapons dominated the market with approximately 67.40% share in 2025, reflecting defense agencies' prioritization of systems capable of permanently neutralizing high-value targets.
North America dominated the market with approximately 43.90% share in 2025, supported by sustained U.S. Department of Defense investment in directed-energy counter-drone systems.
