
Unmanned Surface Vehicle Market Report Scope & Overview:
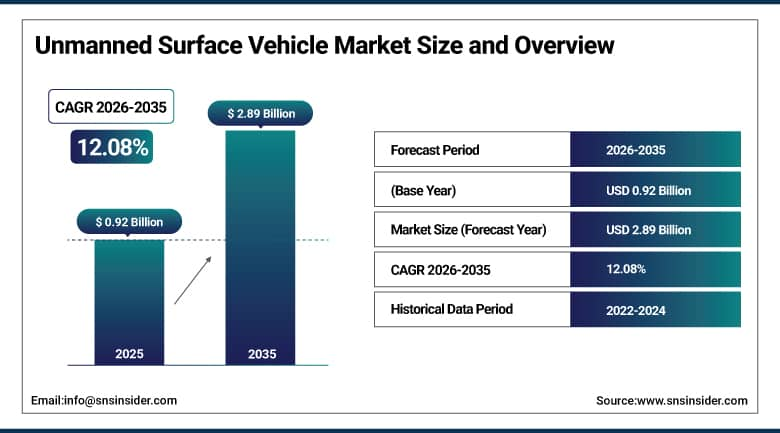
The Unmanned Surface Vehicle Market was valued at USD 0.92 Billion in 2025 and is expected to reach USD 2.89 Billion by 2035, growing at a CAGR of 12.08% from 2026-2035.
Unmanned surface vehicles, also known as autonomous surface vessels or maritime drones, are moving from experimental platforms into mission-critical maritime systems across defense, offshore energy, ocean science, port operations, hydrographic survey, environmental monitoring, and maritime security. These vehicles enable persistent maritime presence without placing crew members in harm's way, supporting missions ranging from naval mine countermeasures and intelligence, surveillance, and reconnaissance to long-endurance oceanographic data collection and uninhabited waters survey work. The market continues to expand rapidly, driven by growing demand for ocean data mapping, rising naval modernization programs, increasing offshore oil and gas investment, and expanding maritime surveillance and security requirements worldwide. Autonomous navigation technology continues to remove the bandwidth, latency, and operator workload constraints associated with continuous remote operation, enabling deployment of unmanned surface vehicles in beyond-line-of-sight missions lasting days to weeks without continuous human steering input.
In October 2025, Lockheed Martin announced a USD 50 million investment in Saildrone to advance unmanned surface vehicle capabilities for the U.S. Navy. The strategic collaboration combines Saildrone's experience operating unmanned vessels in complex maritime environments with Lockheed Martin's expertise in weapons, sensors, combat systems, and mission integration, with the companies working toward on-water, live-fire integration demonstrations targeted for 2026, reinforcing the broader industry trend of established defense contractors partnering with commercial maritime autonomy specialists to accelerate fielding of combat-relevant unmanned surface capability.
To Get More Information On Unmanned Surface Vehicle Market - Request Free Sample Report
Unmanned Surface Vehicle Market Trends
-
Rising integration of autonomous navigation technology enabling extended beyond-line-of-sight maritime missions.
-
Growing adoption of electric and solar-powered propulsion systems offering fuel-free operational endurance advantages.
-
Expanding deployment of medium-class platforms bridging capability gaps between small survey craft and large naval vessels.
-
Increasing collaboration between commercial maritime autonomy companies and established defense contractors.
-
Rising investment in naval modernization programs incorporating unmanned surface vessels for mine countermeasures and ISR.
-
Growing utilization of unmanned surface vehicles supporting offshore renewable energy inspection and maintenance operations.
U.S. Unmanned Surface Vehicle Market Outlook
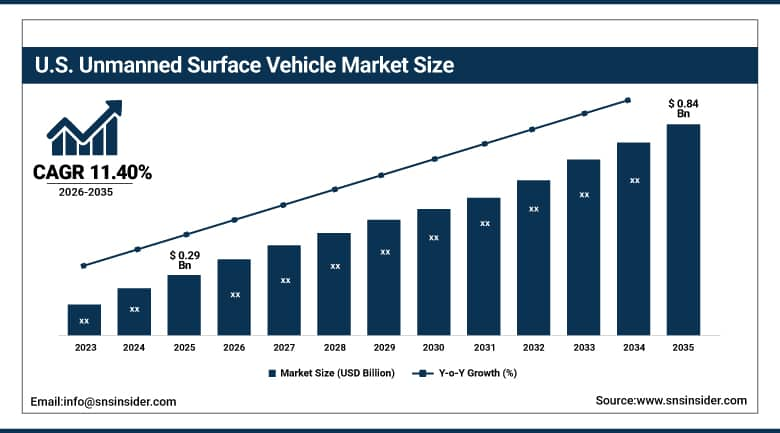
The U.S. Unmanned Surface Vehicle Market was valued at USD 0.29 Billion in 2025 and is expected to reach USD 0.84 Billion by 2035, growing at a CAGR of 11.40% from 2026-2035.
The U.S. Unmanned Surface Vehicle Market is expected to continue being driven by significant military expenditure, innovation, and continued need for maritime surveillance. The region’s strength in manufacturing ships on a global scale, combined with investments in modernizing the navy, energy development offshore, and unmanned maritime technology, continue to ensure continued domestic demand for unmanned surface vehicles. Significant military expenditure and investment from the National Oceanic and Atmospheric Administration continue to ensure that the domestic market remains a leader, backed by continuing military expenditure that will support more unmanned surface vehicle manufacturers.
In August 2025, the U.S. Navy moved to buy autonomous maritime drones from Saronic through a USD 392 million Other Transaction Authority award, with the Texas-based defense company set to produce multiple batches of autonomous surface vessels for the Navy through mid-2031. This substantial procurement commitment illustrates the scale of domestic naval investment flowing toward emerging unmanned surface vehicle manufacturers, reinforcing how the U.S. Navy continues to expand its supplier base beyond traditional defense primes to include venture-backed maritime autonomy specialists capable of delivering production volume at competitive cost and schedule.
Unmanned Surface Vehicle Market Segment Analysis
-
By Size, the Large segment dominated the Unmanned Surface Vehicle Market with approximately 44.60% share in 2025, while the Medium segment is the fastest growing with a CAGR of approximately 13.60%.
-
By Type, the Autonomous Surface Vehicle segment dominated the Unmanned Surface Vehicle Market with approximately 42.60% share in 2025, and is also the fastest growing with a CAGR of approximately 15.20%.
-
By Application, the Defense & Military segment dominated the Unmanned Surface Vehicle Market with approximately 52.60% share in 2025, and is also the fastest growing with a CAGR of approximately 14.60%.
-
By Propulsion, the Diesel segment dominated the Unmanned Surface Vehicle Market with approximately 48.60% share in 2025, while the Electric/Solar segment is the fastest growing with a CAGR of approximately 18.60%.
By Size, Large Dominates the Unmanned Surface Vehicle Market and Medium Grows Fastest
Large unmanned surface vehicles hold the largest size category share, offering the payload capacity and operational endurance required for extended defense and commercial missions spanning intelligence gathering, mine countermeasures, and long-duration oceanographic research. The scale and capability these platforms provide continues to sustain their position as the largest size category across both defense and commercial procurement programs.
Medium-class platforms represent the fastest-growing size category, bridging mission gaps by supporting heavier payloads than small craft while retaining manageable logistics footprints suitable for commercial survey firms and moderately resourced defense programs. This balance between capability and operational practicality continues to position medium-class unmanned surface vehicles for sustained above-market growth as both commercial and defense customers increasingly seek cost-effective platforms suited to a broad range of mission profiles.
By Type, Autonomous Surface Vehicle Dominates the Unmanned Surface Vehicle Market and Also Grows Fastest
Autonomous surface vehicles hold the largest share of the market, as autonomous navigation removes the bandwidth, latency, and operator workload constraints of continuous remote operation, enabling deployment in beyond-line-of-sight missions lasting days to weeks without continuous human steering input. This capability continues to prove essential for persistent ocean surveillance, long-endurance oceanographic data collection, and uninhabited waters survey missions, sustaining this type's position as the largest category within the broader unmanned surface vehicle market.
Autonomous surface vehicles are also the fastest-growing type, as continued advancement in artificial intelligence and autonomy software continues to expand the range of missions these platforms can reliably execute without continuous human oversight. This combination of already-substantial market share and continued above-average growth reflects sustained industry and defense investment in reducing operator workload while extending mission endurance across increasingly demanding maritime operating environments.
By Application, Defense & Military Dominates the Unmanned Surface Vehicle Market and Also Grows Fastest
Defense and military applications account for the largest share of applications due to the increasing need for intelligence, surveillance, and reconnaissance in addition to the ongoing demand for naval mine countermeasures. Defense and military applications remain the leading application category for USVs thanks to the continued growth in the number of naval modernization projects among leading maritime nations.
Defense and military applications remain the fastest-growing category, with growing investment in naval modernization and concerns regarding maritime security pushing governments towards increased procurement activities. This is in view of the fact that defense budgets give priority to USVs which are capable of increasing naval capabilities while reducing exposure to harsh environments for crews.
By Propulsion, Diesel Dominates the Unmanned Surface Vehicle Market and Electric/Solar Grows Fastest
Diesel propulsion has the biggest share by propulsion type, providing well-proven, reliable power that is ideal for extended-range operations and needs a lot of operational endurance in difficult maritime conditions. The already proven reliability and logistical support infrastructure of this technology ensure that diesel propulsion will remain the biggest propulsion category for the unmanned surface vehicles industry in the future.
Electric and solar propulsion systems are the fastest growing propulsion categories, providing real fuel-free endurance capabilities that keep attracting more and more customers. This is especially relevant to oceanographic and environmental research operations where fuel-free endurance and low emissions make sense from both an operational and reputational point of view.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
39.60% |
|
Europe |
Germany |
29.60% |
|
Middle East & Africa |
United Arab Emirates |
27.60% |
|
Latin America |
Brazil |
24.60% |
North America Unmanned Surface Vehicle Market Insights
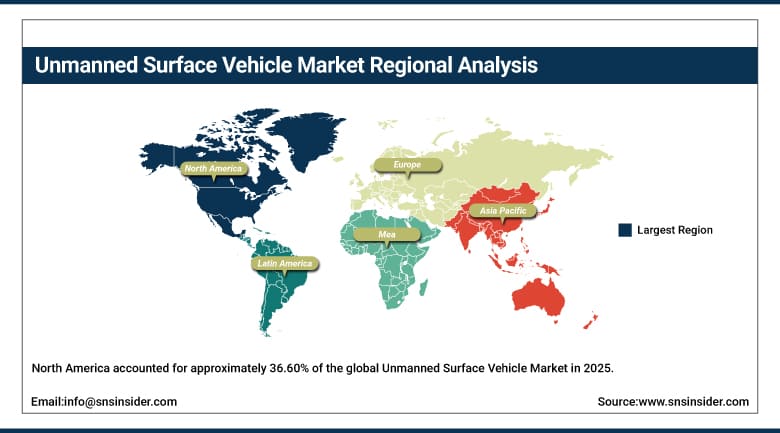
North America accounted for approximately 36.60% of the global Unmanned Surface Vehicle Market in 2025, making it the largest regional market, supported by substantial U.S. defense spending and National Oceanic and Atmospheric Administration investment in maritime autonomy technology. The region's dominance in global ship production, coupled with increasing investment in naval modernization and offshore energy projects, continues to reinforce North America's position as the largest source of global unmanned surface vehicle demand.
Canada is contributing incremental regional demand as its own naval modernization and maritime research programs continue to develop. Continued domestic investment in autonomous maritime technology and expanding defense procurement activity is expected to sustain North America's leading position through the forecast period, even as growth in percentage terms moderates relative to faster-expanding emerging markets.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Unmanned Surface Vehicle Market Insights
Asia Pacific is the fastest-growing market region on account of increasing naval modernization initiatives, increased maritime security threats, and offshore energy investment in China and other leading maritime powers in the region. Continued growth in naval capacity and home-grown maritime technologies in China have played a major role in fueling the demand for unmanned surface vehicles in the region.
Defense electronics in South Korea and Japan have also added weight to the region on account of the incorporation of unmanned surface vehicle technology in their naval modernization initiatives. The continued naval capability development in India has played an important role in driving growth in the region over the forecast period.
Europe Unmanned Surface Vehicle Market Insights
Europe represents a significant share of the global Unmanned Surface Vehicle Market, with regional demand reinforced by sustained defense modernization investment amid an evolving European security environment. The United Kingdom's continued research and development activity, exemplified by ongoing autonomous surface vessel testbed programs, continues to support the region's technological leadership in maritime autonomy.
Germany, France, and other major European defense markets contribute steady regional demand as national naval modernization programs continue to extend unmanned surface vehicle adoption across mine countermeasures and surveillance applications. Regional defense contractors continue investing in autonomous maritime technology to meet evolving NATO interoperability requirements.
MEA & Latin America Unmanned Surface Vehicle Market Insights
The Middle East & Africa market will be driven by steady maritime security and offshore energy industry investments in the United Arab Emirates and Saudi Arabia. The regional governments are continually focusing on the purchase of cutting-edge maritime technology as part of their military capabilities strategy. The market demand is growing as offshore oil and gas investments increase.
Latin America’s market will be relatively small due to the gradual progress made in the regional navies’ modernization and offshore energy industry. There are continued evaluations of unmanned surface vehicle technology investments as part of the region’s maritime security and offshore energy industry monitoring capabilities.
Market Dynamics
Growth Drivers: Naval Modernization Programs and Maritime Surveillance Demand
Growing demand for ocean data mapping and rising naval modernization programs represent the primary driver of Unmanned Surface Vehicle Market growth, as maritime security threats and defense procurement activity continue to expand across both established and emerging naval powers. Increasing adoption across commercial and military operations continues to reinforce sustained demand for platforms capable of extending maritime presence while reducing crew exposure to hazardous operating environments.
Increasing offshore oil and gas investment represents a second major growth driver, as energy companies continue to seek cost-effective alternatives to traditional crewed survey and inspection vessels for offshore infrastructure monitoring. Rising water quality monitoring and environmental conservation requirements continue to reinforce sustained demand across commercial and scientific research applications beyond the market's traditional defense foundation.
Restraints: Regulatory Complexity and High Platform Development Costs
Regulatory complexity represents a meaningful restraint on market growth, as the integration of unmanned surface vehicles into commercial and defense maritime operations continues to require navigation of evolving maritime safety regulations and jurisdiction-specific operating requirements that can constrain the pace of commercial deployment, particularly for platforms operating in congested or international waters.
High platform development costs represent a further restraint, as advanced autonomy systems, sensor integration, and ruggedized hull construction continue to command substantial development investment that can be genuinely difficult for smaller manufacturers and commercial operators to justify without sustained government or defense contract support.
Opportunities: Commercial-Defense Technology Integration and Electric Propulsion Innovation
Continued integration of commercial maritime autonomy technology with established defense capability represents a substantial opportunity, as manufacturers that can successfully combine proven commercial platform reliability with combat-relevant sensor and weapons integration are positioned to capture demand from naval customers seeking rapid capability fielding at reduced development cost and timeline.
The continued advancement of electric and solar propulsion technology offers a further avenue for growth, as manufacturers that can deliver genuinely extended fuel-free operational endurance are positioned to capture demand from both commercial and defense customers increasingly prioritizing minimized logistics footprint and environmental impact across long-duration maritime missions.
Recent Developments:
-
In May 2025, Textron Systems confirmed its first Tsunami unmanned surface vehicle sale to the U.S. Navy, delivering a 24-foot configuration to the Naval Surface Warfare Center Dahlgren Division in Virginia. The vessel is powered by Textron's in-house Common Unmanned Surface Vehicle autonomy suite and offers a range exceeding 1,000 nautical miles.
-
In May 2026, Textron Systems secured a contract from the Defense Innovation Unit to produce and deliver uncrewed surface vessels for the U.S. Navy. The agreement supports fleet experimentation exercises in Key West and joint operations with U.S. Southern Command and the Navy's Fourth Fleet.
-
DeepOcean chartered a new-built unmanned surface vessel with a hybrid diesel-electric propulsion system from USV AS, with delivery expected by the end of 2025. The vessel is capable of operating offshore for up to 30 days without refueling and is expected to support subsea inspection, maintenance, repair, and survey work across offshore renewables and oil and gas operations.
Unmanned Surface Vehicle Market Key Players
-
Kongsberg Maritime AS
-
BAE Systems plc
-
ECA GROUPE
-
Elbit Systems Ltd.
-
Fugro N.V.
-
L3Harris Technologies, Inc.
-
Liquid Robotics, Inc. (Boeing)
-
Maritime Robotics AS
-
OceanAlpha Group Ltd.
-
Saab AB
-
Sagar Defence Engineering
-
Teledyne Technologies Inc.
-
Textron Systems Corporation
-
Thales Group
-
Saildrone, Inc.
-
MARTAC Systems, Inc.
-
Saronic Technologies, Inc.
-
ASV Global (L3Harris)
-
ST Engineering
-
5G International Inc.
Unmanned Surface Vehicle Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.92 Billion |
| Market Size by 2035 | USD 2.89 Billion |
| CAGR | CAGR of 12.08% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Type (Autonomous Surface Vehicle, Remotely Operated Surface Vehicle, and Semi-Autonomous) • by Application (Defense & Military, Oceanographic Research, Hydrographic Survey, and Environmental Monitoring) • by Size (Small, Medium, and Large) • by Propulsion (Diesel, Hybrid, and Electric/Solar) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Boston Scientific Corporation, Medtronic plc, Olympus Corporation, CONMED Corporation, Abbott Laboratories, Cook Medical LLC, Taewoong Medical Co., Ltd., ENDO-FLEX GmbH, ELLA-CS, s.r.o., Becton, Dickinson and Company, W. L. Gore & Associates, Inc., Merit Medical Systems, Inc., Micro-Tech Endoscopy, M.I.Tech Co., Ltd., Fujifilm Holdings Corporation, Standard SciTech Inc., Hobbs Medical, Inc., Gadelius Medical K.K., CGBIO Co., Ltd., Medorah Meditek Pvt. Ltd. |
Frequently Asked Questions
Key players include Kongsberg Maritime AS, BAE Systems plc, L3Harris Technologies, Inc., Textron Systems Corporation, Thales Group, Saildrone, Inc., and Saronic Technologies, Inc., among other maritime autonomy and defense contractors.
Continued integration of commercial maritime autonomy technology with established defense capability and continued advancement of electric and solar propulsion technology represent the primary opportunities.
Growth is primarily driven by growing demand for ocean data mapping and rising naval modernization programs combined with increasing offshore oil and gas investment.
By Application, Defense & Military dominated the market with approximately 52.60% share in 2025, driven by sustained intelligence, surveillance, and reconnaissance procurement activity worldwide.
North America dominated the market with approximately 36.60% share in 2025, supported by substantial U.S. defense spending and National Oceanic and Atmospheric Administration investment.
