
Aerospace Fasteners Market Report Scope & Overview:
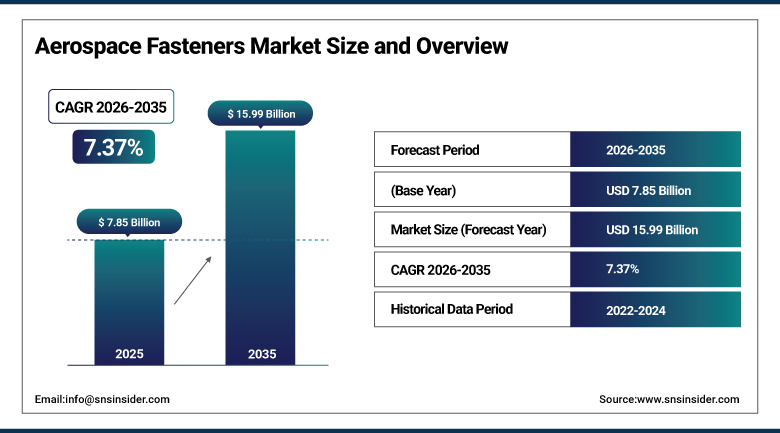
The Aerospace Fasteners Market was valued at USD 7.85 Billion in 2025 and is expected to reach USD 15.99 Billion by 2035, growing at a CAGR of 7.37% from 2026 to 2035.
The aerospace fasteners market is expanding rapidly due to increased production of aircraft and continued expansion of commercial aviation and defense modernization programs. The aerospace fasteners comprise bolts, nuts, screws, rivets, and pins which play an important role in assembly of airframes, engines, and interior assemblies of the aircraft ensuring structural integrity and safety, while possessing favorable characteristics such as adaptability to corrosion, pressure changes, and high temperature. Moreover, market growth is driven by record backlogs of single-aisle jets over 14,000 aircraft on both Boeing and Airbus' books, compelling OEMs to speed up assembly line operations, higher composite airframe content demanding special fastening solutions, and emerging urban air mobility and commercial space launch sectors adding new high growth fastener categories.
Boeing's long-term forecast projects demand for approximately 4,000 new airplanes by 2043, creating a multi-decade pipeline of fastener demand at assembly plants and aftermarket facilities, with commercial aviation accounting for the majority of global aerospace fasteners revenue amid sustained record order backlogs and rebounding passenger traffic worldwide.
To Get more information Aerospace Fasteners Market - Request Free Sample Report
Aerospace Fasteners Market Trends
- Rising Advanced Air Mobility and eVTOL commercialization is requiring novel fastener specifications, as composite-compatible, lightweight, vibration-resistant fasteners are needed in large volumes per airframe.
- Growing hydrogen aircraft programs are demanding embrittlement-resistant fasteners, creating new material science requirements as next-generation propulsion technology enters commercial development.
- Increasing space launch market growth is driving demand for cryogenic-rated precision fastener solutions, as commercial launch frequency approaches one per day globally across rocket stages and satellite structures.
- Expanding composite airframe content across next-generation commercial and defense aircraft is accelerating adoption of composite-compatible polymer fasteners suited to modern lightweight structural applications.
- Strategic partnerships among fastener manufacturers, aircraft OEMs, and MRO providers are supporting development of increasingly diverse, application-specific fastening solutions.
The U.S. Aerospace Fasteners Market Outlook
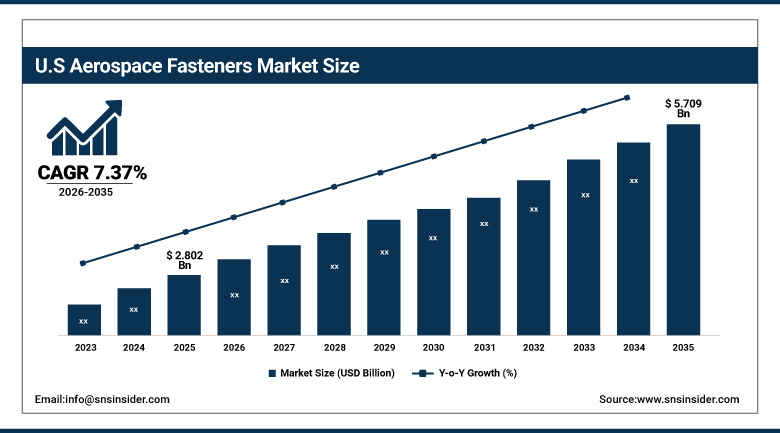
The U.S. aerospace fasteners market was valued at USD 2.80 Billion in 2025 and is projected to reach USD 5.70 Billion by 2035, growing at a CAGR of 7.37% during 2026–2035.
Leading manufacturers in the fastener industry in this nation keep on increasing their production capacity because of the high backlog of single aisle jets in Boeing, which results in speeding up of the production line. Modernization and procurement of military aircraft along with demand for maintenance and overhaul in the commercial sector result in the constant demand for fasteners in the aerospace industry in this nation.
In 2025, the U.S. aerospace fasteners market continued to benefit from Boeing and other aerospace manufacturers increasing aircraft production, while rising defense aircraft procurement and fleet modernization supported demand for high-performance fasteners. Strong MRO activity across the large U.S. commercial aircraft fleet further increased replacement demand for certified aerospace fastening components.
Aerospace Fasteners Market Segment Analysis
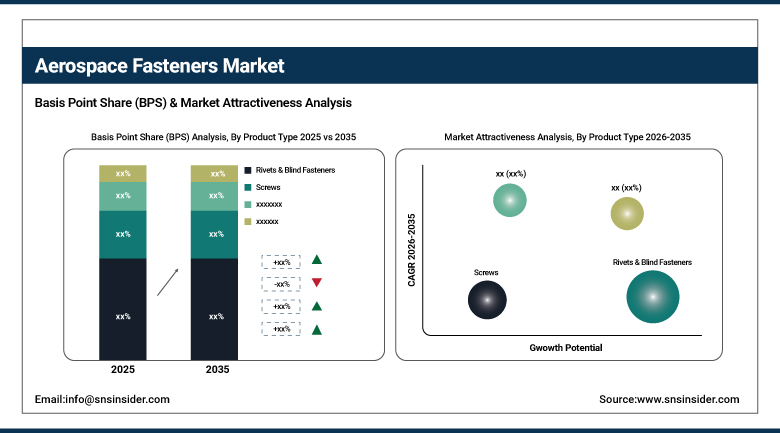
- By Product Type, rivets & blind fasteners dominated the aerospace fasteners market with a 38.40% share in 2025, while screws is the fastest-growing product type segment with a CAGR of 8.20% from 2026–2035.
- By Material, titanium alloy dominated the aerospace fasteners market with a 42.30% share in 2025, while composite-compatible polymer is the fastest-growing material segment with a CAGR of 9.60% from 2026–2035.
- By Application, commercial aircraft dominated the aerospace fasteners market with a 55.90% share in 2025, while military aircraft is the fastest-growing application segment with a CAGR of 8.70% from 2026–2035.
- By End-Use, OEM dominated the aerospace fasteners market with a 68.60% share in 2025, while aftermarket/MRO is the fastest-growing end-use segment with a CAGR of 8.40% from 2026–2035.
By Product Type, rivets & blind fasteners dominated the aerospace fasteners market, while screws is the fastest-growing segment.
By product, rivets occupy first place, holding a market share of 38.40%. Rivets continue to hold first place as the leading product category because of the widespread application of these fasteners in assembling airplanes, as these fasteners are used in assembling aircraft fuselage, wings, and control surfaces by forming lightweight joints that do not come apart easily and can withstand vibrations.
The screws product category will grow very quickly over the next ten years, showing the highest CAGR of 8.20% during the forecast period 2026-2035. The increase in the popularity of screws is due to the increasing need for removable fastening solutions, where the precision in applying torque matters a lot.
By Material, titanium alloy dominated the aerospace fasteners market, while composite-compatible polymer is the fastest-growing segment.
By material, titanium accounts for 42.30% market share. Titanium alloy fasteners continue to be the most prevalent type of fasteners based on their high-strength-to-weight ratio, durability, and performance at high temperatures due to the use of composite airframes, advanced requirements of aircraft structures in next generation aircrafts, and modernization efforts in defense platforms favoring titanium.
Polymer fasteners for composite applications are the fastest-growing type of fasteners growing at a CAGR of 9.60%, consistent with the increased use of carbon fiber reinforced polymers in next generation aircrafts. The growing need for composite-friendly, lightweight, and vibration-resistant fasteners in next generation airframe construction for urban air mobility is responsible for their fast growth.
By Application, commercial aircraft dominated the aerospace fasteners market, while military aircraft is the fastest-growing segment.
Commercial aviation accounted for 55.90% of the aerospace fasteners market revenue in 2025. Commercial aircraft still account for the leading application category, supported by consistent record levels of order backlog at Boeing and Airbus, as well as recovery of passenger numbers, thus being the largest and the most mature application category that drives aerospace fastener market demand globally.
The segment of end-users related to the military sector accounts for the fastest CAGR of 8.70% within 2026-2035 due to the development of the sixth-generation fighters and advanced trainer aircraft. Increasing global military budget, air fleet modernization, and the creation of advanced fighters and transports continue to support the segment growth in the market for military aircraft fasteners since fighters, helicopters, and transports are the most fastened types of aviation craft.
By End-Use, OEM dominated the aerospace fasteners market, while aftermarket/MRO is the fastest-growing segment.
The OEM segment dominated the aerospace fasteners market, reflecting OEM production-linked demand with strong multi-year visibility. OEM fastener procurement remains the dominant end-use category owing to sustained new aircraft production driven by record commercial and defense backlogs, representing the primary fastener procurement channel across the majority of aircraft assembly programs worldwide.
The aftermarket/MRO segment is expected to register the fastest CAGR of 8.40% during the forecast period 2026-2035. The robust aftermarket for maintenance, repair, and overhaul in the commercial sector further contributes to consistent fastener demand, especially for replacement and upgrade purposes, as an aging global fleet continues requiring sustained fastener replacement and structural maintenance activity.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
China |
44.60% |
|
Middle East & Africa |
UAE |
25.60% |
|
Latin America |
Brazil |
37.70% |
North America Aerospace Fasteners Market Insights
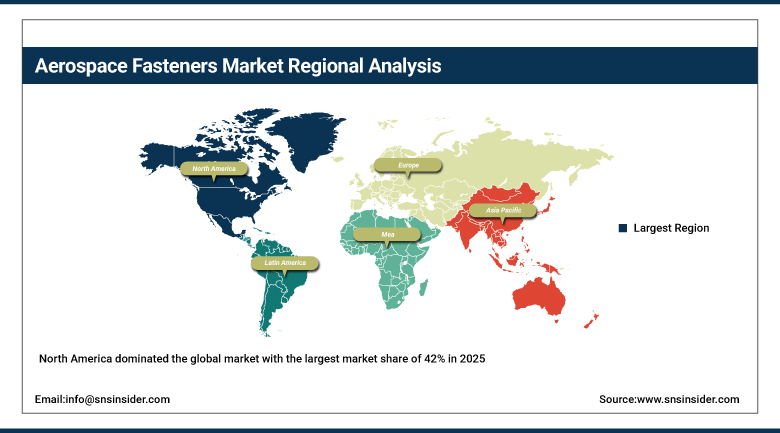
North America dominated the global market with the largest market share of 42% in 2025, driven by record single-aisle jet backlogs, robust defense modernization investment, and substantial domestic fastener manufacturing infrastructure across the region.
In 2025, the US will be the dominant nation in the North America aerospace fasteners market, propelling the growth of the global market by 7.5% CAGR due to OEM-driven aerospace manufacturing and enhancements in the existing fleet. Canada’s growth is also being fueled by its aerospace manufacturing industry and manufacture of aircraft components.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Aerospace Fasteners Market Insights
The Europe aerospace fasteners market was a major contributor in 2025. This is attributed to the region's substantial commercial aircraft manufacturing base led by Airbus, strong presence of leading fastener manufacturers, and sustained NATO-aligned defense modernization investment across member states.
Germany records a 6.8% CAGR, reflecting steady adoption in a mature aerospace sector. Other countries such as France, home to LISI Aerospace and Airbus's primary manufacturing operations, and the United Kingdom, posting a 6.5% CAGR, are also contributing to market growth through extensive fastener manufacturing capacity.
Asia Pacific Aerospace Fasteners Market Insights
Asia-Pacific is set to grow the fastest at a 9.70% CAGR over the forecast period. The market growth is driven by BRICS-focused expansion in commercial and defense aircraft manufacturing and strengthening domestic supply chains across the region's major and emerging economies.
China follows at a 7.3% CAGR, +4% higher than the global benchmark, supported by expanding commercial and defense aircraft manufacturing capacity and strengthening domestic supply chains. India and Japan are also contributing to regional growth through expanding aerospace manufacturing capability and rising demand for precision fastening solutions.
Middle East & Africa and Latin America Aerospace Fasteners Market Insights
Middle East & Africa and Latin American regions are gradually expanding aerospace fasteners market participation as commercial and defense aviation manufacturing investment grows across both regions.
The future market of Brazil is going to be an important one from the Latin American point of view because of the high production ability of Embraer for commercial and business aircraft. In terms of the Middle East & Africa segment, both the UAE and Saudi Arabia have plans for expanding their aviation and MRO facilities.
Market Dynamics
Growth Drivers: Rising aircraft production and defense modernization driving market growth
Rising aircraft production, increasing demand for lightweight and high-performance materials, and continuous growth in commercial aviation and defense modernization programs are among the primary drivers of the aerospace fasteners market. Record single-aisle jet backlogs exceeding 14,000 aircraft at Boeing and Airbus combined have forced OEMs to accelerate assembly-line throughput, driving unprecedented demand for fastening hardware across the global aviation supply chain.
The sustained increase in commercial aircraft production rates, driven by record order backlogs and rebounding passenger traffic post-COVID, continues to serve as a foundational demand driver. Rising global focus on defense modernization and military aircraft procurement, ideal features of hardware components such as better adaptability to corrosion, pressure fluctuations, and extreme temperatures, and expanding urban air mobility and commercial space launch activity are further supporting demand across the forecast period.
Restraints: Raw material cost volatility and stringent certification requirements limiting market expansion
Another important factor that poses as a limitation towards market growth is the instability of the titanium and specialized alloys used in manufacturing of fasteners. This results in uncertainty of costs for the producers trying to sign a contract for supply for a long time with aircraft Original Equipment Manufacturers (OEMs).
Also, the strict certification procedures of aerospace fasteners limit the speed of development of new designs. The technical complexity of developing embrittlement-resistant fasteners for emerging hydrogen aircraft programs and cryogenic-rated fasteners for space launch applications further requires substantial ongoing research and development investment.
Opportunities: Expansion of eVTOL platforms and space launch activity creating new growth avenues
Urban air mobility and the commercial space launch segment are creating two new high-growth fastener categories expanding the market beyond traditional aviation, as eVTOL aircraft require composite-compatible, lightweight, vibration-resistant fasteners in large volumes per airframe.
There is a considerable growth opportunity in the continued development of cryogenic-rated fasteners capable of surviving extreme temperatures and high dynamic loads across rocket stages and satellite structures. The expansion of defense modernization programs and commercial aircraft manufacturing capacity in emerging markets across Asia Pacific is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
- 2025: Howmet Aerospace expanded its titanium fastener production capacity, strengthening its ability to supply growing commercial aircraft OEM customer demand for high-performance, corrosion-resistant fastening solutions.
- 2025: LISI Aerospace launched an updated composite-compatible fastener product line designed for eVTOL applications, offering urban air mobility manufacturers lightweight, vibration-resistant fastening solutions.
- 2026: Precision Castparts Corp expanded its specialty fastener manufacturing facility, strengthening its ability to supply growing defense aircraft platform demand for advanced fighter and transport aircraft programs.
- 2026: TriMas Corporation launched a new cryogenic-rated fastener solution designed for space launch applications, targeting manufacturers seeking fasteners capable of surviving extreme temperatures across rocket and satellite structures.
Aerospace Fasteners Market key players are:
- Howmet Aerospace Inc.
- Precision Castparts Corp. (Berkshire Hathaway)
- LISI Aerospace
- Stanley Black & Decker, Inc.
- TriMas Corporation
- National Aerospace Fasteners Corporation
- B&B Specialties Inc.
- SAT Aerospace
- Arconic Corporation
- TFI Aerospace Corporation
- Würth Group
- M.S. Aerospace
- TPS Aviation Inc.
- Bollhoff Group
- Monogram Aerospace Fasteners
- SPS Technologies (Fairchild Fasteners)
- Kaman Aerospace Corporation
- MW Industries, Inc.
- 3V Fasteners Company Inc.
- Acumen Global Technologies
Aerospace Fasteners Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 7.85 Billion |
| Market Size by 2035 | USD 15.99 Billion |
| CAGR | CAGR of 7.37% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Rivets & Blind Fasteners, Screws, Bolts & Nuts, Pins & Inserts) • By Material (Titanium Alloy, Aluminum Alloy, Steel & Superalloy, Composite-Compatible Polymer, Others) • By Application (Commercial Aircraft, Military Aircraft, UAV/eVTOL) • By End-Use (OEM, Aftermarket/MRO) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Howmet Aerospace Inc., Precision Castparts Corp. (Berkshire Hathaway), LISI Aerospace, Stanley Black & Decker, Inc., TriMas Corporation, National Aerospace Fasteners Corporation, B&B Specialties Inc., SAT Aerospace, Arconic Corporation, TFI Aerospace Corporation, Würth Group, M.S. Aerospace, TPS Aviation Inc., Bollhoff Group, Monogram Aerospace Fasteners, SPS Technologies (Fairchild Fasteners), Kaman Aerospace Corporation, MW Industries, Inc., 3V Fasteners Company Inc., Acumen Global Technologies. |
Frequently Asked Questions
Key players in the Aerospace Fasteners Market include Howmet Aerospace Inc., LISI Aerospace, Precision Castparts Corp., TriMas Corporation, and Stanley Black & Decker, Inc., among others.
Key opportunities in the Aerospace Fasteners Market include eVTOL commercialization, composite aircraft adoption, hydrogen aircraft development, space-launch activity, and increasing commercial and defense aircraft production.
The market is driven by rising aircraft production, increasing demand for lightweight and high-performance materials, and continuous growth in commercial aviation and defense modernization programs.
The Rivets & Blind Fasteners segment dominated the Aerospace Fasteners Market, accounting for approximately 38.40% market share.
The North America region dominated the Aerospace Fasteners Market in 2025 with the largest market share of 42%.
