
Electronic Adhesives Market Report Scope & Overview:
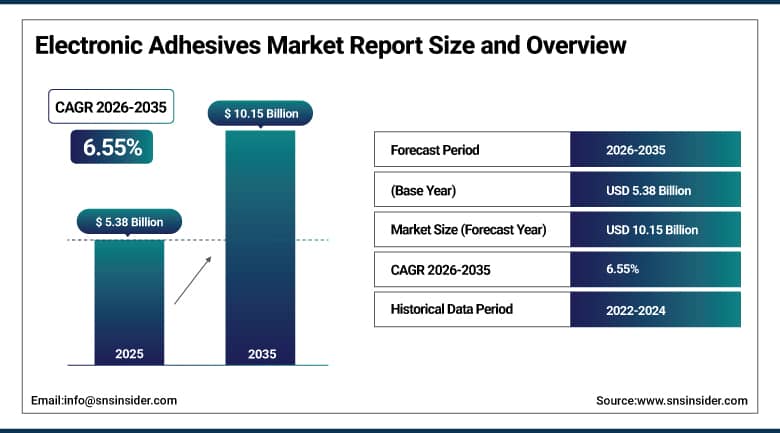
The Electronic Adhesives Market size was valued at USD 5.38 Billion in 2025 and is expected to reach USD 10.15 Billion by 2035, growing at a CAGR of 6.55% from 2026-2035.
The Electronic Adhesives Market is growing owing to rising demand for miniaturized, high performance, and robust electronic components in consumer electronics, automotive, telecommunication, and industrial sectors. Fast adoption of smartphones, wearables, IoT devices, electric cars, and advanced computing systems is creating more requirements for adhesives with features of strong bonding, heat resistance, electrical insulation, and protection against environmental conditions. Further, the rise in 5G technology and automotive electronics is adding to the growth of demand for electronic adhesives in circuit boards, sensors, display panels, and semiconductor packages. Also, rising production and packaging of semiconductors is contributing to the consumption of adhesives.
⮞In July 2026, Dymax launched its 9310 light-curable adhesive engineered to reinforce fine-pitch, leadless components on printed circuit boards. The company stated the product cures within seconds under light exposure, offering a faster alternative to traditional underfill for advanced electronics and AI hardware assembly.
To Get More Information On Electronic Adhesives Market - Request Free Sample Report
Electronic Adhesives Market Trends
- Rising adoption of UV-curable adhesives improving manufacturing throughput for precision electronic assemblies.
- Growing demand for thermally conductive adhesives supporting heat management in compact device designs.
- Expanding use of conductive adhesives as manufacturers seek alternatives to traditional soldering methods.
- Increasing formulation focus on low-outgassing materials suited to sensitive semiconductor packaging.
- Rising integration of adhesive bonding in electric vehicle battery and power electronics assembly.
U.S. Electronic Adhesives Market Size Outlook
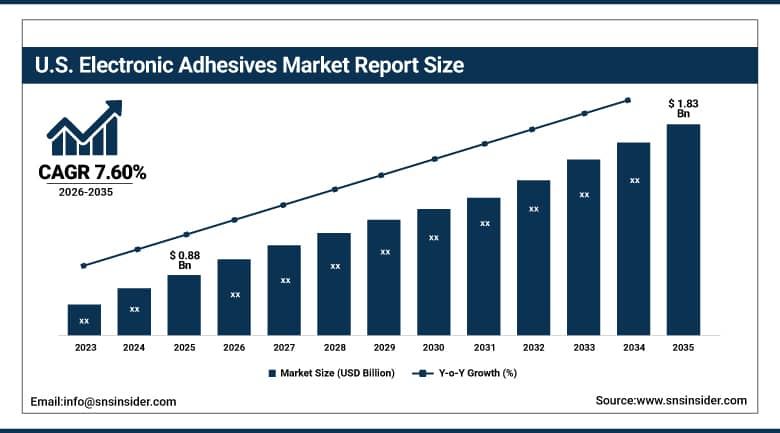
The U.S. Electronic Adhesives Market was valued at USD 0.88 Billion in 2025 and is expected to reach USD 1.83 Billion by 2035, growing at a CAGR of 7.60% from 2026-2035.
The US demand continues to be underpinned by a strong semiconductor and electronics manufacturing base and rising adhesive specification across heat management and precision bonding applications throughout the country's device assembly operations. Leading manufacturers continue expanding their specialty epoxy and UV-curable adhesive portfolios, including formulations for medical device, aerospace, and optoelectronic applications, while continued domestic investment in semiconductor packaging capacity keeps strengthening adhesive demand.
Growing electric vehicle and power electronics manufacturing activity further supports domestic market expansion, positioning U.S. producers to serve both established and emerging bonding applications across a broad range of electronic assembly contexts nationwide. Continued federal investment in domestic semiconductor fabrication capacity further reinforces long-term demand for high-performance, low-outgassing adhesive formulations across the country's expanding chip manufacturing base.
⮞On February 17, 2025, Master Bond introduced a two-component, thermally conductive, electrically insulative epoxy system designed for medical device applications, featuring reliable electrical insulation properties with volume resistivity exceeding 10 to the 14th power ohm-centimeters. The company stated the formulation addresses growing demand for precision bonding in sensitive electronic assemblies.
Electronic Adhesives Market Segment Analysis
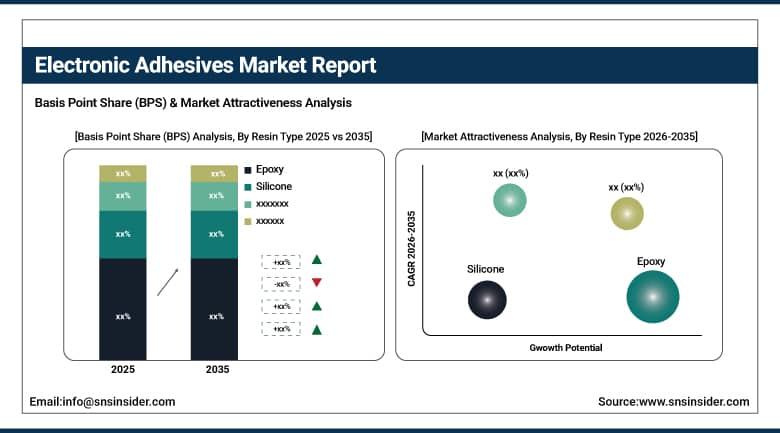
- By Resin Type, Epoxy segment dominated the Electronic Adhesives Market in 2025 with 58% share; Silicone segment is the fastest growing segment.
- By Form, Liquid segment dominated the market in 2025 with 51% share; Paste segment is the fastest growing segment.
- By Application, Surface Mounting segment dominated the market in 2025 with 34% share; Potting & Encapsulation segment is the fastest growing segment.
- By End-Use, Consumer Electronics segment dominated the market in 2025 with 38% share; Automotive segment is the fastest growing segment.
By Resin Type, Epoxy Dominates Electronic Adhesives Market; Silicone to Register Fastest Growth.
Epoxy is leading the Electronic Adhesives Market owing to its strong adhesion, mechanical strength, thermal stability, and resistance to moisture and chemicals in electronic assemblies of different nature. As such, epoxy adhesives can be utilized in applications requiring bonding, encapsulation, attachment of components, and protection of sensitive electronic elements. The already proven processing techniques and the ability of epoxy adhesives to work well on a variety of substrates are additional factors contributing to their popularity among manufacturers. Growing production of semiconductors, printed circuit boards, consumer electronics, and electronic modules keeps driving demand for epoxy electronic adhesives.
Silicone is expected to grow at the highest CAGR owing to its flexibility, excellent temperature resistance, moisture barrier qualities, and reliability when subjected to mechanical and thermal stress. These features are especially important for electronics subject to vibration, temperature cycles, and operation under tough conditions. Rising demand for silicone adhesives in automotive electronics, electric vehicles, sensors, LED technologies, and advanced electronic modules is further boosting their applications in the electronics industry. Enhanced formulation properties, including increased adhesion and cure characteristics, are driving adoption of silicone adhesives.
By Form, Liquid Dominates Electronic Adhesives Market; Paste to Register Fastest Growth.
The Electronic Adhesives Market is primarily led by liquid adhesives due to their ability to offer effective application, coverage, and bonding on electronic assemblies. The adhesives are able to enter gaps and cover even complex surfaces and are capable of automated dispensing in addition to being highly compatible with high-speed manufacturing processes. Liquid adhesives find their application in bonding, coating, encapsulation, and assembly of components on circuit boards and electronic devices.
Paste adhesives are anticipated to witness the highest growth driven by the need for controlled application and effective bonding from the manufacturers of densely packed electronic assemblies. The higher viscosity of the adhesives prevents spreading and allows for precise application on the target surfaces and components. In addition, paste formulations are more amenable to automated dispensing as well as screen printing applications. Increasing demand for miniaturized electronics, high density circuit board assemblies, and components is driving the demand for paste adhesives.
By Application, Surface Mounting Dominates Electronic Adhesives Market; Potting & Encapsulation to Register Fastest Growth.
The Surface Mounting holds the largest share in Electronic Adhesives market since it ensures efficient mounting and securing of electronic components on PCBs by allowing compact and high-density electronic assembly. Adhesives are useful in securing the components through manufacturing processes and also in improving assembly since they play a significant role in positioning and stabilizing the electronic components. Since surface mounting is popular among various types of consumer electronics, telecommunications, automotive electronics, and industrial electronics, there is increased demand for the adhesives used in this type of assembly.
Potting & Encapsulation is the fastest growing segment in the global electronic adhesives market due to increasing need of protection against moisture, dust, chemical, vibrational, and thermal stresses for electronic components. Adhesives can offer insulation and mechanical protection along with improved reliability under extreme environmental conditions for the components. There has been an increased requirement for potting and encapsulation due to the rising demand for electric vehicles, power electronics, sensors, and industrial automation.
By End-Use, Consumer Electronics Dominates Electronic Adhesives Market; Automotive to Register Fastest Growth.
The Consumer Electronics segment will lead the Electronic Adhesives Market, as smartphones, laptops, tablets, wearables, televisions, and other devices need adhesives for component bonding, protection, assembly, and thermal management. Functionalities and miniaturizations in the electronic devices industry are leading to increased need for materials that can support small-scale electronic architectures. Additionally, large production volumes of consumer electronics create a recurring demand for adhesives. Connected devices, advanced displays, portable electronics, and smart home electronics are also growing in their numbers and thus, creating an increasing demand for electronic components and assemblies.
Electric Vehicles is likely to witness the highest growth rate as there is an increase in the number of electronic systems in the vehicles for electrification, connectivity, driver assistance, infotainment, and power management. Electronic adhesives offer properties such as bonding, sealing, insulation, thermal management, and protection from vibrations and environmental exposure for automotive electronic assemblies. Moreover, the growth of Electric Vehicles is contributing to higher adhesives demand in the batteries, power electronics, sensors, and control modules of the vehicles. Growth in semiconductors per car and compact electronic systems is further aiding adoption.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|
Asia Pacific |
China |
39.70% |
|
North America |
United States |
78.60% |
|
Europe |
Germany |
33.90% |
|
Latin America |
Brazil |
40.80% |
|
Middle East & Africa |
United Arab Emirates |
29.60% |
Asia Pacific Electronic Adhesives Market Insights
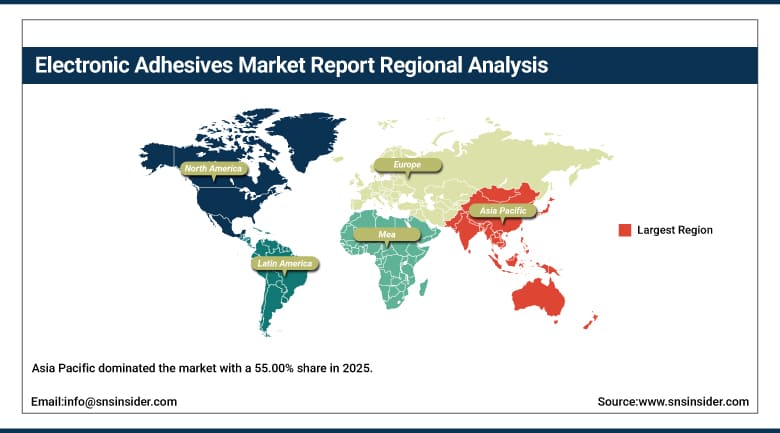
Asia Pacific dominated the market with a 55.00% share in 2025. The region's extensive electronics manufacturing ecosystem, spanning semiconductor fabrication through finished consumer device assembly, continues to anchor this leadership position across virtually every application category. China continues to anchor regional demand as electronics manufacturers expand production capability across both established coastal manufacturing hubs and rapidly developing regional facilities, supported by sustained government investment in domestic semiconductor and electronics supply chain development.
Japan and South Korea contribute substantial additional regional demand, anchored by leading semiconductor foundries and consumer electronics manufacturers requiring high-performance adhesive formulations. Taiwan's advanced semiconductor packaging industry further reinforces regional demand, positioning Asia Pacific to sustain its position as the largest global market for electronic adhesives through the forecast period.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Electronic Adhesives Market Insights
North America is projected to be the fastest-growing region, registering a CAGR of 7.60% during 2026-2035, supported by a strong domestic electronics and semiconductor industry alongside rising demand for medical devices and wearables requiring specialized adhesive formulations. The United States shapes regional demand through its concentration of leading specialty adhesive developers and expanding semiconductor packaging investment under domestic manufacturing incentive programs.
Canada contributes additional regional demand through its participation in North American electronics manufacturing and distribution networks. Continued domestic investment in semiconductor fabrication capacity is expected to keep North America expanding at the fastest pace of any region through the forecast period, even as Asia Pacific retains the larger overall revenue base.
Europe Electronic Adhesives Market Insights
Europe holds a meaningful share of the global market, underpinned by a dense concentration of established specialty adhesive manufacturers and continued advancement in automation of electronic device assembly. Germany's substantial electronics and automotive manufacturing base anchors regional demand, supported by a well-developed industrial ecosystem that continues to favour early adoption of next-generation adhesive technology across the country and neighbouring markets.
The United Kingdom, France, and other major European markets contribute consistent demand as regional electronics and automotive manufacturers continue extending advanced adhesive technology into routine production practice. Continued growth in the significance of device automation across the region keeps informing adhesive technology investment, reflecting Europe's role as both an established manufacturing base and a mature, steadily growing end market.
MEA & Latin America Electronic Adhesives Market Insights
Latin America's market is anchored by Brazil, which accounts for the majority of regional demand on the strength of its growing electronics assembly and automotive manufacturing sector. Gradual growth in domestic manufacturing production continues to support steady regional market development.
The Middle East & Africa region continues to grow in strategic importance, with demand concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where increasing investments toward infrastructure development, including telecommunications and smart city projects, continue to drive demand for electronic components and adhesives. South Africa continues to anchor demand on the African continent, supported by its comparatively more developed industrial manufacturing infrastructure.
Market Dynamics
Growth Drivers: Device Miniaturization and Industry 4.0 Adoption
Rise in the requirement of adhesives in the manufacture and maintenance of electronics products is the most significant factor driving the growth of the market due to the miniaturization of electronic devices that requires highly accurate and efficient adhesives. Such growth in demand is supplemented by the growing trend of using Industry 4.0 manufacturing techniques wherein manufacturers use automation in the application of adhesives in production processes.
Increasing use of electronics adhesives in various industries such as telecommunication, consumer electronics, and automotive industry is another major factor boosting the market growth. Increase in the use of medical devices and wearables requiring adhesives is yet another factor boosting the market growth.
Restraints: Outgassing Concerns and Raw Material Price Volatility
Outgassing issues still represent an actual restraint in terms of the market growth potential, since the emission of volatile substances from certain types of adhesives may result in contamination, corrosion, or malfunction of delicate electronic parts, which entails significant expenditures for low-outgassing formulations creation for companies. This issue becomes especially relevant in regard to sealed enclosures and optical devices, where the smallest amount of contamination may affect the performance of a device.
The fluctuation of prices for raw materials also represents a restriction for the industry's further growth, as the prices of specialized resins and curing agents remain highly volatile in line with changes in petrochemicals' market, which poses challenges to margins of companies working under cost pressure. This implies that large-scale manufacturers need to make additional efforts in regard to supply chain management.
Opportunities: UV-Curable Technology and Electric Vehicle Adhesive Demand
Further developments in the area of UV-curing adhesives represent a significant growth opportunity, since companies developing formulations that cure faster and emit fewer chemicals will benefit from increased demand due to improved production efficiency from producers in the face of stringent environmental regulations. Electronic device manufacturers are looking at such adhesives not as an innovation but rather as a necessity that can improve the speed of their production lines and comply with the regulatory framework.
Further expansion in the field of electric vehicles and power electronics manufacturing represents another growth opportunity, since batteries, power modules, and other parts used in advanced driver assistance systems require special heat and electrically conductive adhesive formulations. This growth path is still generating significant demand for manufacturers who are experienced in producing automotive-grade adhesives.
Recent Developments:
- 2025: Henkel introduced a range of LED-curable Loctite adhesives, including the AA 3951/3953 and AA 3961/3963 product lines, designed for medical device assembly applications.
- 2025: H.B. Fuller expanded its conductive adhesive portfolio with a silver-enhanced formulation designed to improve electrical performance across electronic bonding applications.
- 2025: 3M released an upgraded UV-curable adhesive series offering faster curing speed for precision electronic assembly applications.
- 2025: DELO Industrial Adhesives continued expanding its high-purity, low-outgassing adhesive portfolio to meet stringent OLED and augmented and virtual reality display bonding requirements.
Electronic Adhesives Companies are:
- Henkel AG & Co. KGaA
- 3M Company
- H.B. Fuller Company
- Dow Inc.
- Master Bond Inc.
- Ellsworth Adhesives
- Evonik Industries AG
- Panacol-Elosol GmbH
- DELO Industrial Adhesives GmbH & Co. KGaA
- Parker Hannifin Corporation (LORD Corporation)
- Permabond LLC
- Dymax Corporation
- Sika AG
- Huntsman Corporation
- ThreeBond Holdings Co., Ltd.
- Namics Corporation
- Shin-Etsu Chemical Co., Ltd.
- Resonac Holdings Corporation
- Nagase America LLC
- Bostik SA (Arkema Group)
Electronic Adhesives Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.38 Billion |
| Market Size by 2035 | USD 10.15 Billion |
| CAGR | CAGR of 6.55% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Resin Type (Epoxy, Silicone, Others) • By Form (Liquid, Paste, Solid) • By Application (Surface Mounting, Conformal Coating, Potting & Encapsulation, Wire Tacking, Others) • By End-Use (Consumer Electronics, Automotive, Telecommunications, Industrial, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Henkel AG & Co. KGaA, 3M Company, H.B. Fuller Company, Dow Inc., Master Bond Inc., Ellsworth Adhesives, Evonik Industries AG, Panacol-Elosol GmbH, DELO Industrial Adhesives GmbH & Co. KGaA, Parker Hannifin Corporation (LORD Corporation), Permabond LLC, Dymax Corporation, Sika AG, Huntsman Corporation, ThreeBond Holdings Co., Ltd., Namics Corporation, Shin-Etsu Chemical Co., Ltd., Resonac Holdings Corporation, Nagase America LLC, Bostik SA (Arkema Group) |

Frequently Asked Questions
Asia Pacific dominated the market with a 55.00% share in 2025, supported by the region's extensive electronics manufacturing ecosystem, led by China.
By Application, Surface Mounting dominated the market in 2025.
Key players include Henkel, 3M, H.B. Fuller, Dow, Master Bond, Ellsworth Adhesives, Evonik Industries, Panacol-Elosol, DELO Industrial Adhesives, and Parker Hannifin, among others.
Continued advancement of UV-curable adhesive technology and the continued expansion of electric vehicle and power electronics manufacturing represent the two most significant opportunities shaping the market's next phase of growth.
Growth is primarily driven by increasing demand for adhesives supporting electronic device miniaturization, combined with rising adoption of Industry 4.0 manufacturing concepts.
