
Embedded Payments Market Report Scope & Overview:
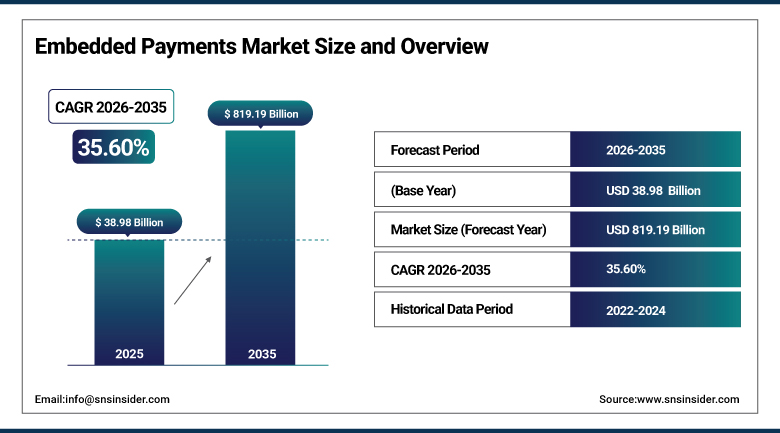
The Embedded Payments Market was valued at USD 38.98 Billion in 2025 and is expected to reach USD 819.19 Billion by 2035, growing at a CAGR of 35.60% from 2026-2035.
The Embedded Payments Market is growing quickly as software platforms, marketplaces and vertical applications build payment acceptance, payouts and financing directly into their own user journeys. Instead of redirecting customers to a separate checkout, merchants now accept cards, wallets and bank transfers inside the app, and platforms earn a share of processing revenue. Payment facilitators, issuer processors and banking-as-a-service providers supply the infrastructure through application programming interfaces. Real-time payment rails, open banking and stablecoin settlement are widening the choices available to platforms. The competition is moving to developer experience, global coverage, and financial services integration, while consolidation is taking place for technology expansion. North America leads in market size, while Asia Pacific is projected to be the fastest-growing region.
⮞In August 2026, Adyen reported first-half processed volume up 24% and net revenue of about USD 1.50 billion, up 19%, and raised its 2026 net revenue growth outlook to 21% to 23% in constant currency. The results show strong demand for unified payment platforms embedded in merchant software.
To Get more information Embedded Payments Market - Request Free Sample Report
Embedded Payments Market Trends
-
Software platforms are becoming payment facilitators to capture processing revenue from their merchants.
-
Real-time payment networks and account-to-account transfers are being added alongside card acceptance.
-
Payouts, working capital and card issuing are being bundled with acceptance in a single integration.
-
Stablecoin settlement and cross-border payment services are being tested by leading processors.
-
Mergers among payment providers are consolidating technology and widening geographic coverage.
U.S. Embedded Payments Market Outlook
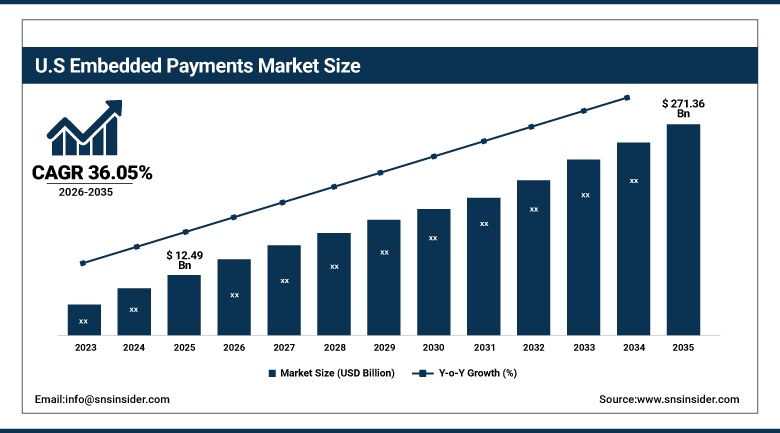
The U.S. Embedded Payments Market was valued at USD 12.49 Billion in 2025 and is expected to reach USD 271.36 Billion by 2035, growing at a CAGR of 36.05% from 2026-2035.
The U.S. Embedded Payments Market is the largest national market for software-led payments, supported by a dense base of vertical software vendors, marketplaces and small businesses that rely on digital tools. Platforms in restaurants, healthcare, property management, field services and e-commerce increasingly act as payment facilitators and earn revenue on each transaction they process. Card networks, acquirers and fintech processors compete to supply the underlying infrastructure, and the FedNow service and the RTP network add real-time options for payouts and bill payment. Regulators are watching consumer protection and sponsor bank oversight closely. Growth remains very strong as more software vendors add payments to their offering, and sponsor banks, issuer processors and acquirers expand their partnerships with platforms.
⮞In July 2026, the Federal Reserve's FedNow Service reported more than 1,800 participating banks and credit unions, including seven of the ten largest U.S. banks, up from more than 1,600 in January 2026. The expanding network gives embedded platforms a growing set of instant account-to-account routes.
Embedded Payments Market Segment Analysis
-
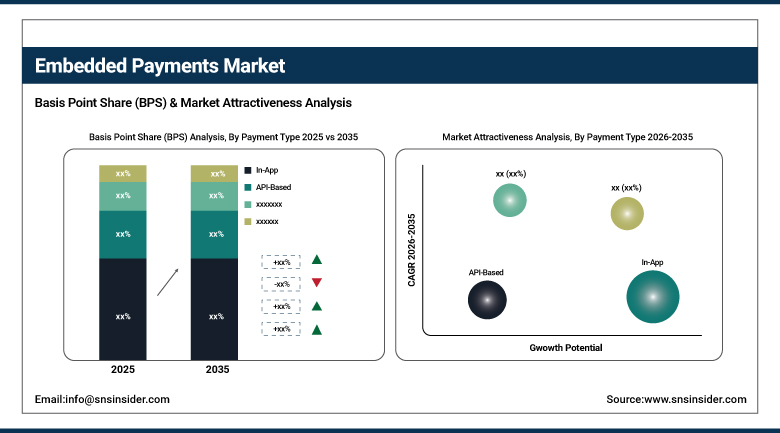
By Payment Type, the In-App segment dominated the Embedded Payments Market with approximately 34.60% share in 2025, while the API-Based segment is the fastest growing with a CAGR of approximately 38.45%.
-
By Payment Method, the Digital Wallets segment dominated the Embedded Payments Market with approximately 33.20% share in 2025, while the Mobile Payments segment is the fastest growing with a CAGR of approximately 37.12%.
-
By Industry Vertical, the E-Commerce segment dominated the Embedded Payments Market with approximately 36.80% share in 2025, while the Healthcare segment is the fastest growing with a CAGR of approximately 38.64%.
-
By Deployment, the Cloud segment dominated the Embedded Payments Market with approximately 74.00% share in 2025, while the On-Premise segment is the fastest growing with a CAGR of approximately 37.05%.
By Payment Type, In-App Dominates the Embedded Payments Market and API-Based Grows Fastest
In-app payments lead because consumers increasingly complete purchases inside the mobile applications and software tools they already use. Ride hailing, food delivery, ticketing, subscription and marketplace apps store payment credentials and process a purchase in a single tap, which lifts conversion and reduces abandoned carts. Platforms value the control over the checkout experience and the data it generates, and they can add tipping, loyalty and split payments inside the same flow. Device wallets and tokenization have improved security, so customers feel comfortable keeping payment details inside the app.
API-based payments are growing fastest as developers use well-documented interfaces to add acceptance, payouts, identity checks and card issuing without building a processing stack. Providers offer sandbox environments, software development kits and modular components, allowing a vertical software vendor to launch payments within weeks. Platform-integrated, software-as-a-service and marketplace models draw on the same interfaces, and split payment features let a marketplace route funds to many sellers. Competition among providers is based on developer experience, pricing transparency, reliability and the breadth of countries and payment methods supported, and many publish clear documentation to attract engineering teams.
⮞In August 2026, Marqeta reported second-quarter total processing volume of USD 120.4 billion, up 32%, with net revenue of USD 176.0 million, up 17%. The figures show strong volume growth in programmable card issuing.
By Payment Method, Digital Wallets Dominates the Embedded Payments Market and Mobile Payments Grows Fastest
Digital wallets are the most widely used method inside embedded checkouts because they combine speed, stored credentials and strong authentication through biometrics. Consumers use wallets from device makers, payment companies and super apps, and platforms benefit from higher approval rates and lower fraud when tokens replace card numbers. Merchants add wallets with a few lines of code through their payment provider, and wallets support one-tap experiences across web and mobile. Credit and debit cards remain the settlement backbone behind many wallets, while bank transfers are gaining use for large or recurring payments.
Mobile payments are growing fastest as smartphones become the main device for shopping, bill payment and peer-to-peer transfers, particularly in Asia Pacific, Latin America and Africa. Quick response codes, near-field communication and instant payment schemes allow low-cost transactions at the point of sale and online. Super apps embed payments inside messaging, transport and commerce services, creating high-frequency usage. Providers are linking mobile payments with credit, loyalty and merchant financing, and regulators are encouraging interoperability among wallets and bank accounts to expand acceptance, which lowers merchant costs and widens the user base.
⮞In the quarter ended 30 June 2026, PayPal reported total payment volume of USD 486 billion, up 9% on a currency-neutral basis, with Braintree payment services volume up 13%. The data highlights steady growth in merchant payment processing.
By Industry Vertical, E-Commerce Dominates the Embedded Payments Market and Healthcare Grows Fastest
E-commerce accounts for the largest share of embedded payments because online retailers, marketplaces and subscription businesses were early adopters of integrated checkout, and they process very large volumes. Storefront platforms bundle payment acceptance, fraud screening and buy-now-pay-later options directly into their merchant tools, which makes payments a core revenue line. Merchants prefer faster onboarding, consolidation of reporting, and automatic payments and have the ability to provide "buy now pay later" solutions without any additional contractual agreements. The complexities of cross-border sales and local payments increase the difficulty, and thus, merchants prefer platforms that provide everything within one integration.
Healthcare is growing fastest as clinics, hospitals and digital health providers move to patient-friendly billing. Embedded payment tools let patients pay at the point of care, set up installment plans and receive statements through portals and mobile apps, while practice management software reconciles transactions automatically. Providers gain faster collections and reduced administrative costs. Financial services, retail, hospitality, transportation and logistics also add embedded payments, with restaurants and field service businesses using integrated point-of-sale and software systems to manage payments, tips and payroll, and logistics firms embedding payouts for drivers and carriers.
⮞In August 2026, Shopify reported second-quarter gross merchandise volume of USD 115.6 billion, up 32%, with Shopify Payments processing USD 78.1 billion and reaching 68% penetration of volume. The figures show how deeply payments are embedded in commerce software.
By Deployment, Cloud Dominates the Embedded Payments Market and On-Premise Grows Fastest
Cloud deployment dominates because embedded payments depend on elastic capacity, quick releases and continuous security updates that cloud platforms provide. These companies offer services like acceptance, tokenization, fraud scoring and reconciliation in the form of managed services, thus enabling software providers to enter into new geographies without having to host their data centers. The pay as you go approach is ideal for start-ups and medium size platforms, while availability in several geographies helps meet data residency regulations. Integration with accounting, enterprise resource planning and customer relationship management systems becomes easy in the cloud environment, making the integration cost-effective and quick.
On-premise deployments are growing rapidly, though from a small base, powered by large banking organizations and regulated entities that require direct control over their data. Certain financial organizations retain key ledgers and card processing within their own premises while interfacing with external providers via gateways. A common pattern is a hybrid model where sensitive operations are performed on purpose-built infrastructure, while customer-facing operations run in the cloud. Vendors are packaging containerized software that can run in either environment, helping large organizations modernize without giving up control, while regulators in some markets favor local processing of sensitive payment data.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.30% |
|
Europe |
United Kingdom |
29.68% |
|
Asia Pacific |
China |
38.52% |
|
Latin America |
Brazil |
47.30% |
|
Middle East and Africa |
United Arab Emirates |
31.20% |
North America Embedded Payments Market Insights
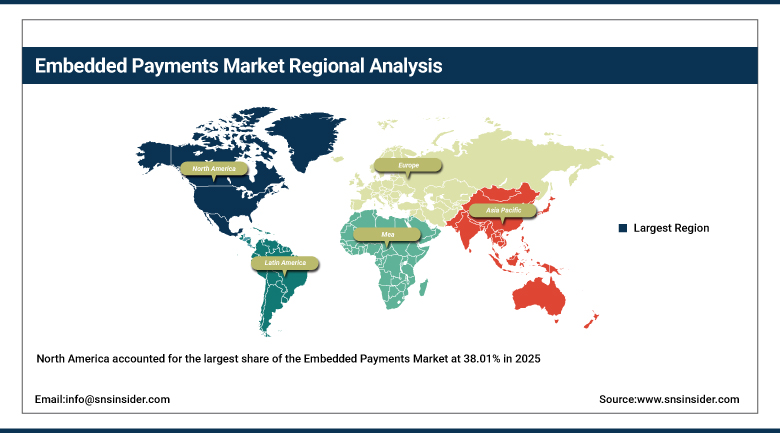
North America accounted for the largest share of the Embedded Payments Market at 38.01% in 2025, led by the United States, with Canada contributing a smaller but mature market. The region has the highest density of vertical software vendors, marketplaces and payment technology companies, and merchants are used to digital checkout and card acceptance. Platforms in restaurants, healthcare, property management and e-commerce have added payment facilitation to raise revenue per customer. Venture funding and a deep pool of engineering talent keep new providers entering, and private equity continues to back vertical software platforms with payments roadmaps.
Competition between established acquirers, card networks and fintech processors is intense, and pricing pressure favors providers with scale. With real-time payments such as FedNow and RTP, account-to-account payment and bill payment are some of the services that are provided, while open banking initiatives expand the reach of data sharing and tokenization in the bank partnerships. Consumer protection, anti-money laundering laws, and regulation of the sponsor banks that back fintechs are the top priorities of regulators. Growth remains robust as smaller firms continue to move their transactions into integrated platforms and larger companies seek a single payments stack.
⮞In August 2026, Block reported second-quarter Square gross payment volume of USD 72.8 billion, up 13%, with Square gross profit of USD 1.16 billion, up 13%. The results reflect steady growth among small business sellers using integrated payment tools.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Embedded Payments Market Insights
Europe is a large and technically advanced market, supported by the Single Euro Payments Area, strong open banking rules and widespread acceptance of contactless and wallet payments. The region is the home of several leading global processors, and software platforms use local methods such as bank transfers and direct debit alongside cards. The United Kingdom, Germany, France and the Netherlands are the main centers of activity, and the Nordic countries lead in digital adoption. Merchants expect payment options to match local preferences in each country, so platforms that support many local methods gain an edge, and banks are partnering with fintech providers to offer integrated services to business clients.
Regulation is an important determinant. The reformed Payment Services Directive regulation enhances the role of authentication and the regulation of fraud liability, while the Instant Payments Regulation demands that all euro area providers must provide instant transfer services at the same cost as the traditional one. Such requirements will give the advantage to providers who have the ability to link to multiple schemes and account-to-account checkout. Cross-border sales inside the bloc are very easy, which facilitates the development of the platform. Growth rates are high, but some issues of fragmentation of local schemes and compliance costs may hold back small providers.
⮞Under the European Union Instant Payments Regulation, euro-area payment service providers had to send instant payments with verification of payee by 9 October 2025, and payment and e-money institutions must send and receive them by 9 April 2027, according to the European Central Bank. The mandate opens a large account-to-account channel for embedded checkout.
Asia Pacific Embedded Payments Market Insights
Asia Pacific is the fastest growing region, with a projected CAGR of 37.84% from 2026-2035, supported by the world's largest mobile-first consumer base, rapid growth of super apps and strong government support for digital payment schemes. China has the most developed ecosystem of embedded wallets in commerce and transport platforms. India's Unified Payments Interface has made account-to-account payments an everyday habit for consumers and small merchants alike, and Southeast Asia, Japan, South Korea and Australia are adding real-time schemes and open banking, and platform operators are tailoring wallets and checkout flows to local tastes.
⮞In September 2026, the National Payments Corporation of India reported that the Unified Payments Interface processed 24.07 billion transactions, up 23% from September 2025, with a value of INR 29.37 lakh crore. The data shows the scale of real-time payments behind embedded checkout in India.
Merchants and platforms in the region embed payments in messaging, ride hailing, food delivery and marketplace services, and cross-border e-commerce is creating demand for multi-currency settlement. Regulation differs by country, with data localization and licensing requirements shaping market entry for global providers. Local champions compete with international processors, and partnerships are common, with global processors working alongside domestic wallets and banks to reach merchants. Government digital identity programs also simplify merchant onboarding. The combination of mobile adoption, low-cost real-time rails and a large population of small merchants points to the fastest expansion among the major regions.
MEA and Latin America Embedded Payments Market Insights
The Middle East and Africa is led by the United Arab Emirates, with Saudi Arabia, Egypt, Nigeria, Kenya and South Africa also contributing. Mobile money, agent networks and super apps provide payment access for large populations without bank accounts, and Gulf governments are investing in instant payment systems and open banking. Platforms in commerce, ride hailing and delivery are embedding wallets and card acceptance, and global processors are opening regional hubs. Currency controls, fragmented regulation and low card penetration in some countries limit the pace of growth, although mobile money operators and fintech start-ups are steadily closing the gap.
Brazil, alongside Mexico, Argentina, Colombia, and Chile, constitutes an important country in Latin America, and Mexico can be classified as one of the countries in Latin America. Payment methods of Brazil have created a revolution in the field of payment, and they are being used for checkouts, POS, and invoicing applications. Installment payments and local payments are some of the payment methods that merchants use, and they have to be supported by international payments processors. The fintech platforms are growing in acquiring and card issuance for small merchants. Inflation and currency volatility create challenges, but digital adoption remains strong and supports a long runway for platform-led payments.
Growth Drivers: Platform Monetization and Real-Time Payment Rails Drive Growth in the Embedded Payments Market
Software platforms are discovering that payments are one of the most profitable features they can add. By acting as payment facilitators, vertical software vendors earn a share of processing revenue on top of subscription fees, and the customer relationship deepens as payments, payouts and financing sit in one place. Providers have simplified onboarding and compliance through standard interfaces, so even small vendors can launch quickly. This monetization logic is spreading from retail and restaurants to healthcare, education, property management and professional services.
Real-time payment rails and wider digital adoption add momentum. Instant payment systems in the United States, Europe, India and Brazil let platforms offer faster payouts, lower costs and account-to-account checkout. Consumers expect seamless digital experiences, and businesses want same-day access to funds, which makes instant settlement a competitive feature for any platform that handles money. Growth in global card and wallet volumes provides a rising base for processing, and the continued shift of commerce online increases the number of transactions that can be embedded in software across the forecast period, with small merchants in emerging markets joining platforms that bring them online.
⮞In July 2026, Visa reported fiscal third-quarter net revenue of USD 11.6 billion, up 14%, with payments volume up 10% in constant dollars and 71.7 billion processed transactions. The figures indicate a rising global base of digital payment activity.
Restraints: Fraud Exposure and Regulatory Complexity Restrain Growth in the Embedded Payments Market
Embedded payments expose platforms to fraud, chargebacks and compliance obligations that they may not be equipped to handle. When a software vendor becomes a payment facilitator, it takes on responsibility for merchant onboarding, sanctions screening and dispute resolution. Account takeover, synthetic identities and authorized push payment scams are growing, and losses can damage trust and invite closer supervision of the whole sector. Smaller platforms often rely on providers to bear these risks, which limits the economics they can capture and slows adoption among conservative software vendors.
Regulatory complexity adds further friction. Regulations related to payments licensing, data security, strong authentication, and sponsor bank monitoring vary by country, while regulation authorities are being more cautious in the area of cooperation between fintechs and banks. Price pressure from large payment processors squeezes margins, and the old infrastructure of some banks and acquirers complicates the process of modernization. Technical integration issues and the expense of supporting a number of different payment types in multiple countries can delay product launch, especially in cross-border operations, and staff expenses also increase.
⮞In August 2026, Fiserv reported second-quarter adjusted revenue of USD 4.96 billion, down 4%, while Clover revenue rose 2% as reported and 11% on an adjusted basis. The mixed result shows the pressure facing established processors during platform transitions.
Opportunities: Cross-Border Payments and Embedded Financing Create Opportunities in the Embedded Payments Market
Cross-border commerce and payouts are a large opportunity. Platforms serving freelancers, marketplaces and global sellers need to collect and disburse funds in many currencies quickly and cheaply. Providers that combine local acquiring, multi-currency accounts and compliance in one interface can win this business. Stablecoin settlement and faster international rails may further cut costs and settlement times for platforms with global sellers, and several leading processors are building infrastructure to support them, with pilots under way with banks and large merchants.
Embedded financing and card issuing are a second opportunity. Processors hold detailed data on merchant sales, which supports working capital advances, installment plans and revenue-based lending that can be repaid from future transactions. Platforms can issue cards for expenses and payouts, earning interchange and strengthening loyalty. Artificial intelligence is improving fraud detection, routing and customer support, and small and medium businesses in emerging markets remain underserved, offering a large addressable base for integrated payment services, and providers with local licenses are positioned to capture it.
⮞In the quarter ended 30 June 2026, Mastercard reported gross dollar volume of USD 2.9 trillion, up 8% in local currency, with net revenue of USD 9.3 billion, up 14%. The data shows the scale of card activity that embedded platforms can build on.
Recent Developments:
-
In February 2026, Stripe reported 2025 total payment volume of USD 1.9 trillion, up 34%, and an employee tender offer that valued the company at USD 159 billion. The company also acquired Bridge, Privy and Metronome during 2025, widening its stablecoin and billing capabilities.
-
In June 2026, Nuvei agreed to acquire Payoneer for USD 7.40 per share in cash, an equity value of about USD 2.75 billion, creating a company expected to process more than USD 500 billion in annual payment volume. The transaction is expected to close in mid-2027.
-
In June 2026, Airwallex raised USD 320 million in a Series H round at a valuation of USD 11 billion, with annualized revenue of USD 1.30 billion as of March 2026. The funding supports expansion of its global payments and treasury platform.
-
In August 2026, Toast reported second-quarter gross payment volume of USD 60.7 billion, up 22%, with about 180,000 locations after adding 9,500 net new locations in the quarter. The results confirm growing adoption of its integrated restaurant payments platform.
Embedded Payments Market Key Players
-
Stripe
-
PayPal
-
Worldpay
-
Block
-
Marqeta
-
Fiserv
-
Checkout.com
-
Rapyd
-
Mangopay
-
Finix
-
Mollie
-
GoCardless
-
Paddle
-
Spreedly
-
Cashfree
-
Plaid
-
Toast
-
Nuvei
Embedded Payments Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 38.98 Billion |
| Market Size by 2035 | USD 819.19 Billion |
| CAGR | CAGR of 35.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Payment Type (In-App, API-Based, Platform-Integrated, SaaS, and Marketplace) • By Payment Method (Digital Wallets, Credit and Debit Cards, Bank Transfers, and Mobile Payments) • By Industry Vertical (E-Commerce, Healthcare, Financial Services, Retail, Hospitality, Transportation and Logistics, and Others) • By Deployment (Cloud and On-Premise) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Stripe, Adyen, PayPal, Worldpay, Block, Shopify, Marqeta, Fiserv, Checkout.com, Rapyd, Mangopay, Finix, Mollie, GoCardless, Paddle, Spreedly, Cashfree, Plaid, Toast, Nuvei |

Frequently Asked Questions
Key opportunities include cross-border payments and payouts, embedded financing and card issuing, and stablecoin settlement. Small and medium businesses in emerging markets also offer a large base for integrated payment services.
The major growth factor is platform monetization. Software vendors earn processing revenue by becoming payment facilitators, and real-time payment rails make payouts faster and cheaper.
The In-App segment dominated the Embedded Payments Market in 2025 with approximately 34.60% share. Its lead reflects the growing share of purchases completed inside mobile applications and software tools.
