
EV Test Equipment Market Report Scope & Overview:
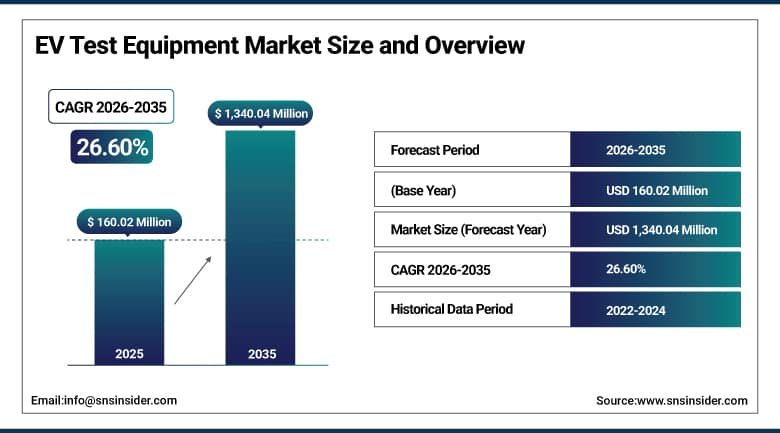
The EV Test Equipment Market was valued at USD 160.02 Million in 2025 and is expected to reach USD 1,340.04 Million by 2035, growing at a CAGR of 26.60% from 2026-2035.
The EV Test Equipment Market is being fueled mainly by the ongoing electric vehicle revolution across the globe, which is forcing manufacturers and research institutions to prioritize the validation process to make sure that every component from the battery cells, inverters, chargers, and motors is safe and efficient enough to pass all the required benchmarks before being shipped off on the roads. With rising electric vehicle manufacturing volumes and evolving battery chemistry and power electronics technologies, there is always a huge requirement for dedicated test equipment that can validate increasingly complicated electric vehicle architectures by both the original equipment manufacturer (OEM) and the first-tier supplier companies.
Another factor fueling the demand is the increased requirement for validation of evolving charging standards, voltage architecture, and the use of real-time connected analytics technology in the test equipment setup. Continuous investment by the vendors in flexible and scalable test solutions with automated and safety-compliant validation process to reduce cost-per-test time will fuel growth of the market in the coming years.
In 2024, HORIBA announced the acquisition of DYNATEST, a German company specializing in electric drivetrain test benches, strengthening HORIBA's portfolio in the electric vehicle test equipment sector.
To Get More Information On EV Test Equipment Market - Request Free Sample Report
EV Test Equipment Market Trends
- Growing integration of AI-driven analytics for predictive maintenance and validation accuracy in test equipment.
- Rising demand for modular, scalable test platforms supporting compatibility across fast-evolving charging standards.
- Continued shift toward software-defined, highly automated test benches for battery and powertrain validation.
- Increasing consolidation as test equipment manufacturers acquire specialized electric drivetrain testing firms.
- Expanding development of high-voltage-compatible test systems supporting next-generation EV architectures.
U.S. EV Test Equipment Market Outlook
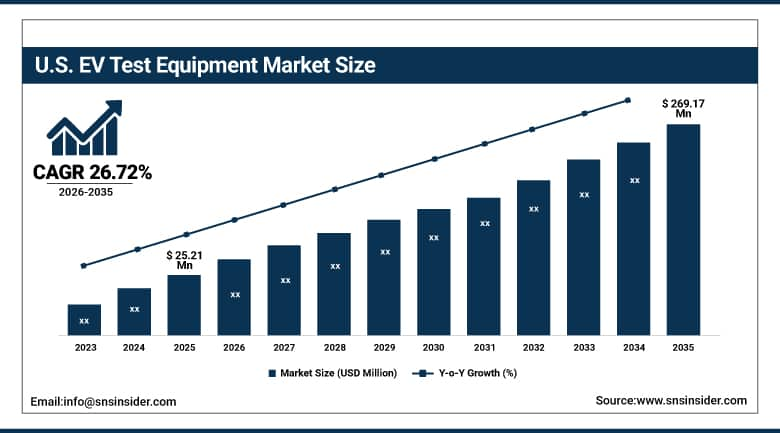
The U.S. EV Test Equipment Market was valued at USD 25.21 Million in 2025 and is expected to reach USD 269.17 Million by 2035, growing at a CAGR of 26.72% from 2026-2035.
U.S. EV Testing Equipment Market is further boosted by robust domestic electric vehicle production growth, supportive government policies toward adoption of zero-emission vehicles, and a presence of major test & measurement equipment manufacturers in the country. The domestic market is further driven by substantial OEM investments in building validation facilities for batteries and powertrains in view of increasing range of electric vehicle models. Robust domestic battery gigafactory investments fuel demand for battery testing equipment which can validate high-power and high-voltage battery technologies.
In 2025, HORIBA secured a major contract win with General Motors to supply advanced EV battery and propulsion test systems supporting GM's Ultium platform testing program.
EV Test Equipment Market Segment Analysis
- By Vehicle Type, the Passenger Vehicles segment dominated the EV Test Equipment Market with approximately 62.50% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of approximately 24.60%.
- By Propulsion Type, the Battery Electric Vehicle segment dominated the EV Test Equipment Market with approximately 44.80% share in 2025, while the Plug-in Hybrid Electric Vehicle segment is the fastest growing with a CAGR of approximately 23.80%.
- By Equipment Type, the Powertrain segment dominated the EV Test Equipment Market with approximately 47.00% share in 2025, while the Charging segment is the fastest growing with a CAGR of approximately 25.40%.
- By Vehicle Class, the Mid-Priced segment dominated the EV Test Equipment Market with approximately 63.00% share in 2025, while the Luxury segment is the fastest growing with a CAGR of approximately 25.70%.
By Vehicle Type, Passenger Vehicles dominates and Commercial Vehicles grows fastest
Passenger Vehicles remain the dominant vehicle type segment within the EV Test Equipment Market, reflecting the sheer scale of global passenger electric vehicle production relative to commercial vehicle segments. This segment benefits from sustained high-volume electric vehicle sales across passenger car and SUV categories, which continue to require extensive battery, powertrain, and charging validation infrastructure.
Commercial Vehicles are emerging as the fastest-growing vehicle type segment, driven by growing electrification of delivery vans, buses, and medium-duty trucks that require specialized test equipment suited to higher-capacity battery systems and more demanding duty cycles. This segment focuses on validating the durability and performance requirements unique to commercial electric vehicle applications, positioning commercial vehicle testing to capture disproportionate growth as fleet electrification continues to accelerate.
By Propulsion Type, Battery Electric Vehicle dominates and Plug-in Hybrid grows fastest
Battery Electric Vehicles constitutes the most prominent propulsion type category in the market for EV Testing equipment due to the fact that the technology is at the core of the boom in the manufacture of electric vehicles and the extensive testing procedures required for high voltage batteries, inverters and electric drives. The category is characterized by steady investments from original equipment manufacturers in battery electric vehicles platforms that need comprehensive end-of-line and component testing capabilities.
Plug-In Hybrid Electric Vehicle testing applications constitute the fastest growing propulsion type category, driven by the increased attention from automakers to hybrid power trains, which are composed of both internal combustion engines and electric drives, which necessitates testing capabilities for such dual powertrain configurations. The category involves test equipment that enables testing of the integration of traditional and electric drives, hence plug-in hybrids can capitalize on the increasing demand of automakers for hybrid vehicles.
By Equipment Type, Powertrain dominates and Charging grows fastest
The Powertrain Test Equipment is still the leading equipment type segment in the market for EV Test Equipment because of the essential nature of testing the performance of motors, inverters, and drivetrains for increasingly sophisticated electric vehicles. This segment is advantaged by the well-developed technology of dynamometers and drivetrain analyzers that have been used as the core of the powertrain test programs of electric vehicles.
The Charging Test Equipment is becoming the fastest-growing segment of the equipment types in the market due to the constant development of fast-charging standards and testing needs for compatibility in various AC and DC charging technologies. The focus of this segment is on simulators and interface testing of the charging stations, which makes the segment well-positioned to capitalize on increasing demands.
By Vehicle Class, Mid-Priced dominates and Luxury grows fastest
Mid-Priced vehicle class testing applications remain the dominant vehicle class segment within the EV Test Equipment Market, reflecting the largest volume category of electric vehicle production as automakers continue prioritizing mainstream, mass-market electric vehicle platforms. This segment benefits from high-volume production requirements that sustain consistent demand for standardized, cost-effective test equipment across mainstream electric vehicle programs.
Luxury vehicle class testing applications are emerging as the fastest-growing vehicle class segment, driven by premium automakers' increasing investment in advanced electric vehicle technology requiring more sophisticated validation capability for high-performance battery, powertrain, and infotainment systems. This segment focuses on testing equipment capable of validating the more demanding performance and feature requirements of premium electric vehicle platforms, positioning luxury vehicle testing to capture growing investment as automakers continue expanding premium electric vehicle offerings.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
48.60% |
|
North America |
United States |
85.50% |
|
Europe |
Germany |
34.60% |
|
Latin America |
Brazil |
41.80% |
|
Middle East & Africa |
United Arab Emirates |
36.60% |
Asia Pacific EV Test Equipment Market Insights
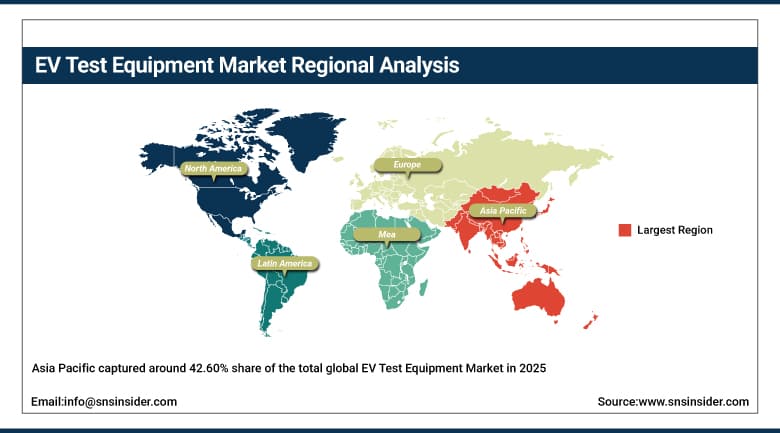
Asia Pacific captured around 42.60% share of the total global EV Test Equipment Market in 2025 and is expected to grow at the fastest rate of 18.06% throughout the forecast period of 2026-2035 owing to the early adoption of public EVs and increasing number of EV manufacturing plants in the region. China contributes most to the region, driven by the presence of electric vehicles manufacturing plants in the country along with the availability of a network of batteries and components makers that require testing facilities.
Japan and South Korea also make contributions in terms of market demand for EV test equipment, which can be attributed to the presence of test and measurement equipment makers in these countries having years of experience in automotive testing technologies.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America EV Test Equipment Market Insights
North America represents a significant regional market for EV test equipment, anchored by the United States' growing electric vehicle production base and its concentration of leading test and measurement equipment providers. The United States accounts for the substantial majority of regional demand, reflecting both favorable government policy supporting zero-emission vehicle adoption and its role as home to prominent industry players.
Canada contribute additional regional volume through cross-border automotive supply chain integration linked to broader North American electric vehicle assembly. Continued domestic battery gigafactory investment further supports steady regional demand growth for specialized battery testing equipment.
Europe EV Test Equipment Market Insights
Europe forms a major region for the demand for testing equipment in the EV market, thanks to Germany being the country with the largest number of auto manufacturers along with the largest number of premium carmakers and providers of test equipment, like AVL and Rohde & Schwarz. The market position of Germany in the region is due to its dominating market presence not only in terms of electric cars manufacturing but also test equipment manufacturers.
The French and UK automotive manufacturing industries help provide further regional demand. The focus of EU regulations on the emission and safety standards of vehicles provides further regional demand for testing infrastructure.
MEA & Latin America EV Test Equipment Market Insights
The Middle East & Africa region remains a smaller contributor to global demand, with growth concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where rising electric vehicle imports and growing automotive testing infrastructure investment are gradually increasing component demand. South Africa continues to anchor demand on the African continent, supported by its comparatively more developed automotive assembly and testing infrastructure base.
Latin America's EV Test Equipment Market is led by Brazil, which accounts for the majority of regional demand on the strength of its growing domestic electric vehicle assembly interest and expanding automotive manufacturing sector. Gradual growth in domestic electric vehicle adoption continues to support steady regional market development.
Market Dynamics
Growth Drivers: Rising EV Production and Stricter Validation Requirements
The increasing trend of the global electric vehicles revolution is the biggest driving force behind the growing demand for the EV Test Equipment Market due to the rising manufacturing of electric vehicles, which in turn makes it essential to have a complete testing infrastructure for end-of-line and component tests at the levels of battery, inverter, charger and motor tests. These factors are supplemented by the rising demands for the validation of the fast-growing standards for charging and voltage of vehicles.
Moreover, the fast development of the chemistry of batteries and power electronics serves another substantial source of demand since car producers and Tier 1 suppliers need to have test systems that will be able to validate next-generation cars.
Restraints: High Equipment Costs and Rapid Technology Obsolescence
High upfront costs associated with comprehensive EV test equipment installations represent a significant restraint on the EV Test Equipment Market, particularly for smaller Tier 1 suppliers and testing laboratories evaluating the return on investment of specialized, capital-intensive test infrastructure. This dynamic is compounded by the rapid pace of vehicle technology advancement, which can render existing test equipment obsolete before the full useful life of the capital investment has been realized.
The technical complexity of validating increasingly diverse charging standards and high-voltage architectures requires continuous equipment upgrades and specialized technical expertise, adding cost and complexity relative to more mature automotive test equipment categories. Continued semiconductor and precision component cost volatility adds further uncertainty to long-term equipment manufacturing cost planning across the industry.
Opportunities: Modular Platform Development and Charging Standard Validation Expansion
Continued development of modular, scalable test platforms presents a substantial growth opportunity for the EV Test Equipment Market, as these designs allow OEMs and Tier 1 suppliers to expand their measurement and testing capabilities incrementally without replacing entire systems. Manufacturers that can demonstrate validated, flexible test platform architectures are well positioned to capture share as the industry increasingly prioritizes reusability and reduced total cost of ownership.
Rising complexity of global charging standards presents a longer-term opportunity for test equipment providers to expand their charging validation portfolios to serve increasingly diverse AC and DC charging protocol requirements across different regional markets. As charging infrastructure continues to evolve globally, providers with established multi-standard charging validation capabilities are positioned to capture a disproportionate share of this emerging demand.
Recent Developments:
- 2024: National Instruments unveiled a new modular test platform for electric vehicle powertrains, enabling faster validation cycles and improved integration with battery and inverter testing systems.
- 2024: Keysight Technologies announced a strategic partnership with Siemens AG to co-develop an integrated EV battery and vehicle-level test solution, combining Keysight's high-precision measurement hardware with Siemens' automation software.
- 2025: Chroma ATE secured a multi-million dollar contract to supply advanced EV battery test systems to a leading North American automaker, strengthening its position in the battery validation equipment market.
EV Test Equipment Market Key Players are:
- National Instruments Corporation
- Keysight Technologies, Inc.
- HORIBA, Ltd.
- AVL List GmbH
- TÜV Rheinland AG
- Chroma ATE Inc.
- Dürr AG
- FEV Group GmbH
- Yokogawa Electric Corporation
- Rohde & Schwarz GmbH & Co. KG
- Bosch Rexroth AG
- Siemens AG
- MTS Systems Corporation
- A&D Company, Limited
- Racelogic Ltd.
- Cincinnati Test Systems, Inc.
- ETAS GmbH
- dSPACE GmbH
- Meatest s.r.o.
- Emerson Electric Co.
EV Test Equipment Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 160.02 Million |
| Market Size by 2035 | USD 1,340.04 Million |
| CAGR | CAGR of 26.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Propulsion Type (Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, and Hybrid Electric Vehicle) • By Vehicle Type (Passenger Vehicles and Commercial Vehicles) • By Equipment Type (Powertrain, Charging, Battery, Drivetrain, Others) • By Vehicle Class (Mid-Priced, Luxury, and Economy) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | National Instruments Corporation; Keysight Technologies, Inc.; HORIBA, Ltd.; AVL List GmbH; TÜV Rheinland AG; Chroma ATE Inc.; Dürr AG; FEV Group GmbH; Yokogawa Electric Corporation; Rohde & Schwarz GmbH & Co. KG; Bosch Rexroth AG; Siemens AG; MTS Systems Corporation; A&D Company, Limited; Racelogic Ltd.; Cincinnati Test Systems, Inc.; ETAS GmbH; dSPACE GmbH; Meatest s.r.o.; Emerson Electric Co. |
Frequently Asked Questions
Leading companies in the EV Test Equipment Market include National Instruments, Keysight Technologies, HORIBA, AVL List, and TÜV Rheinland, among others.
Key opportunities include continued development of modular, scalable test platforms reducing total cost of ownership, and rising complexity of global charging standards requiring expanded validation portfolios.
The accelerating global electric vehicle revolution, combined with stricter validation requirements tied to fast-evolving charging standards and higher-voltage architectures, is the major factor driving market growth.
The Powertrain segment dominated the EV Test Equipment Market with approximately 47.00% share in 2025.
Asia Pacific dominated the EV Test Equipment Market in 2025 with approximately 42.60% share, reflecting the region's early adoption of public electric vehicles, led by China.
