
Autonomous Trucks Market Report Scope & Overview:
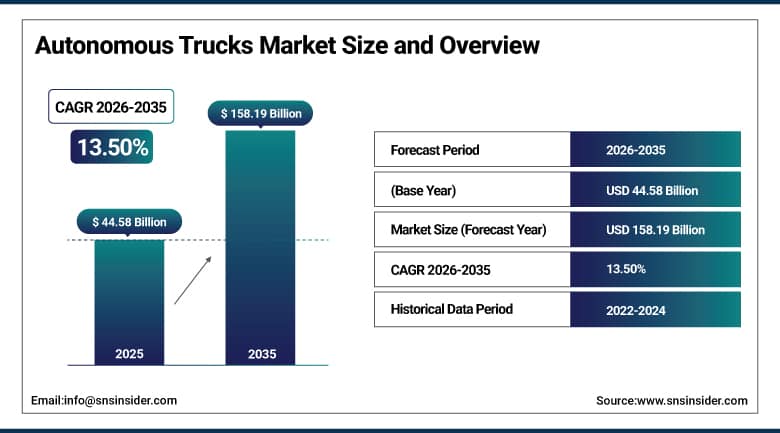
The Autonomous Trucks Market was valued at USD 44.58 Billion in 2025 and is expected to reach USD 158.19 Billion by 2035, growing at a CAGR of 13.50% from 2026-2035.
The main growth factor of the Autonomous Trucks Market comes from the persistent commercial driver shortage problem, as evidenced by the American Trucking Associations’ data that points to over 80,000 truck drivers lacking in the U.S., the number expected to reach over 160,000 in 2031 if current dynamics remain unchanged. Autonomous trucks equipped with cameras, radar, LiDAR, ultrasonic sensors, and AI-powered driving software continue to benefit from not having hours-of-service restrictions, thus allowing 24/7 operations and significantly increasing asset utilization compared to traditional trucks. Increased pressure is exerted by stricter emission norms (EPA Phase 3 greenhouse gas standards and the European Union’s Fit for 55), as well as rising e-commerce logistics demand, which makes it essential to decrease transport costs per mile. Growing investments in transport infrastructure, favorable regulatory environment, and increased OEM investments in North America, Europe, and Asia-Pacific ensure rapid market development over the next ten years.
On May 20, 2025, Aurora Innovation launched a commercial driverless trucking service between Dallas and Houston along Interstate 45, marking the first commercial self-driving service using heavy-duty Class 8 trucks operating on public roads without a human safety driver. The launch, conducted using the Aurora Driver system deployed on Volvo VNL Autonomous and PACCAR-built trucks, represents a pivotal industry milestone as autonomous trucking developers transition from extended safety-driver testing programs toward fully driverless commercial freight operations.
To Get More Information On Autonomous Trucks Market - Request Free Sample Report
Autonomous Trucks Market Trends:
-
Growing transition from extended safety-driver pilot programs toward fully commercial driverless operations.
-
Rising integration of LiDAR, radar, and high-performance computing platforms across freight and logistics fleets.
-
Continued expansion of hub-to-hub interstate corridor deployment models across major U.S. freight lanes.
-
Increasing adoption of Driver-as-a-Service subscription business models reducing upfront fleet capital costs.
-
Expanding government investment in transportation infrastructure supporting autonomous vehicle integration.
U.S. Autonomous Trucks Market Outlook:
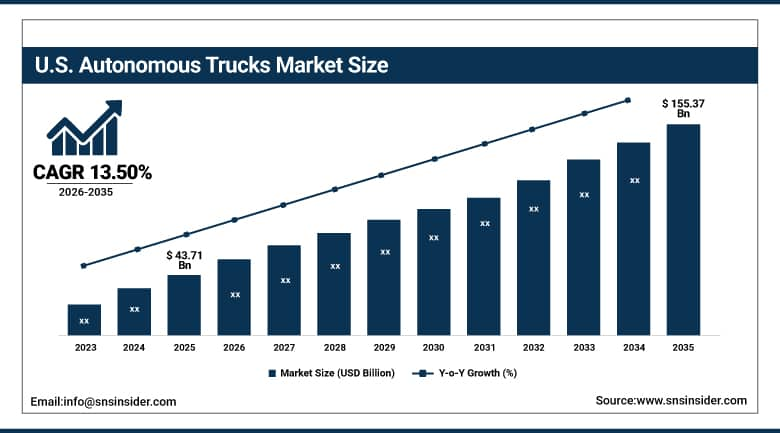
The U.S. Autonomous Trucks Market was valued at USD 43.71 Billion in 2025 and is expected to reach USD 155.37 Billion by 2035, growing at a CAGR of 13.50% from 2026-2035.
The U.S. Autonomous Trucks Market growth continues to be reinforced by favorable Sun Belt regulatory environments, continuous hub-to-hub interstate freight corridors, and the country's concentration of leading autonomous trucking developers actively conducting commercial deployments. Domestic demand also benefits from a severe and worsening commercial driver shortage that continues to make technology-assisted and driverless approaches increasingly attractive to fleet operators and logistics providers. Continued expansion of driverless commercial operations across additional interstate corridors further supports domestic market growth as autonomous trucking developers scale beyond initial launch markets toward broader national freight network coverage.
On January 15, 2025, Atlas Energy Solutions became the first customer of Kodiak Robotics to take ownership of a RoboTruck, a Class 8 semi-truck equipped with Kodiak's self-driving system, launching driverless commercial semi-truck operations across the company's private lease road network in the Permian Basin. The deployment reflects continued domestic commercialization of driverless trucking technology in controlled, lower-complexity operating environments that serve as an early testing ground for broader public roadway deployment.
Autonomous Trucks Market Segment Analysis:
-
By Vehicle Class, the Class 8/Heavy-Duty segment dominated the Autonomous Trucks Market with approximately 58.50% share in 2025, while the Class 1-5/Light-Duty segment is the fastest growing with a CAGR of approximately 19.70%.
-
By Autonomy Level, the L1 Driver-Assist segment dominated the Autonomous Trucks Market with approximately 56.50% share in 2025, while the L5 Full Autonomy segment is the fastest growing with a CAGR of approximately 24.50%.
-
By Application, the Long-Haul Freight & Logistics segment dominated the Autonomous Trucks Market with approximately 48.50% share in 2025, while the Last-Mile & Urban Delivery segment is the fastest growing with a CAGR of approximately 18.60%.
-
By Propulsion Type, the Diesel/CNG segment dominated the Autonomous Trucks Market with approximately 65.00% share in 2025, while the Battery-Electric segment is the fastest growing with a CAGR of approximately 19.80%.
-
By Sensor Type, the Camera & Radar segment dominated the Autonomous Trucks Market with approximately 54.50% share in 2025, while the LiDAR segment is the fastest growing with a CAGR of approximately 40.60%.
By Vehicle Class, Class 8/Heavy-Duty dominates and Class 1-5/Light-Duty grows fastest
Class 8 and other heavy-duty trucks account for the largest vehicle-class share of the Autonomous Trucks Market, a position tied directly to their outsized contribution to overall trucking industry operating costs across fuel, labor, and maintenance. The near-term business case for autonomy is strongest here: removing the human driver from long-haul heavy-duty operations delivers the greatest per-mile cost reduction while enabling continuous, 24/7 operation unconstrained by hours-of-service regulations. Fleet operators running Class 8 trucks also tend to have the scale and capital resources to absorb the upfront technology cost of autonomous retrofits, giving developers a customer base with both the strongest financial incentive and the greatest ability to actually invest.
Class 1-5 light-duty trucks represent the fastest-growing vehicle-class segment, as interest builds in extending autonomous technology beyond traditional long-haul freight into last-mile delivery, urban distribution, and smaller commercial applications. Adapting the technology to the more complex, unpredictable conditions of urban and suburban driving is the central engineering challenge here, but it's one that should pay off as e-commerce-driven delivery volumes keep expanding. Developers targeting this segment are increasingly partnering directly with retail and logistics companies rather than pursuing standalone technology deals, reflecting how closely light-duty autonomous delivery is tied to a specific customer's operational footprint.
By Autonomy Level, L1 Driver-Assist dominates and L5 Full Autonomy grows fastest
L1 Driver-Assist systems hold the largest share by autonomy level, reflecting the broad, established deployment of foundational advanced driver-assistance features such as adaptive cruise control and lane-keeping assistance across the existing global truck fleet. Decades of accumulated safety validation and regulatory acceptance keep this level of automation the default specification across the vast majority of new commercial trucks, even as higher autonomy levels remain earlier in their commercial journey. Fleet operators also find L1 systems the easiest to justify internally, since the safety and efficiency gains are well documented and the technology requires no meaningful change to existing driver training or operating procedures.
L5 Full Autonomy systems represent the fastest-growing autonomy level, propelled by continued technical validation of driverless commercial operations and accelerating investment from leading autonomous trucking developers pursuing fully driver-out freight operations. Eliminating the human safety driver entirely, across increasingly diverse operating conditions, is drawing disproportionate long-term investment as the industry moves from safety-driver pilot programs toward commercial-scale driverless deployment. Investors have shown a clear preference for backing developers furthest along this path, since the economic upside of fully driverless operation, freed from both driver wages and hours-of-service limits, dwarfs what partial automation levels can deliver.
By Application, Long-Haul Freight & Logistics dominates and Last-Mile & Urban Delivery grows fastest
Long-Haul Freight & Logistics remains the dominant application, underpinned by the strongest economic case for autonomy given the predictable, continuous highway conditions that define interstate freight corridors. Established hub-to-hub operating models reinforce this position, limiting autonomous trucks to well-mapped, lower-complexity highway segments while human drivers continue to handle first-mile and last-mile yard operations. This division of labor lets developers commercialize the technology today on the corridors where it works best, rather than waiting until the system can handle every driving scenario a truck might encounter.
Last-Mile & Urban Delivery is the fastest-growing application, driven by continued e-commerce expansion and rising consumer expectations for fast, reliable delivery service that demand flexible urban distribution solutions. Navigating the substantially more complex sensor and decision-making requirements of dense urban environments is the core challenge, and technology providers extending their capabilities beyond controlled highway corridors stand to capture much of this growing investment. Pedestrians, cyclists, and unpredictable traffic patterns make this a much harder engineering problem than highway driving, which is why most developers are approaching it as a distinct product rather than a simple extension of their long-haul technology.
By Propulsion Type, Diesel/CNG dominates and Battery-Electric grows fastest
Diesel and compressed natural gas propulsion systems continue to dominate by propulsion type, a reflection of how thoroughly conventional powertrains still define the existing global heavy-duty truck fleet, backed by established refueling infrastructure supporting long-haul operations. Proven range and refueling speed advantages keep this propulsion type specified across the majority of current autonomous truck deployments. Most autonomous trucking developers have also chosen to build and validate their driving systems on conventional diesel platforms first, since doing so lets them isolate the autonomy technology from the added variable of an unproven propulsion system during early commercial testing.
Battery-electric propulsion is the fastest-growing category, as tightening emissions regulations and growing fleet operator interest push toward combining autonomous operation with zero-emission propulsion. Integrating autonomous driving systems with electric drivetrain architectures suited to shorter-haul and regional distribution is where most of the engineering effort is concentrated, and demand should keep building as charging infrastructure and battery technology mature. Regional distribution routes, which return to a depot each night, are proving to be the natural starting point for electric autonomous trucks, since predictable overnight charging sidesteps the range anxiety that still limits electric trucks on longer interstate hauls.
By Sensor Type, Camera & Radar dominates and LiDAR grows fastest
Camera and radar sensor systems hold the largest share by sensor type, owing to their established, cost-effective role in enabling the foundational advanced driver-assistance features already deployed across the broader truck fleet. Mature manufacturing processes and proven reliability keep this sensor combination widely specified across both driver-assist and higher-autonomy truck platforms. These sensors also benefit from years of cost reduction driven by high-volume passenger vehicle production, giving truck manufacturers access to camera and radar hardware that's both cheaper and more reliable than it was even five years ago.
LiDAR sensors represent the fastest-growing sensor category, as continued cost declines and improving performance make high-resolution, three-dimensional environmental mapping increasingly viable for commercial deployment. The precise depth perception and object detection this technology provides is essential for higher levels of autonomy, and demand should accelerate as developers scale toward driverless operations requiring redundant, high-fidelity sensing. What was once a component costing tens of thousands of dollars per unit has fallen sharply in price over the past several years, a trend that's finally making it practical to equip commercial vehicles with the multiple LiDAR units true driverless operation requires.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
88.50% |
|
Europe |
Germany |
34.60% |
|
Asia Pacific |
China |
42.60% |
|
Latin America |
Brazil |
41.80% |
|
Middle East & Africa |
United Arab Emirates |
34.60% |
North America Autonomous Trucks Market Insights
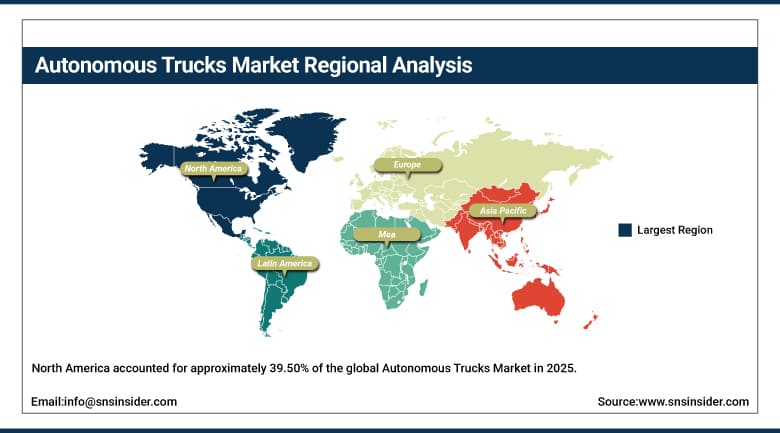
North America accounted for approximately 39.50% of the global Autonomous Trucks Market in 2025, driven by extensive highway infrastructure, progressive state-level autonomous vehicle regulations, and active commercial deployments by leading developers including Aurora Innovation and Kodiak Robotics. The United States shapes regional demand dynamics through favorable Sun Belt regulatory environments and continuous hub-to-hub interstate freight corridors well suited to early commercial autonomous truck deployment. States including Texas have become particularly attractive testing and launch markets, combining clear regulatory frameworks with the kind of long, predictable interstate corridors autonomous trucks are best suited to operate on today.
Canada contributes additional regional demand through its participation in North American freight transportation networks and cross-border logistics operations. Continued state and federal support for autonomous vehicle testing corridors further reinforces North America's position as the largest regional market for autonomous trucks. As more U.S. corridors move from pilot testing into full commercial operation, the region's early regulatory head start looks likely to keep compounding, since developers already operating profitably in Sun Belt states have less incentive to prioritize expansion elsewhere until domestic scaling is complete.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Autonomous Trucks Market Insights
Asia Pacific is projected to expand at the fastest CAGR across the Autonomous Trucks Market during the 2026-2035 forecast period, reflecting the region's increasing focus on commercial autonomous freight solutions and growing government investment in smart logistics infrastructure. China represents the largest single contributor within the region, supported by substantial domestic investment in autonomous vehicle technology and large-scale logistics infrastructure development. Chinese logistics operators are also benefiting from a regulatory environment generally more willing to greenlight large-scale commercial pilots than some Western markets, letting domestic developers accumulate real-world operating data at a faster pace.
On April 8, 2026, Hong Kong Marine Port introduced a fleet of autonomous trucks to support smarter container transportation and logistics operations, highlighting the region's growing commercial deployment momentum. Japan and South Korea contribute additional regional demand, supported by established automotive technology manufacturing bases and rising interest in autonomous freight solutions, reinforcing Asia Pacific's position as the fastest-growing global market for autonomous trucks. Port and terminal environments, being enclosed and tightly controlled compared to public roads, are emerging as one of the region's most practical near-term deployment settings for autonomous freight technology.
Europe Autonomous Trucks Market Insights
Europe represents a significant regional market for autonomous trucks, anchored by Germany's substantial commercial vehicle manufacturing base and its concentration of major truck manufacturers including Daimler Truck and MAN Truck & Bus actively investing in autonomous driving technology. Germany's share within the European market reflects both its outsized share of regional commercial vehicle production and its home-market presence of major autonomous trucking technology developers. German manufacturers are also uniquely positioned to integrate autonomous systems directly into new vehicle platforms at the factory level, rather than retrofitting existing trucks, an advantage few developers elsewhere in the world can match.
France and the Netherlands contribute additional regional demand, supported by established cross-border freight corridors and growing regulatory support for autonomous vehicle testing. Continued European Union emissions regulation under the Fit for 55 package supports steady regional demand for autonomous, zero-emission-compatible truck technology. The Netherlands' position as a major European logistics gateway, with dense cross-border freight traffic moving through its ports, gives the country an outsized role in shaping how autonomous truck regulation eventually gets harmonized across the broader European Union.
MEA & Latin America Autonomous Trucks Market Insights
Latin America's Autonomous Trucks Market is led by Brazil, which accounts for the majority of regional demand on the strength of its large domestic logistics sector and growing interest in freight efficiency technology. Gradual expansion of regional infrastructure investment continues to support steady regional market development. Brazil's vast geographic scale and heavy reliance on road freight for interior agricultural exports make efficiency-focused technology, including eventual autonomous trucking, an attractive long-term proposition for the country's largest logistics operators.
The Middle East & Africa region remains a smaller contributor to global demand, with growth concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where expanding logistics infrastructure investment and smart mobility initiatives are gradually increasing interest in autonomous freight technology. Broader regional demand remains limited relative to North America, Europe, and Asia Pacific, reflecting the technology's concentrated presence in markets with more advanced regulatory frameworks. The UAE's position as a major regional logistics hub, combined with its willingness to fund forward-looking smart mobility pilots, makes it the most likely near-term proving point for autonomous freight technology anywhere in the broader region.
Market Dynamics:
Growth Drivers: Driver Shortage and Cost-Efficiency Pressure
A chronic and worsening commercial driver shortage sits at the heart of demand for the Autonomous Trucks Market, since the persistent deficit of qualified commercial drivers keeps making technology-assisted and driverless approaches more attractive to fleet operators trying to hold onto freight capacity. Tightening emissions regulations and rapid progress in artificial intelligence and automation technology are reinforcing this trend, steadily strengthening the safety, reliability, and economic case for autonomous truck deployment. Industry groups have repeatedly flagged the driver shortage as an existential threat to freight capacity over the coming decade, a warning that continues to push more fleet operators toward seriously evaluating autonomous alternatives rather than treating the technology as a distant experiment.
Surging e-commerce freight volumes add another significant layer of demand, as logistics providers look for cost-efficient solutions that can bring down per-mile transportation costs without sacrificing delivery reliability. Growing government investment in transportation infrastructure is helping too, as authorities recognize that roadways and digital infrastructure need upgrading to safely accommodate autonomous vehicle operations. Highway departments in several states have begun piloting dedicated lane markings and digital infrastructure upgrades specifically intended to support autonomous truck operations, a sign that public infrastructure planning is starting to treat the technology as a near-term reality rather than a hypothetical.
Restraints: Safety Validation and Regulatory Fragmentation
Winning consumer and industry confidence remains one of the toughest hurdles facing the Autonomous Trucks Market, since overcoming public safety concerns takes a demonstrated track record of safety, transparent testing, and successful commercial deployments before broader adoption can really take off. That's kept fully driverless commercial deployment confined to a small number of well-mapped, lower-complexity corridors, even after years of extensive safety-driver testing. A single high-profile incident involving an autonomous truck could set the entire industry's public perception back significantly, which is why leading developers continue to prioritize extensive safety-driver testing even when the underlying technology is technically ready for driverless operation.
Regulatory fragmentation across different states and countries adds another layer of difficulty, since commercial operation authorization and safety certification requirements vary meaningfully from one jurisdiction to the next. High technology development and sensor system costs compound the challenge further, particularly for smaller fleet operators still weighing whether autonomous truck adoption pencils out. A developer cleared to operate driverless trucks in one state may need to restart much of that certification process to expand into a neighboring one, a patchwork that continues to slow how quickly successful pilot programs can scale into truly national operations.
Opportunities: Driver-as-a-Service Models and Urban Delivery Expansion
Driver-as-a-Service subscription business models represent a substantial growth opportunity here, since converting hefty upfront capital expenditures into scalable operational subscription fees meaningfully lowers the adoption barrier for fleet operators. Technology providers able to demonstrate validated, cost-competitive subscription models are well positioned to win share as smaller and mid-sized fleet operators warm up to autonomous truck adoption. This model also gives technology providers a recurring revenue stream instead of a one-time hardware sale, aligning their incentives with keeping the underlying autonomous system reliably operational over the long run rather than simply shipping a product and moving on.
Extending autonomous technology into last-mile and urban delivery applications offers developers a longer-term path to grow beyond the traditional long-haul, hub-to-hub operating model most autonomous trucks rely on today. As sensor technology and AI-based driving software keep maturing, technology providers with established urban navigation capabilities stand to capture a disproportionate share of this emerging demand. Developers who successfully crack the urban delivery problem will also have built a technology stack transferable to an even broader range of applications, from robotaxis to smaller delivery robots, giving early movers here a real platform advantage beyond trucking alone.
Recent Developments:
-
On October 30, 2025, Aurora Innovation announced the launch of a second driverless route between Fort Worth and El Paso, surpassing 100,000 driverless miles on public roads and outlining plans to deploy hundreds of driverless trucks using its next-generation Aurora Driver hardware beginning in 2026.
-
On April 8, 2026, Hong Kong Marine Port introduced a fleet of autonomous trucks to support smarter container transportation and logistics operations, reflecting growing commercial autonomous freight deployment across the Asia Pacific region.
Autonomous Trucks Market Key Players:
-
Waymo LLC
-
Aurora Innovation, Inc.
-
Daimler Truck Holding AG
-
AB Volvo
-
Tesla, Inc.
-
Continental AG
-
Kodiak Robotics, Inc.
-
Plus (PlusAI, Inc.)
-
Einride AB
-
Nuro, Inc.
-
Gatik AI, Inc.
-
PACCAR Inc.
-
Scania AB
-
MAN Truck & Bus SE
-
Ford Motor Company
-
Torc Robotics, Inc.
-
Robert Bosch GmbH
-
NVIDIA Corporation
-
Waabi Innovation Inc.
-
Bot Auto, Inc.
Autonomous Trucks Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 44.58 Billion |
| Market Size by 2035 | USD 158.19 Billion |
| CAGR | CAGR of 13.50% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Vehicle Class (Class 8/Heavy-Duty, Class 6-7/Medium-Duty, and Class 1-5/Light-Duty) • by Autonomy Level (L1 Driver-Assist, L2/L3 Partial Automation, L4 Highway Autonomy, and L5 Full Autonomy) • by Application (Long-Haul Freight & Logistics, Last-Mile & Urban Delivery, Mining & Off-Highway, and Port & Terminal Operations) • by Propulsion Type (Diesel/CNG, Battery-Electric, and Hydrogen Fuel Cell) • by Sensor Type (Camera & Radar, LiDAR, and Ultrasonic) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Waymo LLC, Aurora Innovation, Inc., Daimler Truck Holding AG, AB Volvo, Tesla, Inc., Continental AG, Kodiak Robotics, Inc., Plus (PlusAI, Inc.), Einride AB, Nuro, Inc., Gatik AI, Inc., PACCAR Inc., Scania AB, MAN Truck & Bus SE, Ford Motor Company, Torc Robotics, Inc., Robert Bosch GmbH, NVIDIA Corporation, Waabi Innovation Inc., Bot Auto, Inc. |
Frequently Asked Questions
Leading companies in the Autonomous Trucks Market include Waymo, Aurora Innovation, Daimler Truck, AB Volvo, and Kodiak Robotics, among others.
Key opportunities include continued development of Driver-as-a-Service subscription business models, and rising interest in extending autonomous technology to last-mile and urban delivery applications.
The chronic and worsening commercial driver shortage, combined with tightening emissions regulations and rapid AI and automation advancement, is the major factor driving market growth.
The Diesel/CNG segment dominated the Autonomous Trucks Market with approximately 65.00% share in 2025.
North America dominated the Autonomous Trucks Market in 2025 with approximately 39.50% share, driven by extensive highway infrastructure and progressive state-level regulations, led by the United States.
