
Flip Chip Market Report Scope & Overview:
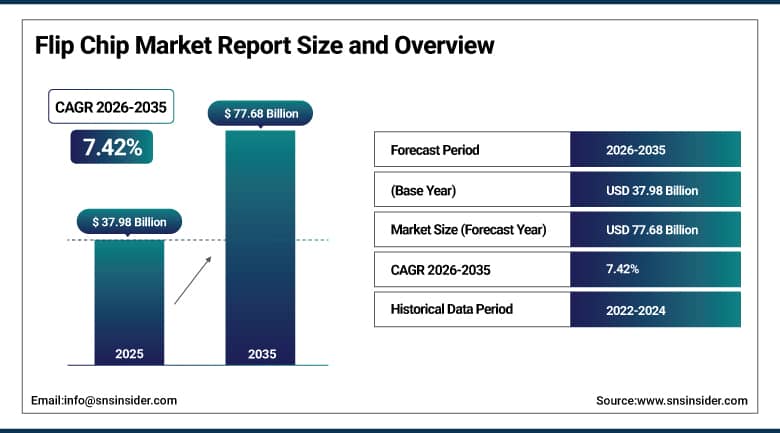
The Flip Chip Market size was valued at USD 37.98 Billion in 2025 and is expected to reach USD 77.68 Billion by 2035, growing at a CAGR of 7.42% from 2026-2035.
Flip Chip Market is expanding owing to rising needs for semiconductor packaging technologies in consumer electronics, automobiles, telecommunication systems, and computing systems. With an increase in the use of smartphones, wearable electronics, IoT products, artificial intelligence, and data center systems, there will be an increased need for smaller and high-performance chips with good electrical and thermal properties. Flip chip technology offers shorter connections, input/output density, electrical performance, and heat dissipation as compared to the traditional process of wire bonding. Growing investment in the production of semiconductors, especially in the Asia-Pacific region, will help in driving the market's growth.
⮞By the end of 2025, TSMC aimed to scale its Chip on Wafer on Substrate advanced packaging capacity to roughly 75,000 wafers per month, with plans to expand further toward 120,000 to 130,000 wafers monthly by the end of 2026. The company said current capacity remains sold out through 2026, reflecting AI GPU and ASIC customer demand that continues to substantially exceed available advanced packaging supply across the industry.
To Get More Information On Flip Chip Market - Request Free Sample Report
Flip Chip Market Trends
-
Rising adoption of copper-to-copper hybrid bonding supporting sub-5-micron interconnect pitch requirements.
-
Growing outsourcing of advanced packaging steps from leading foundries to established OSAT partners.
-
Expanding use of 2.5D interposer packaging supporting high-bandwidth memory integration for AI accelerators.
-
Increasing government semiconductor incentive investment supporting domestic advanced packaging capacity build-out.
-
Rising demand for flip chip interconnects across automotive electronics and high-performance computing applications.
U.S. Flip Chip Market Size Outlook
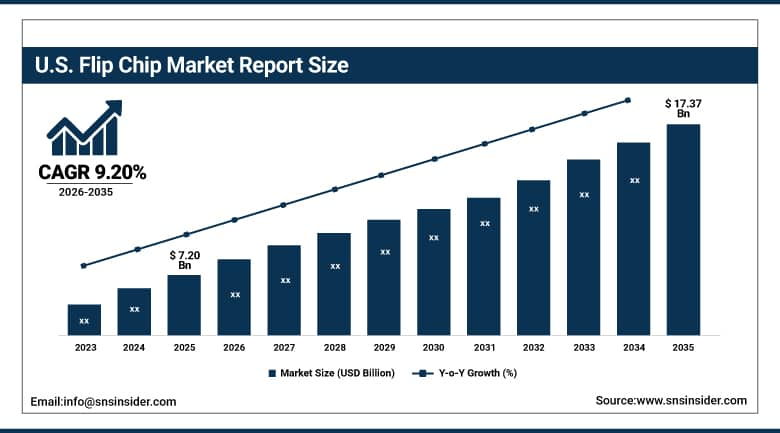
The U.S. Flip Chip Market was valued at USD 7.20 Billion in 2025 and is expected to reach USD 17.37 Billion by 2035, growing at a CAGR of 9.20% from 2026-2035.
Domestic demand continues to be reinforced by strong research and development investment, accelerating AI accelerator and high-performance computing deployment, and sustained government incentive support for onshore advanced packaging capacity. Leading domestic technology companies continue securing multi-year advanced packaging capacity commitments from both foundries and outsourced assembly and test partners, reflecting the strategic importance domestic customers now place on packaging supply security alongside chip design leadership.
⮞In 2025, Amkor Technology continued progressing its USD 2 billion advanced packaging facility in Peoria, Arizona, developed in coordination with a memorandum of understanding with TSMC under which Amkor packages chips for the foundry's leading customers. The facility reinforces domestic advanced packaging capacity as demand from AI accelerator and high-performance computing customers continues to substantially outstrip available global supply.
Flip Chip Market Segment Analysis
-
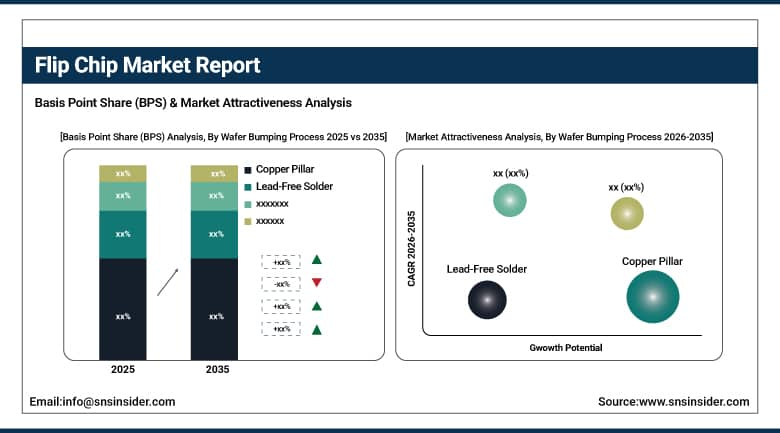
By Wafer Bumping Process, Copper Pillar segment dominated the Flip Chip Market in 2025 with 48% share; Lead-Free Solder segment is the fastest growing segment.
-
By Packaging Type, FC-BGA segment dominated the market in 2025 with 46% share; FC-SiP segment is the fastest growing segment.
-
By End-Use Industry, Consumer Electronics segment dominated the market in 2025 with 39% share; Automotive segment is the fastest growing segment.
By Wafer Bumping Process, Copper Pillar Dominates Flip Chip Market; Lead-Free Solder to Register Fastest Growth
The Copper Pillar holds the largest market share in the Flip Chip Market owing to its excellent electrical and thermal conductivity, fine pitch interconnects, and high-density semiconductor packaging. With a lower electrical resistance and current-carrying capacity, copper pillars are ideal for processors, application specific integrated circuits, power devices, and other high-performance chips. Copper pillar technology enables thin packaging and enhanced reliability when compared to traditional solder bump interconnect technologies. Increasing demand for improved performance of processors, miniaturization, and semiconductor packaging is driving the demand for copper pillars in flip chip applications.
The Lead-Free Solder is projected to be the fastest growing segment in the global flip chip market driven by the adoption of environmentally friendly packaging materials and compliance with the restrictions on hazardous substances in semiconductor packaging material. Lead-free solder bumps offer excellent manufacturing compatibility and reliable electrical interconnects in a wide variety of flip-chip applications. Increasing environmental regulations and sustainability initiatives are pushing manufacturers to switch to lead-free materials.
By Packaging Type, FC-BGA Dominates Flip Chip Market; FC-SiP to Register Fastest Growth
FC-BGA is a leader in the Flip-Chip market owing to its high interconnection density, electrical efficiency, and good thermal management for semiconductor devices that require more power. It is commonly used in processors, graphics devices, chipsets, networking devices, and any other application that requires more interconnection capabilities. This packaging type can support large die sizes and high pin counts due to its ability to satisfy the needs of advanced computing. High-performance computing, artificial intelligence, data centers, and advanced consumer electronics continue to increase the demand for this packaging.
FC-SiP will grow at the fastest rate due to the increasing trend of integrating multiple dies, components, and functional blocks into small packages. The use of flip-chip system-in-package architectures helps to minimize package size while enhancing electrical performance and shortening the interconnection paths. Increasing demand for smaller and multifunctional electronic devices will drive the usage of FC-SiP in mobile electronics, wearables, connectivity devices, and many other applications where there is a need for miniaturization and functionality.
By End-Use Industry, Consumer Electronics Dominates Flip Chip Market; Automotive to Register Fastest Growth
Consumer Electronics drives the Flip Chip Market because there is a need for high-end semiconductor packages due to shrinking form factors in smartphones, tablets, wearables, gaming, and other electronic devices. Flip chip allows for shorter interconnects, denser packaging, and good electrical and thermal performance that facilitates the production of smaller and more powerful electronics. Increasing innovation and functionalities in consumer electronics continuously drive the demand for advanced semiconductor packaging. The rise in the use of processors, connectivity chips, graphics chips, and application-specific chips will help the segment dominate the market.
The Automotive segment will witness the highest growth owing to the increasing use of semiconductors in vehicles for advanced driver assistance, infotainment, connectivity, electrification, and automated driving features. These applications have the need for semiconductor packages with excellent performance in processing and thermal management in small form factors. With an increase in the adoption of electric cars and software-defined architecture in cars, the semiconductor content per vehicle is increasing, hence driving the demand for semiconductor packaging.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|
Asia Pacific |
Taiwan |
41.20% |
|
North America |
United States |
84.60% |
|
Europe |
Germany |
26.80% |
|
Latin America |
Brazil |
24.60% |
|
Middle East & Africa |
United Arab Emirates |
22.60% |
Asia Pacific Flip Chip Market Insights
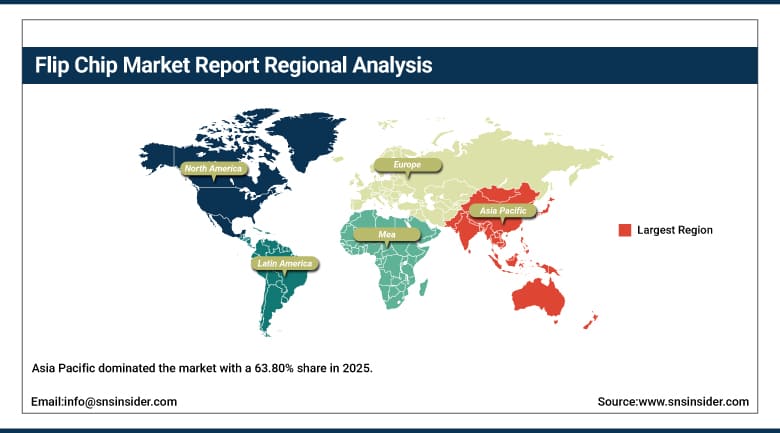
Asia Pacific dominated the market with a 63.80% share in 2025. The region's concentration of leading foundries and outsourced semiconductor assembly and test providers, particularly across Taiwan and China, continues to anchor this leadership position, supported by decades of accumulated advanced packaging manufacturing expertise and sustained capital investment in expanding wafer-level packaging capacity to meet surging AI accelerator demand.
Taiwan continues to command the largest share within the region, hosting the world's leading advanced packaging foundry alongside major outsourced assembly and test providers pursuing aggressive capacity expansion. China's rapidly growing domestic packaging sector, Japan's established semiconductor materials and equipment industry, and South Korea's leading memory manufacturers contribute further regional depth, reinforcing Asia Pacific's position as the largest market for flip chip packaging through the forecast period.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Flip Chip Market Insights
North America is projected to be the fastest-growing region, registering a CAGR of 9.20% during 2026-2035. Strong research and development investment, accelerating AI accelerator deployment, and substantial government semiconductor incentive programs continue to drive sustained domestic advanced packaging capacity expansion. The United States continues to host leading chip designers whose surging AI infrastructure demand continues to anchor regional packaging capacity investment.
Continued government incentive support for domestic semiconductor manufacturing, including advanced packaging facility investment across Arizona, Ohio, and Texas, continues to reinforce North America's accelerating growth trajectory. Canada and Mexico contribute additional regional demand as their own electronics manufacturing sectors continue to develop, positioning North America as the fastest-growing regional market through the forecast period.
Europe Flip Chip Market Insights
Europe represents a meaningful share of the global market, supported by the region's own semiconductor sovereignty programs and established automotive electronics manufacturing base. Germany's substantial automotive and industrial electronics sector continues to anchor regional demand, reinforced by increasing flip chip adoption across advanced driver-assistance systems and electric vehicle power electronics.
France, the Netherlands, and other major European semiconductor markets contribute consistent demand as regional chipmakers continue extending advanced packaging adoption. Continued European Union investment in semiconductor manufacturing sovereignty is expected to sustain steady regional growth through the forecast period, even as the region trails both Asia Pacific and North America in overall market scale.
MEA & Latin America Flip Chip Market Insights
The Middle East & Africa market remains comparatively modest, with growing electronics assembly and telecommunications infrastructure investment across the United Arab Emirates and Saudi Arabia gradually supporting regional demand for advanced semiconductor packaging.
Latin America's market is anchored by Brazil, where a developing domestic electronics manufacturing sector sustains gradual demand growth. Mexico contributes further incremental growth as regional electronics assembly continues to expand alongside broader nearshoring-driven manufacturing investment across the country.
Market Dynamics
Growth Drivers: AI Accelerator Demand and Heterogeneous Integration
Increasing demand for AI accelerators, GPU, high-performance computing systems, and processors used in the data center will drive the Flip Chip Market since today’s semiconductor designs are becoming increasingly complicated and demand more interconnect density, higher speed signal transfers, and effective heat management solutions.
Flip chip allows using shorter electrical connections, higher input/output density and provides better performance in comparison with traditional wire bonding and therefore is perfect for advanced computer architecture. Moreover, increasing use of heterogeneous integration will boost demand since companies are integrating multiple dies, chiplets, memory, and special processors in single packages. Increased production of semiconductors for artificial intelligence, cloud computing, consumer electronics, and edge computing will increase demand for packaging solutions. Moreover, increased usage of electric cars, ADAS, 5G, and connected devices will create additional application areas for flip chip packaging.
Restraints: Advanced Packaging Capacity Constraints and High Capital Costs
The shortage of advanced packaging capacity is one of the major restraints to the development of the Flip Chip Market due to competition between semiconductor manufacturers for available advanced packaging capacity. Increased demand for processors for AI and GPUs, high bandwidth memory and other advanced semiconductors requires more advanced packaging capacity and the availability of such capacity limits production and can increase lead times for customers.
High investments associated with advanced packaging capacity is another problem that faces manufacturers as the creation of advanced packaging facilities requires a lot of investments in the construction of clean room facilities and the purchase of equipment, testing and control system. Such problems may affect small companies' ability to invest in advanced packaging and limit capacity expansion. The need for continuous innovations in packaging technologies is also very expensive for manufacturers.
Opportunities: Hybrid Bonding Innovation and OSAT Capacity Expansion
Innovations in hybrid bonding technology offer a major opportunity for the Flip Chip Market because semiconductor producers look for more refined interconnect pitches, increased bandwidths, and enhanced chip-to-chip connections. Hybrid bonding allows for direct connections between semiconductor surfaces and even three-dimensional integration, chiplet design, and fast memory devices. Improvements in such aspects as precise bonding, reliability of the process, high alignment accuracy, and yields may drive its adoption in future generations of semiconductor packaging. In addition, growth in outsourcing of semiconductor assembly and testing facilities may bring in new opportunities for semiconductor producers looking for external partners to meet their packaging needs.
New facilities with the necessary equipment and packaging capabilities are being developed by OSAT companies to respond to the increased needs of AI, automotive, telecom, and consumer electronics clients. Geographic diversification of packaging facilities may also help in securing the supply chain and decreasing dependency on the particular regions of production.
Recent Developments:
-
In May 2025, Samsung Electronics powered its Galaxy Z Flip 7 with an in-house Exynos 2500 chipset, marking the first use of an Exynos processor in a foldable device in place of the previously expected Snapdragon chip.
-
In May 2025, MediaTek's next-generation flagship system-on-chip and Arm-based processors helped drive a year's worth of packaging tool orders for ASE Group within a single quarter.
-
In December 2025, TSMC transferred a portion of its advanced packaging orders to outsourced semiconductor assembly and test partners ASE and Amkor rather than allowing customer orders to flow to Samsung Electronics, its largest packaging competitor.
-
In 2025, Amkor Technology introduced Intel's EMIB packaging process across its manufacturing plants in South Korea, Portugal, and Arizona, expanding the range of advanced packaging technologies available across its global facility network.
Flip Chip Companies are:
-
Advanced Semiconductor Engineering, Inc. (ASE Group)
-
Intel Corporation
-
Amkor Technology, Inc.
-
Samsung Electronics Co., Ltd.
-
STATS ChipPAC Pte. Ltd.
-
GlobalFoundries Inc.
-
Texas Instruments Incorporated
-
United Microelectronics Corporation
-
STMicroelectronics N.V.
-
Nepes Corporation
-
Palomar Technologies, Inc.
-
Flip Chip International, LLC
-
Micron Technology, Inc.
-
SK Hynix Inc.
-
Applied Materials, Inc.
-
ASML Holding N.V.
-
JCET Group Co., Ltd.
-
Broadcom Inc.
Flip Chip Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 37.98 Billion |
| Market Size by 2035 | USD 77.68 Billion |
| CAGR | CAGR of 7.42% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Wafer Bumping Process (Copper Pillar, Lead-Free Solder, Tin-Lead Solder, Gold Stud Bump) • By Packaging Type (FC-BGA, FC-QFN, FC-CSP, FC-SiP) • By End-Use Industry (Consumer Electronics, Telecommunications, Automotive, Industrial, Medical & Healthcare, Military & Aerospace) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Taiwan Semiconductor Manufacturing Company, Advanced Semiconductor Engineering, Inc. (ASE Group), Intel Corporation, Amkor Technology, Inc., Samsung Electronics Co., Ltd., STATS ChipPAC Pte. Ltd., Powertech Technology Inc., GlobalFoundries Inc., Texas Instruments Incorporated, United Microelectronics Corporation, STMicroelectronics N.V., Nepes Corporation, Palomar Technologies, Inc., Flip Chip International, LLC, Micron Technology, Inc., SK Hynix Inc., Applied Materials, Inc., ASML Holding N.V., JCET Group Co., Ltd., Broadcom Inc. |

Frequently Asked Questions
Key players include Taiwan Semiconductor Manufacturing Company, ASE Group, Intel Corporation, Amkor Technology, Inc., and Samsung Electronics Co., Ltd., among other semiconductor manufacturers and packaging providers.
Continued advancement of hybrid bonding technology and continued expansion of outsourced assembly and test capacity represent the primary opportunities for providers.
Growth is primarily driven by rising demand for AI accelerators, GPUs, and high-performance computing devices, combined with growing adoption across automotive and telecommunications applications.
By Wafer Bumping Process, Copper Pillar dominated the market in 2025.
Asia Pacific dominated the market with a 63.80% share in 2025, supported by the region's concentration of leading foundries and outsourced assembly providers.
