
Thermal Interface Materials Market Report Scope & Overview:
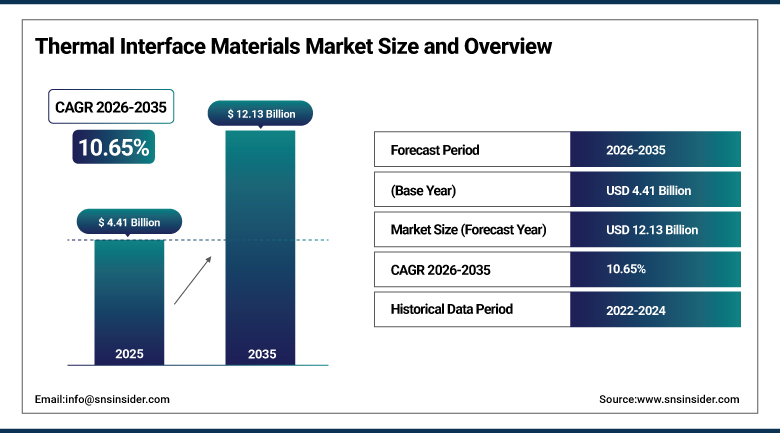
The Thermal Interface Materials Market was valued at USD 4.41 Billion in 2025 and is expected to reach USD 12.13 Billion by 2035, growing at a CAGR of 10.65% from 2026-2035.
Thermal Interface Materials Market is mainly getting fueled by accelerated growth in AI-enabled data center facilities that keep pushing processors and servers into new extremes of power density, forcing the usage of ever more complex thermal interface materials for effective cooling between these devices and heat sinks. With electronics becoming smaller and more compact, efficient use of thermal interface materials to eliminate any air gaps and optimize heat dissipation becomes increasingly important. Electric vehicle growth drives the need for thermal interface materials as the battery packs and power electronics generate significant amounts of heat that need proper management in order to maintain performance and safety of such systems.
In October 2025, Henkel unveiled a new thermal interface material formulation delivering 14.5 W/m-K thermal conductivity, specifically engineered for high-power-density optical transceivers used in AI data centers, including coherent optical modules.
To Get more information Thermal Interface Materials Market - Request Free Sample Report
Thermal Interface Materials Market Trends
- Rapid growth of AI-powered data center infrastructure driving demand for high-conductivity thermal materials.
- Increasing adoption of phase change materials for high-performance computing and power module applications.
- Growing use of aligned carbon nanotube and advanced filler technology to improve thermal conductivity.
- Rising demand for battery and power electronics thermal management across electric vehicle platforms.
- Continued development of silicone-based and low-stress formulations for high-power, demanding electronics environments.
U.S. Thermal Interface Materials Market Outlook
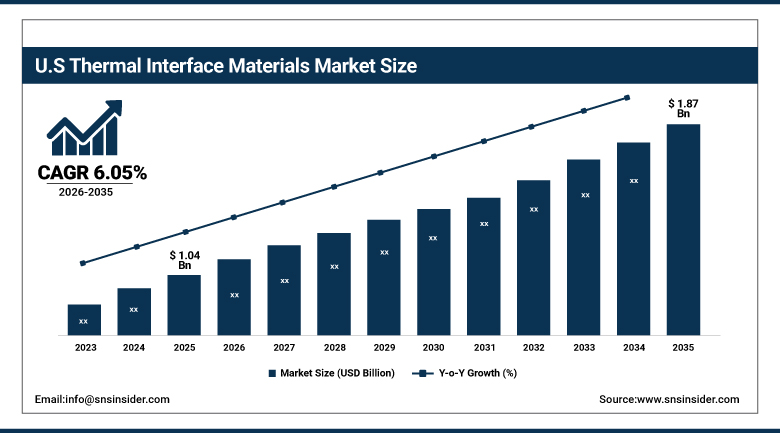
The U.S. Thermal Interface Materials Market was valued at USD 1.04 Billion in 2025 and is expected to reach USD 1.87 Billion by 2035, growing at a CAGR of 6.05% from 2026-2035.
The growth of the U.S. Thermal Interface Material Market is further buttressed by significant investments in AI-enabled data centers infrastructure in the home market, increasing power electronics in electric vehicles, and the country's presence of leading thermal interface material suppliers and specialty chemicals producers. The growth in the domestic demand is also supported by the increase in aerospace, defense, and advanced electronics manufacturing industries, where high-quality thermal management solutions are required. Increased investments in domestic semiconductor packaging and computing infrastructure are additional drivers for the demand for the new generation of thermal interface materials.
In October 2024, Dow announced a strategic partnership with Carbice to introduce multi-generational thermal interface materials using aligned carbon nanotube technology for industrial, consumer, mobility, and semiconductor applications.
Thermal Interface Materials Market Segment Analysis
- By Product Type, the Greases & Adhesives segment dominated the Thermal Interface Materials Market with approximately 37.50% share in 2025, while the Phase Change Materials segment is the fastest growing with a CAGR of approximately 12.40%.
- By Application, the Computer segment dominated the Thermal Interface Materials Market with approximately 27.00% share in 2025, while the Data Center & Telecom segment is the fastest growing with a CAGR of approximately 13.10%.
By Product Type, Greases & Adhesives dominates and Phase Change Materials grows fastest
Greases & Adhesives are the prevailing type of products being marketed in the Thermal Interface Materials Market due to their efficient thermal conductivity and adhesive properties that still continue making them the preferred specifications for use in many electronic cooling applications. Greases & Adhesives take advantage of low-cost production methods and their long-term reliability across computing, consumer electronics, and industrial applications where wet application is advantageous.
The fastest growing type of products is Phase Change Materials because of their capacity to undergo a change from solid state into a state with better conformability under operating conditions thus ensuring good contact and thermal stability even through numerous thermal cycles. This type of products caters to high-performance computing modules and power dense electronics applications where good thermal resistance is more important than application ease.
By Application, Computer dominates and Data Center & Telecom grows fastest
Computer applications remain the dominant application segment within the Thermal Interface Materials Market, reflecting the substantial heat generated by high-performance processors and graphics processing units that require effective, reliable thermal management to maintain performance and prevent component degradation. This segment benefits from decades of accumulated thermal material engineering experience built specifically around central processing unit and graphics processing unit cooling requirements.
Data Center & Telecom applications are emerging as the fastest-growing application segment, driven by rapid expansion of AI-powered data center infrastructure that continues to push server and network equipment power densities to unprecedented levels. This segment focuses on high-conductivity formulations engineered for optical transceivers, network switches, and high-density server racks, positioning data center and telecom applications to capture a rapidly growing share of overall thermal interface material demand as AI infrastructure investment continues to accelerate globally.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
52.60% |
|
North America |
United States |
80.00% |
|
Europe |
Germany |
34.60% |
|
Latin America |
Brazil |
44.90% |
|
Middle East & Africa |
United Arab Emirates |
28.60% |
Asia Pacific Thermal Interface Materials Market Insights
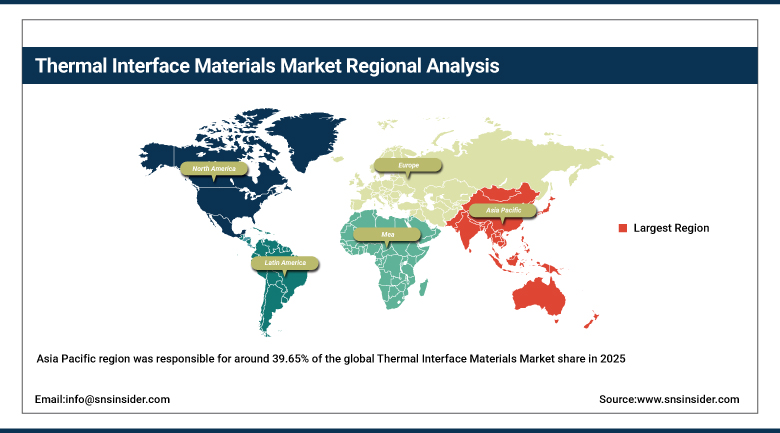
The Asia Pacific region was responsible for around 39.65% of the global Thermal Interface Materials Market share in 2025 and is also expected to grow at the fastest rate in the coming years, between 2026 and 2035. This is due to the presence of robust electronics manufacturing industry along with global semiconductor and consumer devices manufacturing activities.
China is the biggest contributor in the region due to the presence of strong electronics manufacturing ecosystem along with increasing domestic data centers and EVs production. Japan and South Korea are also playing an important role in regional consumption of Thermal Interface Materials owing to decades of expertise in semiconductor packaging materials. The increasing investments in AI infrastructure and production of electric vehicles is fueling the growth of the market in the region.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Thermal Interface Materials Market Insights
North America represents a significant regional market for thermal interface materials, supported by substantial investments in AI-driven data center infrastructure and a strong presence of thermal management technology developers. The United States accounts for the majority of regional demand, reflecting its extensive data center construction activity and concentration of companies developing advanced thermal interface materials and specialty chemicals for high-performance computing applications.
Canada and Mexico contribute additional regional demand through electronics manufacturing, industrial applications, and integrated cross-border supply chains. Continued expansion of aerospace, defense, telecommunications, and advanced computing applications is further supporting demand for high-performance thermal management materials. Growing requirements for efficient heat dissipation in increasingly compact and power-intensive electronic systems are creating additional opportunities across the region.
Europe Thermal Interface Materials Market Insights
Europe represents a meaningful regional market for thermal interface materials, anchored by Germany’s strong automotive and industrial electronics manufacturing base and its established specialty chemicals and advanced materials industry. Germany contributes substantial regional demand due to its large automotive production ecosystem and presence of companies developing thermal management materials. Increasing adoption of electric vehicles, power electronics, and high-performance computing is further supporting demand for efficient thermal solutions.
The United Kingdom, France, Italy, and Spain contribute additional demand through automotive, electronics, industrial automation, and energy-related applications. Growing investments in vehicle electrification and advanced electronic systems are increasing requirements for reliable heat dissipation and thermal management. Continued development of electric mobility, industrial automation, and increasingly compact electronic components is expected to sustain regional demand for high-performance thermal interface materials.
MEA & Latin America Thermal Interface Materials Market Insights
Latin America’s Thermal Interface Materials Market is led by Brazil, which accounts for a substantial portion of regional demand, supported by its expanding electronics assembly, automotive manufacturing, and industrial sectors. Gradual development of domestic consumer electronics production and increasing automotive manufacturing activity are creating steady requirements for thermal management solutions. Growing adoption of electronic components and electrified vehicle technologies is further supporting regional market development.
The Middle East & Africa region remains a smaller contributor to global Thermal Interface Materials demand, with growth concentrated in Gulf Cooperation Council markets such as the United Arab Emirates. Expanding data center, telecommunications, and technology infrastructure investments are gradually increasing demand for thermal management components. South Africa continues to represent an important African market, supported by its relatively developed electronics, telecommunications, and industrial sectors.
Market Dynamics
Growth Drivers: AI Data Center Expansion and Electric Vehicle Adoption
The rapid development of data center infrastructure driven by Artificial Intelligence will be the key factor driving the Thermal Interface Materials Market due to the need for better heat dissipation methods amid growing density of processors and servers. This trend is augmented by the rapid proliferation of electric vehicles in which high-power battery packs and lighter construction material will bring about a paradigm shift in terms of thermal management needs.
Further development of fifth generation wireless technology and proliferation of renewable energy sources create another strong source of demand, as both types of technologies need effective thermal management components to preserve their performance. Innovation in the field of medical devices and increased use of automation processes in the pharmaceutical and industrial production industries create another strong impetus for market growth.
Restraints: Raw Material Cost Volatility and Formulation Complexity
The continued volatility of the prices of specialty filler compounds, such as boron nitride, aluminum nitride, and silver metal fillers, is an important constraint on the market of Thermal Interface Materials as it has a direct impact on the production and pricing of the materials. The challenge is even more pronounced when it comes to high-performance products where the use of costly advanced fillers ensures high thermal conductivity.
The technical difficulty involved in formulating products that combine thermal conductivity, flexibility, and durability under extremely diverse conditions slows down the process of innovation, especially for the challenging segments, like the optical transceivers for AI data centers.
Opportunities: AI Infrastructure Cooling and Electric Vehicle Thermal Management Expansion
The sustained and rapid expansion in the growth of infrastructure such as data centers and high-performance computing infrastructure based on AI technology provides a great potential for growth in the Thermal Interface Materials Market, as these use high conductivity materials that are able to handle high power density levels. Companies that have the capability of offering validated high performance thermal products for future computing infrastructure based on AI technology can gain a competitive edge.
Increasing demands for electric vehicle battery and power electronics thermal management is a potential long-term market opportunity for companies to expand their product range into automotive thermal interface materials. As production of electric vehicles is expanding in the global market, companies that have a proven track record of validating automotive materials can gain a disproportionate share of this growing market.
Recent Developments:
- 2025: Wacker Chemie AG introduced new silicone-based thermal interface materials designed to improve heat flow in electronics and vehicles, strengthening Europe's position in advanced thermal management solutions.
- 2025: 3M launched THERM-A-GAP GEL 120, a dispensable thermal gap filler gel positioned as a high-conductivity choice for demanding electronics cooling applications.
Thermal Interface Materials Market Key Players are:
- Honeywell International Inc.
- 3M Company
- Henkel AG & Co. KGaA
- Parker Hannifin Corporation
- Shin-Etsu Chemical Co., Ltd.
- Momentive Performance Materials Inc.
- Wakefield-Vette, Inc.
- Indium Corporation
- Panasonic Corporation
- Arctic Silver, Inc.
- Fujipoly America Corporation
- Master Bond Inc.
- Dow Inc.
- Laird Performance Materials
- DuPont de Nemours, Inc.
- Boyd Corporation
- Kitagawa Industries Co., Ltd.
- Zalman Tech Co., Ltd.
- Wacker Chemie AG
- T-Global Technology Co., Ltd.
Thermal Interface Materials Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.41 Billion |
| Market Size by 2035 | USD 12.13 Billion |
| CAGR | CAGR of 10.65% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Greases & Adhesives, Phase Change Materials, Pads & Gap Fillers, Tapes & Films, Metal-Based, Others) • By Application (Computer, Data Center & Telecom, Automotive, Consumer Electronics, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Honeywell International Inc.; 3M Company; Henkel AG & Co. KGaA; Parker Hannifin Corporation; Shin-Etsu Chemical Co., Ltd.; Momentive Performance Materials Inc.; Wakefield-Vette, Inc.; Indium Corporation; Panasonic Corporation; Arctic Silver, Inc.; Fujipoly America Corporation; Master Bond Inc.; Dow Inc.; Laird Performance Materials; DuPont de Nemours, Inc.; Boyd Corporation; Kitagawa Industries Co., Ltd.; Zalman Tech Co., Ltd.; Wacker Chemie AG; T-Global Technology Co., Ltd. |
Frequently Asked Questions
Leading companies in the Thermal Interface Materials Market include Honeywell International, 3M, Henkel, Parker Hannifin, and Shin-Etsu Chemical, among others.
Key opportunities include continued rapid expansion of AI-powered data center and high-performance computing infrastructure, and growing electric vehicle battery and power electronics thermal management requirements.
Rapid expansion of AI-powered data center infrastructure combined with rising processor and server power densities, alongside rapid electric vehicle adoption, is the major factor driving market growth.
The Greases & Adhesives segment dominated the Thermal Interface Materials Market with approximately 37.50% share in 2025.
Asia Pacific dominated the Thermal Interface Materials Market in 2025 with approximately 39.65% share, reflecting the region's strong electronics manufacturing base, led by China.
