
Frozen Seafood Packaging Market Report Scope & Overview:
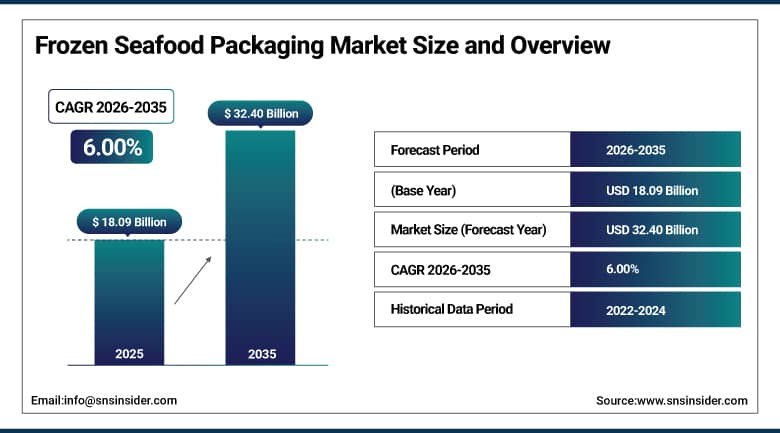
The Frozen Seafood Packaging Market was valued at USD 18.09 Billion in 2025 and is expected to reach USD 32.40 Billion by 2035, growing at a CAGR of 6.00% from 2026 to 2035.
The market for frozen seafood packaging products is showing steady growth, due to increasing global demand for seafood products, expanding cold chain logistics, and the increasing trend towards consuming long shelf life protein sources as compared to fresh sources. The growing consumer awareness regarding food safety and preserving freshness is leading to the adoption of advanced barrier films, vacuum packaging, and modified atmosphere packaging, which help delay lipid oxidation, freezer burns, and bacteria. Growing seafood distribution channels in combination with increased seafood trade from major exporter countries is driving demand for packaging in developed and developing countries. Apart from that, the increasing trend towards recyclable and lighter packaging formats along with investments in intelligent packaging is also a reason for this growth.
In November 2025, Amcor plc launched a recycle-ready frozen-seafood packaging format in Latin America featuring a 38% reduced carbon footprint compared with prior multilayer structures, reflecting continued vendor investment in sustainable barrier packaging for temperature-sensitive protein categories.
To Get More Information On Frozen Seafood Packaging Market - Request Free Sample Report
Frozen Seafood Packaging Market Trends
- Rising adoption of recyclable and mono-material flexible films is reshaping frozen seafood packaging design.
- Growing use of modified atmosphere and vacuum packaging is extending shelf life and reducing food waste.
- Expanding e-commerce and direct-to-consumer seafood delivery is driving demand for insulated, tamper-evident packaging formats.
- Increasing integration of smart labels and freshness indicators is enhancing cold-chain visibility and consumer trust.
- Growing partnerships between packaging manufacturers and seafood processors are advancing lightweight, high-barrier film technologies.
The U.S. Frozen Seafood Packaging Market Outlook
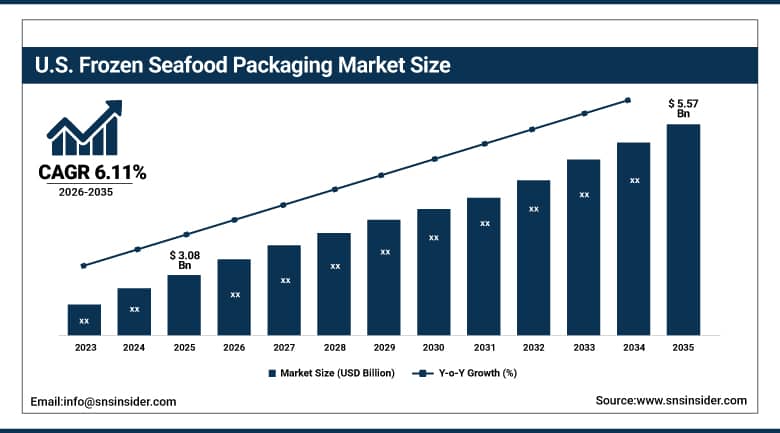
The U.S. frozen seafood packaging market was valued at USD 3.08 Billion in 2025 and is projected to reach USD 5.57 Billion by 2035, growing at a CAGR of 6.11% during 2026-2035.
The market for packaging U.S. Frozen Seafood Packaging is experiencing constant growth, fueled by increased per capita consumption of seafood, improved cold chain logistics, and increased demand for ready-to-cook frozen seafood. Consumer preference for sustainable and trackable sources of seafood is encouraging brands to use recyclable packaging options that are also lightweight. The development of online groceries and meal kits is leading to an increased need for insulated and tamper-proof packaging that can be used in temperature-controlled transport. Increased adoption of new barrier films and modified atmosphere packaging technology is allowing the seafood industry to prolong shelf-life and reduce wastage. Moreover, increased importance placed by retailers on private label frozen seafood packaging is also driving packaging volume growth.
Sonoco Products Company launched a new recyclable paperboard tray system for frozen seafood retail packs in the month of August 2025. These trays would be used as an alternative to the multilayered plastic trays that provide moisture protection and freezer-grade strength.
Frozen Seafood Packaging Market Segment Analysis
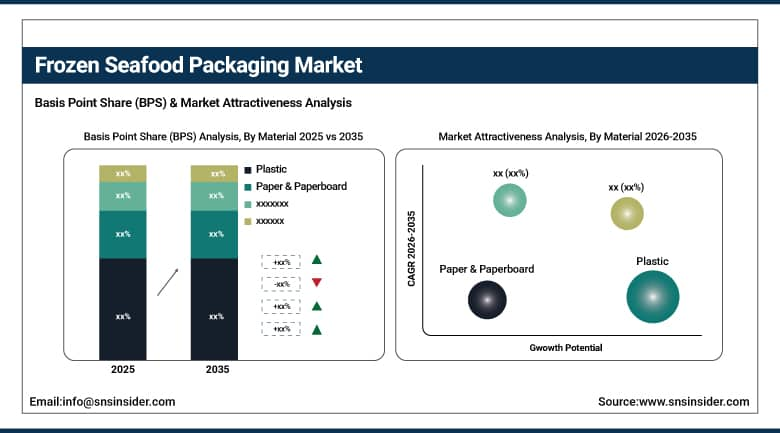
- By Material Type, plastic segment dominated the frozen seafood packaging market in 2025 with 46% share; paper & paperboard segment is the fastest-growing segment.
- By Packaging Type, bags & pouches segment dominated the market in 2025 with 41% share; trays segment is the fastest-growing segment.
- By Application, fish segment dominated the market in 2025 with 39% share; shrimp & crustaceans segment is the fastest-growing segment.
- By Distribution Channel, supermarkets & hypermarkets segment dominated the market in 2025 with 54% share; online retail segment is the fastest-growing segment.
By Material Type, plastic dominates the frozen seafood packaging market while paper & paperboard registers the fastest growth
Plastic dominates the frozen seafood packaging market owing to its superior moisture barrier properties, low cost, and compatibility with vacuum sealing and modified atmosphere packaging processes widely used across seafood processing facilities. The flexible nature along with high resistance to freezer burn and oxidation offered by the materials, which include polyethylene and polyamide multi-layer films, gives excellent protection even during cold storage and transport. The already existing production facilities and availability of plastic resins are contributing toward the dominance of this segment in the market.
Paper & Paperboard is experiencing rapid growth driven by tightening plastic-reduction regulations and rising consumer preference for recyclable, curbside-collectible packaging formats. The manufacture of moisture-resistant coated paperboard trays and cartons that can withstand freezing temperatures without losing their physical strength is becoming commonplace. The increasing commitment of retailers to plastics reduction objectives and the availability of barrier coatings suitable for freezers have helped foster this trend in frozen seafood retail packaging.
By Packaging Type, bags & pouches dominates the frozen seafood packaging market while trays emerge as the fastest-growing format
Bags & pouches rules the frozen seafood packaging market as the most suitable packaging type for vacuum packaging of fish, fish fillets, and shellfish in a compact and economical structure that helps in reducing freezer burn. These types of packaging are favored owing to their good barrier properties, easy stackability during freezing, and suitability on automated packing lines for high speed filling operations. The presence and manufacturing capability of flexible pouches is enhancing this category’s market dominance.
Trays is experiencing rapid growth driven by rising retail demand for ready-to-cook, portion-controlled seafood packs that offer strong shelf presence and convenient at-home preparation. Rising popularity of skin pack and modified atmosphere trays packaging by super and club markets is driving this market segment. Developments in the area of recyclable freezer paper board and PET trays are offering several opportunities for commercial applications in this market segment.
By Application, fish dominates the frozen seafood packaging market while shrimp & crustaceans experiences the fastest growth
Fish dominates the frozen seafood packaging market due to its high global consumption volumes, established cold-chain distribution networks, and broad availability across both retail and foodservice channels. Frozen fish fillets and whole fish would need to be protected from moisture damage and freezer burn, which makes the packaging films used by this category highly popular. There are many applications in which these films are used and there will be increasing consumption due to their wide usage.
Shrimp & Crustaceans is growing rapidly on account of rising global shrimp aquaculture output and expanding export volumes from major producing nations across Asia and Latin America. Increasing demand for individually quick-frozen shrimp in resealable, tamper-evident pouches is compelling processors to adopt advanced barrier packaging. Rising foodservice demand for portion-controlled frozen shrimp packs is opening up several opportunities for commercial utilization in this segment.
By Distribution Channel, supermarkets & hypermarkets dominates the frozen seafood packaging market while online retail registers the fastest growth
Supermarkets & hypermarkets dominates the frozen seafood packaging market due to consumer preference for purchasing frozen seafood through established retail chains offering wide product assortments and reliable cold-chain handling. These stores offer consumers an opportunity to have access to different frozen seafood varieties, thereby enabling them to make comparisons on freshness dates and claims made about packaging. There is also a connection between the seafood processing company and the retail chain, which is responsible for frozen products' sales.
Online Retail is growing rapidly because of the convenience of scheduled grocery delivery, subscription-based seafood boxes, and expanding access to specialty and sustainably sourced seafood brands not typically carried by physical stores. The comparison of sourcing transparency, freshness dates, and sustainability of packaging can be done by consumers before purchase through e-commerce platforms. Increased investments in the insulation of delivery packages for the last mile and the increasing ease of frozen food purchasing through e-commerce have contributed to its success.
Regional Insights
|
Region |
Country |
Share (2025) |
|---|---|---|
|
North America |
United States |
84.30% |
|
Asia Pacific |
China |
29.40% |
|
Europe |
Germany |
26.80% |
|
Middle East & Africa |
UAE |
18.60% |
|
Latin America |
Brazil |
25.90% |
North America Frozen Seafood Packaging Market Insights
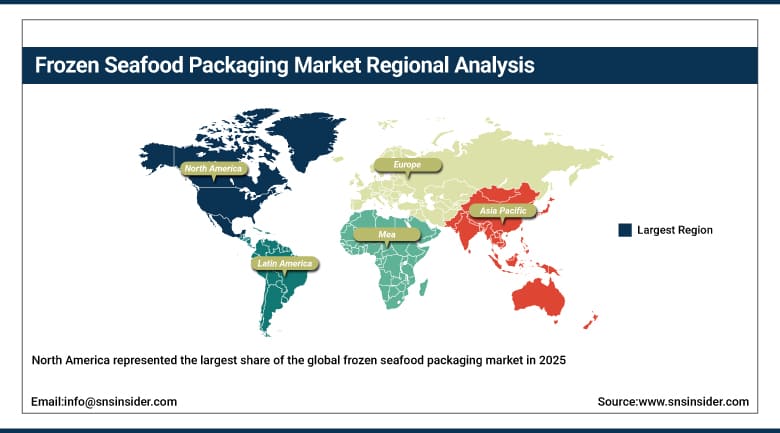
North America represented the largest share of the global frozen seafood packaging market in 2025, supported by high per-capita seafood consumption, well-established cold-chain logistics, and broad retail and foodservice distribution infrastructure. The rising demand by consumers for sustainable and trackable seafood has increased the use of recyclable packaging materials in the region. The growing penetration of e-commerce grocery deliveries and meal kits has prompted processors to add more insulated and tamper-proof packaging options. Seafood processing and packaging manufacturing facilities, which are well-developed in both the US and Canada, have helped increase the availability of the product.
The US has a share of about 85.40% in the North American market as it has a large consumer base for seafood in the country along with extensive cold chain processing and packaging facilities. Canada is helping in growing the regional market by increasing its demand for frozen seafood owing to its developing fisheries and aquaculture export industry.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Frozen Seafood Packaging Market Insights
Asia Pacific is expected to register the fastest CAGR in the frozen seafood packaging market during 2026-2035, driven by expanding seafood processing and export capacity, rising disposable income, and growing modern retail penetration across the region's large population base. A significant amount of shrimp and fish processing is done in China, Vietnam, and Indonesia, thus increasing the demand for packaging for local sales and exports. Increased investment in the cold chain infrastructure, along with increasing consumer awareness about food safety, has been driving market growth. The increase in aquaculture production in the region is also helping to drive the above-average growth of Asia Pacific compared to other developed regions.
In 2025, China captured an estimated market share of around 32.60%, helped by the large seafood processing base and cold chain exports in the country. Other major contributors include Japan, India, and Vietnam, wherein the latter is witnessing market growth due to the rapid development of shrimp export industry and freezing capability of seafood.
Europe Frozen Seafood Packaging Market Insights
The frozen seafood packaging market had a noteworthy market share in Europe in 2025 due to well-established practices of seafood consumption along with good regulatory policies regarding food contact packaging material. An increasing demand for sustainable packaging material and recycled packaging material in Norway, United Kingdom, and Germany is expected to drive innovation in this market. Increasing regulations regarding single-use plastic and preference towards fiber-based packaging material will add on to Europe’s market share.
The market share of Norway in Europe stood at 19.60% in 2025 due to the country’s status as a major global supplier of salmon along with an established infrastructure for seafood processing and cold chain. The contribution from Germany and United Kingdom will help add on to the European market share as well.
Middle East & Africa and Latin America Frozen Seafood Packaging Market Insights
The Middle East & Africa region is exhibiting steady growth as cold-chain infrastructure and modern retail penetration expand across the Gulf states, supported by rising seafood import volumes. Latin America is similarly benefiting from expanding seafood export capacity and growing domestic consumption of frozen seafood across major regional urban centers.
In 2025, the UAE held the top position in the Middle East and Africa region, having a regional share of 16.80%, as a result of developing cold-chain retail and increasing seafood imports demand. In the Latin American region, Chile accounted for 27.40% of the total seafood market share in 2025 owing to being the largest exporter of salmon and seafood in the world.
Growth Drivers: Rising Seafood Consumption and Cold-Chain Expansion Driving Market Growth
Some of the key drivers behind the development of the frozen seafood packaging market are the increased consumption of seafood in general around the world, the expansion of cold chain logistics networks, and growing preference for more convenient and long-lasting protein sources as compared to fresh options. With the growing awareness regarding the advantages of frozen seafood among consumers, producers see new growth possibilities in retail, foodservice, and export packaging of this product category.
Growing adoption of vacuum and modified atmosphere packaging technologies continues to expand as processors seek to extend shelf life and reduce spoilage-related losses. Increasing innovation in barrier film and freezer-grade coating technology is influencing new product development trends across the overall frozen seafood packaging market.
Restraints: Regulatory Pressure and Raw Material Volatility Limiting Market Expansion
Despite good consumer demand for the product category, there are challenges linked to increasing restrictions concerning allowable materials, labeling, and recyclability of food contact packaging under changing plastic reduction regulations in the different regions. Instability in polymer resin prices, which represent a large proportion of total manufacturing costs, will remain challenging for profit margins of the manufacturers and price management. Inconsistencies in supply of packaging materials may be affected by sourcing of different raw material volumes and seasons from different geographies.
Expenses related to the manufacture of recycleable, freezer grade barrier materials are quite high and hence contribute to the overall production cost which makes it hard for small players to compete in terms of price. Additionally, more and more competition from existing and new packaging manufacturers is creating pricing pressures. As the industry grows, companies have to ensure that their products remain competitive in terms of cost and performance.
Opportunities: Sustainable Materials and Smart Packaging Creating New Growth Avenues
Significant opportunities exist through recyclable mono-material films, fiber-based tray alternatives, and expanding applications in smart, freshness-indicating packaging technologies. Developing curbside-recyclable packaging formats can address growing retailer and consumer interest in sustainable frozen-food packaging. Manufacturers can capitalize on growing interest in traceable, sustainably sourced seafood packaging that supports premium positioning and stronger processor trust. Expanding cold-chain infrastructure across emerging seafood-exporting nations provides another avenue for increasing packaging demand and export volumes.
Innovation around temperature-indicating labels and blockchain-enabled traceability can create differentiated, high-value packaging solutions and attract quality-conscious retailers and processors. Strategic partnerships between packaging manufacturers and seafood processors also offer an opportunity to develop next-generation barrier film formulations. Additionally, expanding e-commerce accessibility and insulated last-mile delivery packaging can strengthen differentiation. These developments can help companies capture emerging demand, broaden consumption occasions, and support premiumization across multiple consumer segments and distribution channels.
Recent Developments
- 2025: Amcor plc launched a recycle-ready frozen-seafood packaging format in Latin America featuring a 38% reduced carbon footprint compared with prior multilayer structures.
- 2025: Sonoco Products Company introduced a recyclable paperboard tray system for frozen seafood retail packs, replacing multilayer plastic trays across major U.S. grocery chains.
- 2025: Sealed Air Corporation completed a new manufacturing facility investment dedicated to producing sustainable food-contact packaging solutions, including formats for frozen seafood.
- 2024: Huhtamaki Oyj expanded its partnership with Borealis to advance recycling solutions for plastic food packaging, including applications for frozen seafood products.
Frozen Seafood Packaging Companies are:
- Amcor plc
- Sealed Air Corporation
- Crown Holdings Inc.
- Sonoco Products Company
- Mondi Group
- DS Smith plc
- Huhtamaki Oyj
- Constantia Flexibles Group GmbH
- ProAmpac LLC
- Winpak Ltd.
- Genpak LLC
- Ardagh Group S.A.
- Uflex Ltd.
- Smurfit Westrock plc
- Novolex Holdings, LLC
- Tetra Pak International S.A.
- Coveris Holdings S.A.
- Cascades Inc.
- Pactiv Evergreen Inc.
- Silgan Holdings Inc.
Frozen Seafood Packaging Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 18.09 Billion |
| Market Size by 2035 | USD 32.40 Billion |
| CAGR | CAGR of 6.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material Type (Plastic, Paper & Paperboard, Metal, Others) • By Packaging Type (Bags & Pouches, Boxes & Cartons, Trays, Films, Others) • By Application (Fish, Shrimp & Crustaceans, Mollusks & Shellfish, Other Seafood) • By Distribution Channel (Supermarkets & Hypermarkets, Foodservice, Online Retail, Specialty Stores) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amcor plc, Sealed Air Corporation, Crown Holdings Inc., Sonoco Products Company, Mondi Group, DS Smith plc, Huhtamaki Oyj, Constantia Flexibles Group GmbH, ProAmpac LLC, Winpak Ltd., Genpak LLC, Ardagh Group S.A., Uflex Ltd., Smurfit Westrock plc, Novolex Holdings, LLC, Tetra Pak International S.A., Coveris Holdings S.A., Cascades Inc., Pactiv Evergreen Inc., Silgan Holdings Inc. |
Frequently Asked Questions
Key players include Sealed Air Corporation, Amcor plc, Crown Holdings Inc., Mondi Group, and Sonoco Products Company, among others.
Key opportunities include demand for sustainable packaging, adoption of high-barrier materials, and increasing use of innovative packaging formats for extended seafood shelf life.
The market is driven by rising global seafood consumption, expanding cold-chain infrastructure, and increasing consumer preference for convenient, long-shelf-life frozen protein products.
The Plastic segment dominated the Frozen Seafood Packaging Market in 2025.
The North America region dominated the Frozen Seafood Packaging Market in 2025, accounting for approximately 35% of global market share.
