
Hospital Capacity Management Solutions Market Report Scope & Overview:
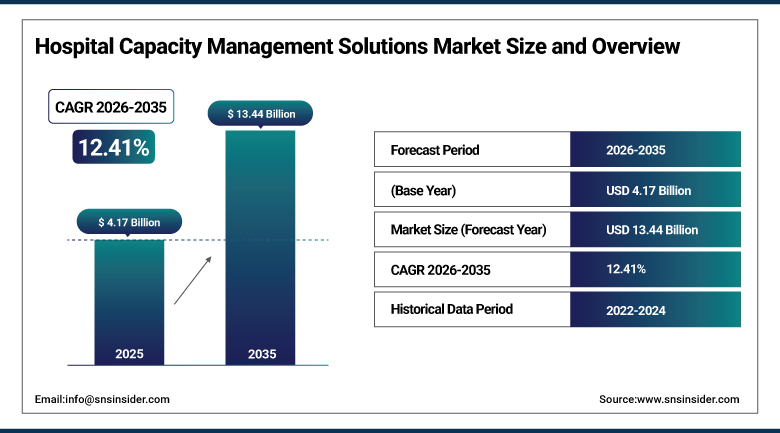
The Hospital Capacity Management Solutions Market was valued at USD 4.17 Billion in 2025 and is expected to reach USD 13.44 Billion by 2035, growing at a CAGR of 12.41% from 2026-2035.
Hospital capacity management solutions are software platforms and supporting services that give health systems real-time visibility into bed availability, patient flow, and equipment location, replacing spreadsheets and phone calls with centralised command centres and predictive analytics. These platforms help hospitals move patients efficiently from admission through discharge, anticipate surges before they overwhelm emergency departments, and allocate scarce staff and equipment where they are needed most. Growth is supported by rising hospital overcrowding and constrained bed availability across health systems, factors that continue to make operational efficiency a board-level priority rather than a back-office concern. According to OECD statistics, bed occupancy in acute care stands at 72%, showing an actual need to reconcile capacity availability with patient demand fluctuations using AI-based planning solutions.
On November 20, 2025, TeleTracking Technologies announced the release of Decision IQ, which is an AI-powered solution that helps in managing patient flow on a large scale, at their annual TeleSummit customer conference in Nashville. The University of Louisville Health was among the first organizations to adopt this technology in order to overcome its capacity limitations and enhance patient access. Decision IQ is powered by artificial intelligence and is used in the process of managing patient flow. It helps in identifying inefficiencies in operations and optimal use of capacity.
To Get more information Hospital Capacity Management Solutions Market - Request Free Sample Report
Hospital Capacity Management Solutions Market Trends
-
Rising adoption of generative AI copilots providing conversational, actionable guidance for capacity decisions.
-
Growing use of predictive analytics forecasting bed demand and staffing needs before surges occur.
-
Expanding integration of capacity management platforms with existing electronic health record systems.
-
Increasing consolidation as vendors acquire complementary patient flow and transition-of-care platforms.
-
Rising adoption of cloud-based deployment replacing legacy on-premise hospital command centre infrastructure.
U.S. Hospital Capacity Management Solutions Market Overview
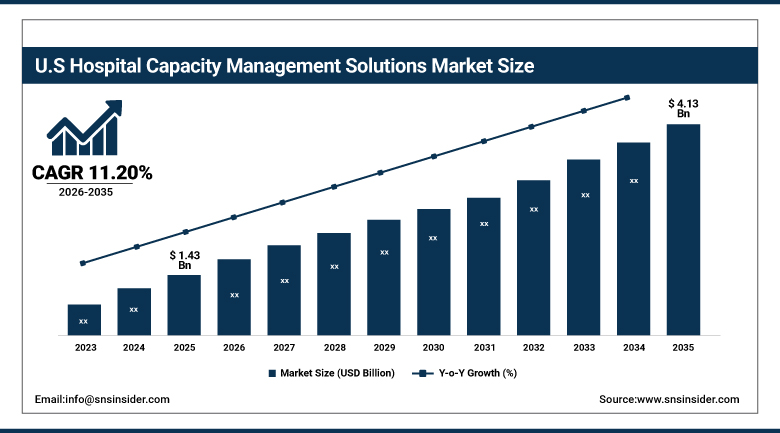
The U.S. Hospital Capacity Management Solutions Market was valued at USD 1.43 Billion in 2025 and is expected to reach USD 4.13 Billion by 2035, growing at a CAGR of 11.20% from 2026-2035.
The U.S. Hospital Capacity Management Solutions Market remains the largest national market, supported by acute nursing shortages and a regulatory and reimbursement environment that increasingly rewards hospitals for reducing length of stay. Leading vendors headquartered in the country continue to compete intensely on AI capability, with several platforms now processing the largest available hospital operations datasets to generate increasingly precise predictions for bed demand, staffing needs, and discharge timing. Large integrated health systems, including HCA Healthcare, Cleveland Clinic, and Mount Sinai, continue to expand use of command-centre style capacity platforms across dozens of hospitals, while independent healthcare technology rating organisations have become an increasingly important factor in vendor selection as hospital buyers seek verified, outcomes-based evidence before committing to multi-year enterprise contracts.
On February 4, 2026, LeanTaaS was recognized as Best in KLAS 2026 for Capacity Optimization Management by KLAS Research for the second consecutive year. The recognition was based on direct customer feedback and documented real-world outcomes, highlighting customer experiences with the company’s capacity optimization solutions. LeanTaaS became the only vendor to receive the Best in KLAS designation twice in this specific category. The achievement reinforces the company’s position in healthcare capacity management and highlights increasing adoption of technology-driven solutions designed to improve resource utilization, operational efficiency, and patient flow across healthcare organizations.
Hospital Capacity Management Solutions Market Segment Analysis
-
By Component, the Software segment dominated the Hospital Capacity Management Solutions Market with a 64.60% share in 2025, while the Services segment is the fastest growing with a CAGR of 13.60% during 2026-2035.
-
By Deployment Mode, the On-Premise segment dominated the Hospital Capacity Management Solutions Market with a 54.60% share in 2025, while the Cloud-Based segment is the fastest growing with a CAGR of 14.80% during 2026-2035.
-
By Solution Type, the Bed Management segment dominated the Hospital Capacity Management Solutions Market with a 34.60% share in 2025, while the Patient Flow Management segment is the fastest growing with a CAGR of 13.80% during 2026-2035.
-
By End-User, the Hospitals segment dominated the Hospital Capacity Management Solutions Market with a 62.60% share in 2025, while the Ambulatory Surgical Centers segment is the fastest growing with a CAGR of 13.40% during 2026-2035.
By Component, Software Dominates the Market and Services Grows Fastest
Software dominated the market in 2025. The core platforms that provide real-time bed visibility, predictive analytics, and workflow automation represent the primary purchase for health systems building capacity management capability, and continued feature expansion, including generative AI copilots and predictive forecasting, continues to reinforce software's position as the largest component category.
Services are projected to be the fastest-growing component over the forecast period. Implementation, training, and ongoing support services continue to see rising demand as health systems increasingly require specialised expertise to configure complex capacity management platforms and drive genuine clinical workflow adoption, particularly for enterprise-scale deployments spanning dozens of hospitals within a single health system.
By Deployment Mode, On-Premise Dominates the Market and Cloud-Based Grows Fastest
On-premise deployment dominated the market in 2025. A substantial installed base of hospital command centre infrastructure remains deployed on local servers, reflecting historical data security preferences and existing capital investment among larger, more established health systems that adopted capacity management technology before cloud-based alternatives became widely available.
Cloud-based deployment is projected to be the fastest-growing deployment mode over the forecast period. Rising comfort with cloud technologies across the healthcare sector, combined with the scalability and faster implementation cloud platforms offer relative to on-premise infrastructure, continues to drive accelerating adoption, particularly among health systems seeking to deploy capacity management capability across multiple facilities without extensive local hardware investment.
By Solution Type, Bed Management Dominates the Market and Patient Flow Management Grows Fastest
Bed management dominated the market in 2025. Real-time visibility into bed availability, cleaning status, and patient assignment remains the foundational capability that most hospitals first deploy when building capacity management infrastructure, and this established, universal use case continues to anchor bed management as the largest solution type category.
Patient flow management is projected to be the fastest-growing solution type over the forecast period. Persistent emergency department overcrowding and rising pressure to reduce length of stay continue to drive demand for platforms capable of orchestrating patient movement across the entire care journey, from admission through discharge, positioning patient flow management for sustained above-market growth relative to the broader bed-management-dominated solution mix.
By End-User, Hospitals Dominates the Market and Ambulatory Surgical Centers Grows Fastest
Hospitals dominated the market in 2025. The scale and complexity of inpatient operations, spanning emergency departments, intensive care units, and general medical-surgical floors, continues to require the most comprehensive capacity management deployment of any care setting, sustaining hospitals as the clear leading end-user category.
Ambulatory surgical centers are expected to be the fastest-growing end-user category over the forecast period. The shift toward minimally invasive surgeries and shorter recovery times has significantly increased patient preference for ambulatory surgical centers, and these facilities increasingly require their own scheduling and capacity optimisation capability to manage rising procedure volumes efficiently.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
88.60% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
China |
38.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Hospital Capacity Management Solutions Market Insights
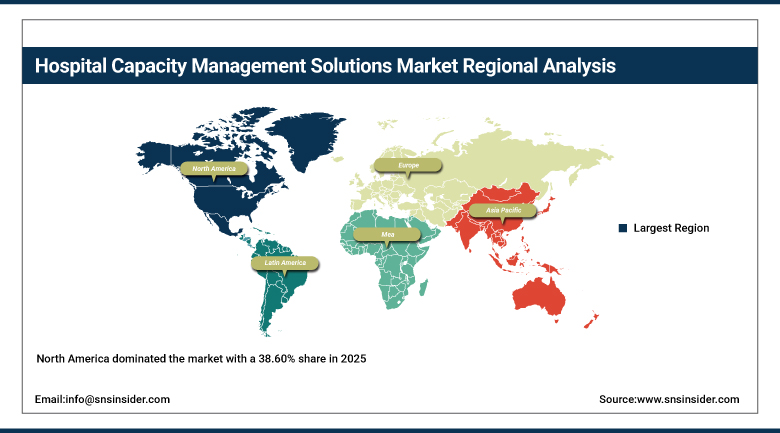
North America dominated the market with a 38.60% share in 2025. Advanced healthcare infrastructure, persistent nursing and staffing shortages, and a regulatory environment that increasingly ties reimbursement to operational efficiency continue to anchor this leadership position. The United States represents the substantial majority of regional demand, reflecting both its healthcare system scale and its concentration of leading capacity management technology vendors.
Canada contributes additional regional demand as its own publicly funded health system continues to expand adoption of capacity planning and patient flow technology. Continued AI-driven product innovation and rising vendor consolidation are expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Hospital Capacity Management Solutions Market Insights
Asia Pacific is projected to be the fastest-growing region, registering a CAGR of approximately 14.0% over the forecast period from 2026 to 2035. Rapidly expanding hospital infrastructure, rising healthcare digitization investment, and growing government initiatives promoting smart hospital technology continue to accelerate regional adoption of capacity management platforms across both public and private healthcare systems.
China anchors regional demand through its expanding hospital network and growing investment in healthcare digitization. Japan and South Korea contribute additional regional depth through established, technology-forward healthcare systems, while India's rapidly expanding private hospital sector continues to add meaningful incremental regional growth.
Europe Hospital Capacity Management Solutions Market Insights
Europe holds a significant share of the global market, supported by well-developed public health systems and growing emphasis on energy-efficient, technologically modern hospital operations. Germany anchors regional demand through its substantial hospital sector and strong domestic health technology development capability.
The United Kingdom, France, and Italy add consistent regional demand as national health systems continue extending capacity management technology adoption to address bed occupancy and staffing pressures. Continued regional focus on sustainable, efficient hospital operations is expected to sustain steady growth across the broader European market.
MEA & Latin America Hospital Capacity Management Solutions Market Insights
The Middle East & Africa region is supported by growing healthcare infrastructure investment across the United Arab Emirates and Saudi Arabia, where regional governments continue to fund modern hospital construction and smart facility technology as part of broader healthcare modernisation strategies.
Latin America accounted for approximately 7% of the global market in 2025, anchored by Brazil, where a growing domestic healthcare sector sustains steady demand for capacity management technology. Mexico contributes further incremental growth as regional healthcare infrastructure investment continues to expand.
Market Dynamics
Growth Drivers: Hospital Overcrowding and Staffing Shortages
Rising hospital overcrowding and increasing patient admission rates stand as the primary growth driver, as limited availability of hospital beds continues to strain health systems worldwide. Growing operational inefficiencies, combined with persistent clinical staffing shortages, continue to make real-time capacity visibility and predictive planning an operational necessity rather than a discretionary technology investment.
Increasing pressure to control healthcare operational costs represents a second major driver, as health systems face mounting financial strain and continue to view capacity management technology as a proven route to reducing length of stay, improving throughput, and maximising utilisation of existing beds and staff without requiring expensive facility expansion.
Restraints: Integration Complexity and Implementation Cost
Integration complexity remains a genuine restraint, as capacity management platforms must connect reliably with existing electronic health record systems, admission-discharge-transfer feeds, and a range of other hospital information systems, a technical undertaking that can extend implementation timelines and require substantial information technology resources.
High implementation cost presents a further restraint, as enterprise-scale capacity management deployments spanning dozens of hospitals require substantial upfront investment in software licensing, configuration services, and change management support, a cost profile that can challenge smaller, independent hospitals operating with more limited capital budgets.
Opportunities: Generative AI Integration and Ambulatory Care Expansion
The continued integration of generative AI capabilities represents a significant opportunity for the Hospital Capacity Management Solutions Market, as vendors offering conversational, actionable guidance can help health systems simplify complex capacity decisions. AI-enabled tools can reduce the cognitive burden on operations teams and clinical leadership by supporting faster interpretation of patient-flow, bed-utilization, staffing, and resource data.
Another growth opportunity is the expansion of capacity management solutions into ambulatory surgical centers and outpatient facilities. The increasing adoption of minimally invasive procedures, shorter recovery periods, and same-day care is expanding the number of healthcare facilities requiring efficient capacity planning, scheduling, resource allocation, and patient-flow optimization systems to improve operational efficiency and support better utilization.
Recent Developments:
-
2026: Oracle Corporation (Cerner) deployed new Oracle Health solutions at San Juan Regional Medical Center to streamline patient flow, improve bed management, and provide real-time visibility into capacity and demand.
-
2026: Epic Systems Corporation highlighted expanded self-scheduling deployment across more than 1,100 clinics in the UK, helping healthcare organizations increase appointment capacity and reduce administrative workload.
-
2026: Qventus, Inc. expanded its partnership with HonorHealth through the AI Solution Factory, supporting co-development of AI solutions across perioperative and inpatient care operations.
Hospital Capacity Management Solutions Market Key Players are:
-
Oracle Corporation (Cerner)
-
GE HealthCare Technologies Inc.
-
Epic Systems Corporation
-
McKesson Corporation
-
Koninklijke Philips N.V.
-
Veradigm (Allscripts)
-
Athenahealth, Inc.
-
eClinicalWorks
-
TeleTracking Technologies, Inc.
-
Bamboo Health (Central Logic)
-
LeanTaaS, Inc.
-
Qventus, Inc.
-
Vocera Communications, Inc. (Stryker)
-
Symplr
-
Stanley Healthcare
-
Midmark Corporation
-
CenTrak, Inc.
-
Infor, Inc.
-
Honeywell International Inc.
-
Apella
Hospital Capacity Management Solutions Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.17 Billion |
| Market Size by 2035 | USD 13.44 Billion |
| CAGR | CAGR of 12.41% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software, Services) • By Deployment Mode (Cloud-Based, On-Premise) • By Solution Type (Bed Management, Patient Flow Management, Workforce & Staffing Optimization, Asset Management, Real-Time Location Systems (RTLS), Patient Care Management, Reporting & Analytics, Others) • By End-User (Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Oracle Corporation (Cerner), GE HealthCare Technologies Inc., Epic Systems Corporation, McKesson Corporation, Koninklijke Philips N.V., Veradigm (Allscripts), Athenahealth, Inc., eClinicalWorks, TeleTracking Technologies, Inc., Bamboo Health (Central Logic), LeanTaaS, Inc., Qventus, Inc., Vocera Communications, Inc. (Stryker), Symplr, Stanley Healthcare, Midmark Corporation, CenTrak, Inc., Infor, Inc., Honeywell International Inc., Apella |

Frequently Asked Questions
Key players include Oracle Corporation, GE HealthCare Technologies Inc., Epic Systems Corporation, McKesson Corporation, TeleTracking Technologies, Inc., and LeanTaaS, Inc., among other healthcare technology vendors.
Continued integration of generative AI capability and continued expansion into ambulatory surgical centers represent the primary opportunities for vendors.
Growth is primarily driven by rising hospital overcrowding and increasing patient admission rates, combined with persistent clinical staffing shortages.
By Component, Software dominated the market with a 64.60% share in 2025, reflecting its role as the core purchase for capacity management capability.
North America dominated the market with a 38.60% share in 2025, supported by persistent staffing shortages and a strong concentration of leading vendors.
