
Hypersonic Weapons Market Report Scope & Overview:
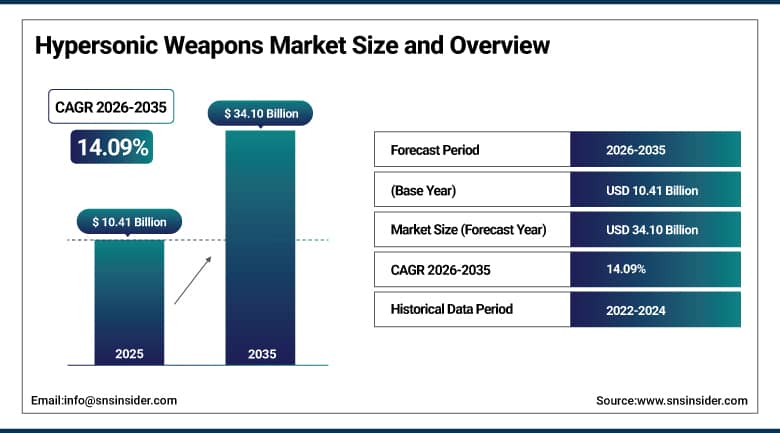
The Hypersonic Weapons Market was valued at USD 10.41 Billion in 2025 and is expected to reach USD 34.10 Billion by 2035, growing at a CAGR of 14.09% from 2026-2035.
The market for Hypersonic Weapons comprises missiles and glide vehicles with propulsion, guidance, and thermal protection systems which allow the vehicle to sustain a flight regime of Mach 5 or higher speeds and provide capabilities of a rapid, maneuverable, and hard to intercept attack on enemy forces for the nation's defense needs. The demand for these weapons has been driven by the increased strategic rivalry between the US, China, and Russia and also due to the accelerated indigenous programs being run by India, France, Japan, South Korea, Germany, and Australia to bridge their capability gaps. Development and sustainment efforts for these weapons are primarily being allocated towards propulsion technologies, heat-resistant materials able to withstand high aerodynamic heating during the flight and guidance systems which ensure precision even at hypersonic speeds.
Program funding continues to scale rapidly, illustrated by an April 2026 contract modification in which Lockheed Martin secured USD 1.36 billion for the U.S. Navy's Conventional Prompt Strike hypersonic missile program, with Northrop Grumman and General Dynamics Mission Systems named as subcontractors on the two-stage solid-rocket boost-glide system. The award, funded jointly through Army missile procurement and Navy research and procurement accounts, reflects how hypersonic programs increasingly span multiple military branches and rely on shared industrial infrastructure, a structural feature of the market that is expected to persist as allied nations pursue similar joint-service approaches to accelerate fielding timelines while managing the high per-unit development cost associated with hypersonic strike systems.
To Get More Information On Hypersonic Weapons Market - Request Free Sample Report
Hypersonic Weapons Market Trends:
-
Accelerating multi-billion-dollar program funding for the U.S. Navy and Army's Conventional Prompt Strike and Long Range Hypersonic Weapon systems.
-
Growing emphasis on air-breathing scramjet propulsion as an alternative to boost-glide architectures for sustained hypersonic cruise flight.
-
Rising investment in glide phase interceptor and hypersonic missile defense systems in response to expanding adversary capabilities.
-
Expansion of indigenous hypersonic development programs across India, Japan, South Korea, France, and Germany to reduce reliance on imported systems.
-
Increasing use of joint-service and multinational industrial teaming arrangements to share the cost burden of hypersonic technology development.
U.S. Hypersonic Weapons Market Outlook:
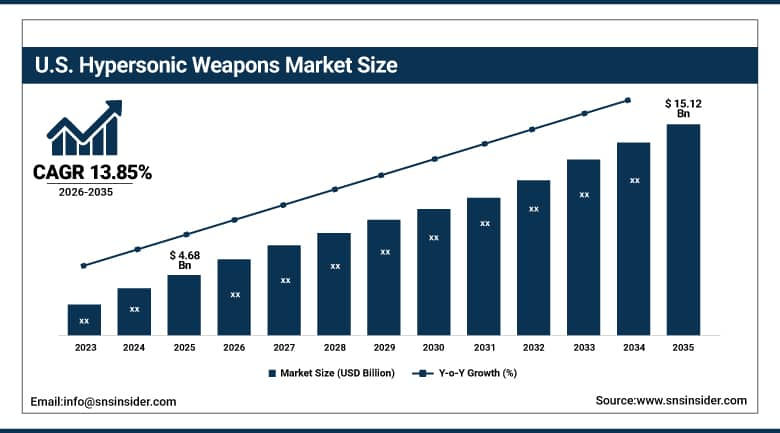
The U.S. Hypersonic Weapons Market was valued at USD 4.68 Billion in 2025 and is expected to reach USD 15.12 Billion by 2035, growing at a CAGR of 13.85% from 2026-2035.
The U.S. continues to be the only major national market for hypersonic weapons, where the Department of Defense has funded concurrent efforts within the three services – Army, Navy, and Air Force – in the development of the Army-Navy joint program, Conventional Prompt Strike and Long Range Hypersonic Weapon systems which utilize the common Hypersonic Glide Body design. Lockheed Martin is the lead systems integrator in the case of the Navy program, Northrop Grumman, and General Dynamics Mission Systems are significant contractors contributing key subsystems and integration, demonstrating the industrial base with multiple contractors that the Pentagon has developed.
In May 2025, the U.S. Navy completed a successful end-to-end flight test of its Conventional Prompt Strike hypersonic weapon using the common All-Up-Round being co-developed with the Army, a milestone the service described as progressing the program toward sea-based deployment. The test followed a series of funding actions, including a May 2024 USD 756 million Army contract modification to Lockheed Martin for Long Range Hypersonic Weapon ground support equipment, underscoring how the U.S. program has moved from pure research and development funding toward the procurement and fielding phase, even as congressional budget markups have periodically deferred specific missile procurement quantities to later fiscal years.
Hypersonic Weapons Market Segment Analysis:
-
By Component, the Propulsion segment dominated the Hypersonic Weapons Market with approximately 28.60% share in 2025, while the Seeker segment is the fastest growing with a CAGR of approximately 12.90%.
-
By Launch Platform, the Land-Launched segment dominated the Hypersonic Weapons Market with approximately 44.35% share in 2025, while the Air-Launched segment is the fastest growing with a CAGR of approximately 13.75%.
-
By Range, the Short-Range segment dominated the Hypersonic Weapons Market with approximately 26.70% share in 2025, while the Strategic/Long-Range segment is the fastest growing with a CAGR of approximately 12.10%.
-
By End User, the Air Force segment dominated the Hypersonic Weapons Market with approximately 39.45% share in 2025, while the Navy segment is the fastest growing with a CAGR of approximately 13.20%.
By Component, Propulsion dominates, and Seeker grows fastest
The propulsion segment contributed the largest share to components in 2025 owing to the critical importance of the propulsion system in obtaining and maintaining the extremely high speed that defines the hypersonic regime, either using solid-rocket powered boost-glide concepts or novel air breathing scramjet engines. The propulsion system component is the single most difficult and expensive component to develop in any hypersonic weapon development program owing to the testing and material qualification requirements associated with it, making it a disproportionately large part of the program budget compared to the airframe or guidance segments.
The seeker technology segment is growing faster than any other component owing to the increasing need to target hard and mobile targets during the terminal phase of engagement using seeker technology robust enough to operate under the harsh conditions of the hypersonic regime. New development programs are concentrating on the development of multi-mode seeker technologies that integrate radar, infrared and other forms of sensor technology owing to the evolving trend of hypersonic weapon development towards improved strike performance against hardened and mobile targets.
By Launch Platform, Land-Launched dominates, and Air-Launched grows fastest
Land-launched systems commanded the majority of the launch platform market share in 2025, driven by developments like the United States Army's Long Range Hypersonic Weapon, owing to the relatively straightforward approach that ground-based launch systems provide towards their development and deployment compared to their air and sea counterparts. Land-based launch systems can be closer to theaters of operation and can be integrated into long-range strike doctrine faster and more easily than other kinds of launch systems, enabling them to meet initial fielding goals faster than those systems requiring integration into aircraft and ships.
Air-launched hypersonic weapons are seeing the most rapid growth as air force strategists look to the advantage of being able to deploy hypersonic strike capabilities using existing bomber and fighter jets without the vulnerability of land-based launchers having a set position. Development of air-breathing scramjet-powered cruise missiles, under funding by the Defense Advanced Research Projects Agency and collaboration between Raytheon and Northrop Grumman, is making air-launched systems a possibility for fielding.
By Range, Short-Range dominates, and Strategic/Long-Range grows fastest
Short-range hypersonic systems held the largest range-segment share in 2025, reflecting their faster technical maturation path and immediate battlefield utility for theater-level strike missions where hypersonic speed provides a decisive advantage against time-sensitive or heavily defended targets within a constrained operational radius. Several allied nations have prioritized short-range systems as an initial step toward building indigenous hypersonic expertise before committing to more technically demanding long-range programs.
Strategic and long-range hypersonic systems, covering ranges beyond 5,500 kilometers, are growing fastest as major powers pursue intercontinental-range strike capability intended to penetrate increasingly sophisticated integrated air and missile defense networks. These programs require substantially more advanced thermal protection and guidance technology to survive extended atmospheric flight, translating into longer development timelines but also larger long-term program budgets as nations prioritize strategic deterrence capability alongside theater-level strike systems.
By End User, Air Force dominates, and Navy grows fastest
Air Force was the dominant end-user segment in 2025, owing to consistent investments in the air-launched hypersonic strike system, which takes advantage of the current bomber and fighter fleet as well as the operational flexibility of air-launched systems over ground-based or naval launchers. The continued work on air breathing technologies being done by the Air Force will solidify its dominance among other end-users.
The Navy end-user segment is the fastest-growing one, due to the success of the conventional prompt strike program, which has entered the fielding phase after successful end-to-end test flights in May 2025, followed by contract awards worth billions of dollars. As the Navy begins to deploy hypersonic strike capability on surface ships and even submarines, continued procurement funding will ensure that naval end-user demand grows faster than the relatively mature Air Force segment.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
92.10 |
|
Europe |
France |
31.45 |
|
Asia Pacific |
China |
48.65 |
|
Middle East & Africa |
Israel |
36.80 |
|
Latin America |
Brazil |
29.55 |
North America Hypersonic Weapons Market Insights
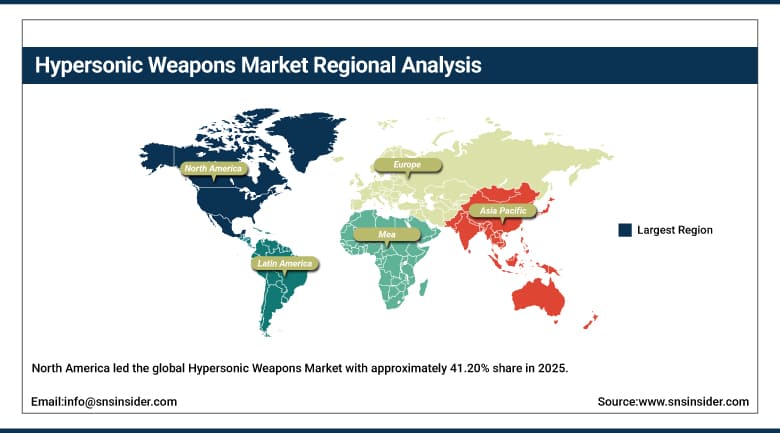
North America led the global Hypersonic Weapons Market with approximately 41.20% share in 2025, driven overwhelmingly by U.S. Department of Defense funding across the Army, Navy, and Air Force hypersonic portfolios, including the jointly developed Conventional Prompt Strike and Long Range Hypersonic Weapon programs. The United States accounted for nearly the entirety of regional revenue, supported by a concentrated industrial base led by Lockheed Martin, RTX Corporation, Northrop Grumman, and Boeing, alongside sustained congressional funding despite periodic procurement quantity adjustments during annual budget markups.
Canada contributes a modest share of regional activity primarily through participation in allied missile defense initiatives and NORAD-related early warning and tracking programs rather than direct hypersonic weapon development. The scale of U.S. program funding, spanning research and development, procurement, and sustainment across multiple parallel programs, is expected to keep North America as the dominant regional market through the near term, even as China's development pace continues to narrow the strategic capability gap driving continued U.S. investment.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Hypersonic Weapons Market Insights
The Asia Pacific region is the leading region in the Hypersonic Weapons Market, expected to grow with a CAGR of around 13.90% over the forecast period from 2026 to 2035, driven by China's speedy deployment of hypersonic glide vehicles and hypersonic cruise missiles as a part of its overall military modernization program. Chinese government-owned defense industry, which includes China Aerospace Science and Technology Corporation, has successfully developed various hypersonic weapons that are either operational or close to becoming operational, necessitating a fast response from other neighboring countries.
The Defence Research and Development Organisation of India is continuously developing indigenously developed hypersonic technology demonstrators, whereas Japan, South Korea, and Australia are developing their hypersonic technologies, some even through collaborations with the United States, with an objective to close the gap of capabilities with China in this region. This combination of a market leader with multiple fast follower markets in this region is going to keep the region growing above the average rate over the forecast period.
Europe Hypersonic Weapons Market Insights
Europe represents a developing hypersonic weapons market, with France leading regional investment through its own hypersonic glide vehicle demonstrator programs and continued collaboration between national defense industrial players and the broader European missile consortium MBDA. Germany has expanded its hypersonic research funding in recent defense budget cycles, reflecting a broader continental push to close perceived capability gaps relative to the United States, China, and Russia.
The United Kingdom is pursuing hypersonic technology development in close cooperation with the United States and Australia under the AUKUS trilateral partnership, focusing on hypersonic and counter-hypersonic capability as one of the initiative's advanced capability pillars. Continued European Union and NATO-level interest in hypersonic missile defense, given rising concern over Russian hypersonic weapon deployments, is expected to sustain steady, if more modest, regional program funding growth relative to the faster-moving Asia-Pacific market.
MEA & Latin America Hypersonic Weapons Market Insights
The hypersonic weapons market in the Middle East & Africa is still in its early stages of development, with Israel being the leader within this region due to its history of investments in missile defenses and precision strikes systems and with Gulf States becoming increasingly interested in hypersonic and counter-hypersonic defenses as part of broader air and missile defense upgrade projects.
Latin American countries have shown little interest in hypersonic weapons to date, with Brazil being the only country actively engaged with respect to this particular category of weapons in the context of broader development of aerospace and defense technologies within its aerospace industry. The Latin American region will continue to be primarily interested in missile defense and early warning solutions rather than hypersonic strike weapons themselves for the foreseeable future.
Market Dynamics:
Growth Drivers: Geopolitical Tensions and Rising Defense Budgets
Escalating strategic competition among the United States, China, and Russia is the primary driver of hypersonic weapons market growth, as each power races to field systems capable of penetrating increasingly sophisticated integrated air and missile defense networks while denying adversaries a comparable capability advantage. This dynamic has drawn a widening circle of allied and regional powers into indigenous or cooperative hypersonic development programs, expanding the addressable program base well beyond the original three leading nations.
Rising national defense budgets across NATO members, driven partly by heightened threat perceptions following Russian hypersonic weapon deployments in recent conflicts, are translating directly into expanded hypersonic research, development, and procurement line items. Defense ministries increasingly treat hypersonic strike and defense capability as a top-tier modernization priority alongside other advanced systems, ensuring hypersonic programs retain budget priority even during periods of broader defense spending constraint or competing modernization demands.
Restraints: Technical Complexity and Program Cost Overruns
Despite the high technical challenges posed by prolonged operation at hypersonic speed, including materials that will endure more than 2,000 degrees Celsius temperatures and systems that must function despite plasma blackout caused by heat, the programs face delayed development schedules and cost overruns due to higher costs compared to estimates. There have been many multi-year schedule delays of major national programs due to flight test failures, necessitating lengthy iterations until reliable systems were finally designed and built.
There is also a lack of dedicated testing facilities, such as hypersonic wind tunnels and flight test ranges, which makes it difficult to proceed faster with validating the design. This lack of qualification facilities coupled with a limited number of contractors having special knowledge needed to integrate hypersonic systems poses a problem for increasing capabilities in industry to support growing government needs.
Opportunities: Missile Defense Integration and Allied Industrial Teaming
The emerging hypersonic missile defense segment, exemplified by the Missile Defense Agency's glide phase interceptor program, represents a significant opportunity as nations recognize that offensive hypersonic capability alone is insufficient without a corresponding ability to detect and intercept adversary systems. This is opening a parallel, defense-oriented revenue stream for contractors beyond traditional offensive weapon development, spanning space-based tracking satellites, ground-based radar upgrades, and interceptor development.
Allied industrial teaming arrangements, such as the AUKUS trilateral partnership's hypersonic capability pillar and continued NATO-level cooperation on hypersonic defense, present a further opportunity by allowing nations to share the substantial cost burden of hypersonic technology development while building interoperable systems across allied militaries. Contractors positioned within these multinational teaming arrangements are well placed to capture a broadening set of program opportunities as more allied nations commit funding to joint hypersonic development initiatives over the coming decade.
Recent Developments:
-
April 2026 - Lockheed Martin secured a USD 1.36 billion contract modification for the U.S. Navy's Conventional Prompt Strike hypersonic missile program, with Northrop Grumman and General Dynamics Mission Systems named as subcontractors.
-
June 2025 - Lockheed Martin was awarded an additional USD 1 billion U.S. Navy contract for continued Conventional Prompt Strike hypersonic missile development, layering FY24 and FY25 research and procurement funding.
-
May 2025 - The U.S. Navy completed a successful end-to-end flight test of its Conventional Prompt Strike hypersonic weapon using the common All-Up-Round being co-developed with the U.S. Army.
-
May 2024 - The U.S. Army awarded Lockheed Martin a USD 756 million contract modification for Long Range Hypersonic Weapon ground support equipment.
-
July 2023 - RTX Corporation, in partnership with Northrop Grumman, secured a follow-on DARPA contract to advance air-breathing hypersonic weapon systems integrating scramjet combustor technology.
Hypersonic Weapons Market Key Players:
-
Lockheed Martin Corporation
-
RTX Corporation
-
Northrop Grumman Corporation
-
The Boeing Company
-
General Dynamics Corporation
-
BAE Systems plc
-
Thales Group
-
Leidos Holdings, Inc.
-
Kongsberg Gruppen ASA
-
Mitsubishi Heavy Industries, Ltd.
-
MBDA
-
Rafael Advanced Defense Systems Ltd.
-
L3Harris Technologies, Inc.
-
Airbus SE
-
Diehl Defence GmbH & Co. KG
-
Saab AB
-
Israel Aerospace Industries Ltd.
-
Hanwha Aerospace Co., Ltd.
-
China Aerospace Science and Technology Corporation
-
Bharat Dynamics Limited
Hypersonic Weapons Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 10.41 Billion |
| Market Size by 2035 | USD 34.10 Billion |
| CAGR | CAGR of 14.09% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Component (Propulsion, Guidance & Navigation, Airframe, Thermal Protection, and Seeker) • by Launch Platform (Land-Launched, Air-Launched, and Sea-Launched) • by Range (Short-Range and Strategic/Long-Range) • by End User (Army, Navy, and Air Force) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, The Boeing Company, General Dynamics Corporation, BAE Systems plc, Thales Group, Leidos Holdings, Inc., Kongsberg Gruppen ASA, Mitsubishi Heavy Industries, Ltd., MBDA, Rafael Advanced Defense Systems Ltd., L3Harris Technologies, Inc., Airbus SE, Diehl Defence GmbH & Co. KG, Saab AB, Israel Aerospace Industries Ltd., Hanwha Aerospace Co., Ltd., China Aerospace Science and Technology Corporation, Bharat Dynamics Limited |
Frequently Asked Questions
Key players in the Hypersonic Weapons Market include Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, The Boeing Company, and General Dynamics Corporation, among others.
Key opportunities lie in the emerging hypersonic missile defense segment, including glide phase interceptor programs, and in allied industrial teaming arrangements such as the AUKUS hypersonic capability pillar that share development costs across nations.
Escalating strategic competition among the United States, China, and Russia, combined with rising national defense budgets across allied nations, is the major growth factor propelling hypersonic weapons investment.
By Launch Platform, the Land-Launched segment dominated the Hypersonic Weapons Market with approximately 44.35% share in 2025.
North America dominated the Hypersonic Weapons Market with approximately 41.20% share in 2025, driven by sustained U.S. Department of Defense program funding across the Army, Navy, and Air Force.
