
Flight Inspection Market Report Scope & Overview:
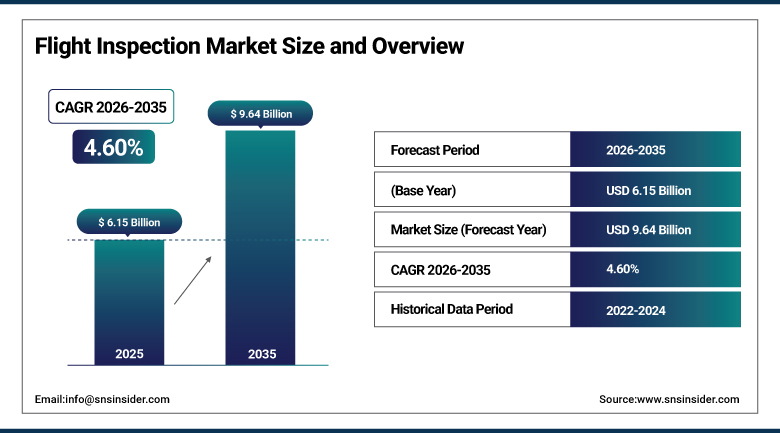
The Flight Inspection Market was valued at USD 6.15 Billion in 2025 and is expected to reach USD 9.64 Billion by 2035, growing at a CAGR of 4.60% from 2026 to 2035.
Flight inspection market is registering consistent growth owing to rising numbers of air traffic, investments in airports infrastructure, and rising regulation needs for calibration of navigational aids that can either be ground based or satellite based. The domain of flight inspections involves specialized testing and calibration of instrument landing system, VOR, DME, radar, and GNSS navigation systems, making sure that they meet ICAO and other regulatory requirements for safe operation of the skies. Increased usage of performance-based navigation systems, along with continuing upgrades in communication, navigation, and surveillance infrastructures in both commercial and military aviations, is contributing towards increased demand for flight inspections aircrafts and systems.
Fixed-wing aircraft account for the majority of flight inspection missions, reflecting the platform's operational range and calibration payload capacity, even as growing satellite-based navigation validation and AI-driven analytics adoption continue expanding automated flight inspection capabilities across commercial airport and defense airspace compliance programs globally.
To Get more information Flight Inspection Market - Request Free Sample Report
Flight Inspection Market Trends
- Rising deployment of AI-driven analytics and automated data transfer is improving flight inspection accuracy and mission efficiency.
- Growing adoption of GNSS-based satellite navigation validation is expanding flight inspection scope beyond traditional ground-based aids.
- Increasing performance-based navigation procedure deployment is driving demand for updated calibration and inspection protocols.
- Expanding airport infrastructure development across emerging economies is broadening flight inspection service and aircraft procurement demand.
- Strategic fleet modernization contracts and public-private partnerships are strengthening national flight inspection capacity and compliance readiness.
The U.S. Flight Inspection Market Outlook
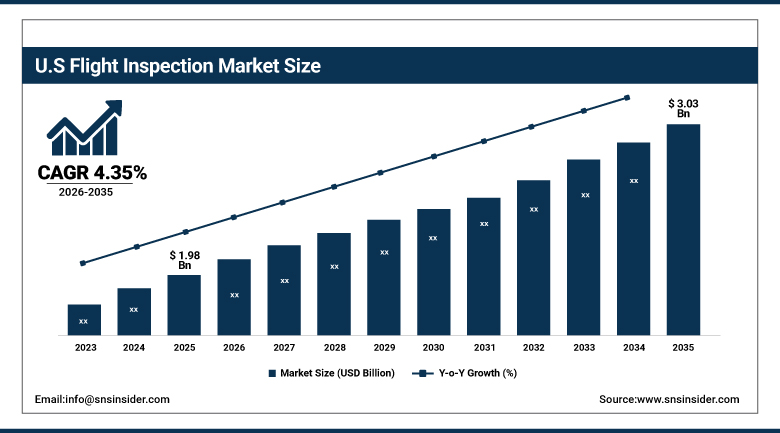
The U.S. Flight Inspection Market was valued at USD 1.98 Billion in 2025 and is projected to reach USD 3.03 Billion by 2035, growing at a CAGR of 4.35% during 2026–2035.
Air navigation services organizations as well as defense aviation agencies from the country have continued to increase their flight inspection fleets and calibration activities in line with the rise in air traffic and regulation needs. The increasing modernization of the navigation aids infrastructure as well as the increasing adoption of GNSS-based satellite validations and automated data exchange further reinforces the domestic demand growth. Increasing government procurement activities for fleet modernization together with the increasing investments in AI calibration analytics further strengthen the country’s status as a prominent flight inspection market.
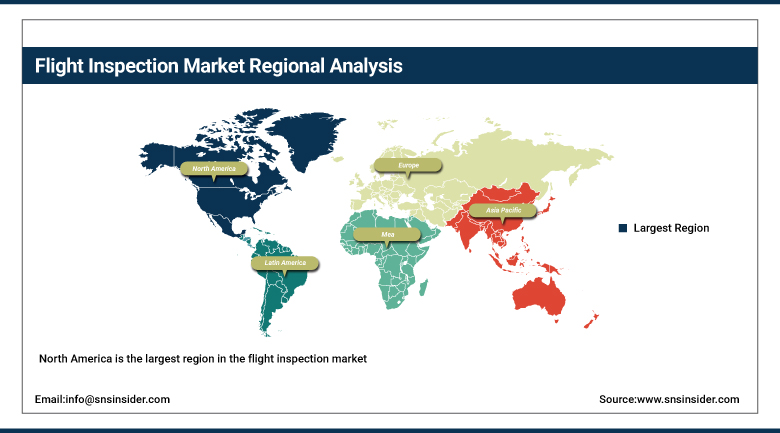
North America has historically established its place as the largest regional flight inspection market, mainly due to extensive commercial and defense aviation infrastructure and stringent FAA regulatory compliance mandates, while Asia Pacific is registering the fastest regional growth rate as demand accelerates across both airport expansion and navigation modernization programs.
Flight Inspection Market Segment Analysis
- By Platform Type, fixed-wing aircraft dominated the flight inspection market with a 70.00% share in 2025, while rotary-wing aircraft is the fastest-growing platform type segment with a CAGR of 5.55% from 2026–2035.
- By System Architecture, onboard integrated systems dominated the flight inspection market with a 58.00% share in 2025, while portable roll-on/roll-off systems is the fastest-growing system architecture segment with a CAGR of 5.20% from 2026–2035.
- By End-User, commercial airports dominated the flight inspection market with the largest share in 2025, while defense & military airports is the fastest-growing end-user segment with a CAGR of 5.80% from 2026–2035.
- By Inspection Type, periodic routine inspection dominated the flight inspection market with the largest share in 2025, while on-demand inspection is the fastest-growing inspection type segment with a CAGR of 5.40% from 2026–2035.
By Platform Type, fixed-wing aircraft dominated the flight inspection market, while rotary-wing aircraft is the fastest-growing segment.
The fixed-wing flight category dominated the market in 2025 with a market share exceeding 70.00% due to their wide range, high cruising speeds, and increased payload capacity, making it possible to accommodate calibration sensors and mission equipment in their long-distance navigation aid inspection routes. Navigation service providers prefer fixed-wing platforms for the high fuel efficiency and ability to undertake multi-airport calibration in one cycle, and the manufacturers have continued to develop and incorporate new technological developments in the areas of avionics integration and sensor miniaturization in order to enhance fixed-wing flight inspection effectiveness.
It is estimated that rotary-wing aircraft will witness the highest CAGR of 5.55% over the period of study, due to increasing need for inspection of low altitude navigation aids, offshore heliports, and confined space airport approaches using helicopters. The benefits offered by rotary wing include hover ability and vertical takeoff facility for calibration of approach lighting systems and low visibility procedures in restricted terrains, which makes them suitable for use by defense authorities and regional airports.
By System Architecture, onboard integrated systems dominated the flight inspection market, while portable roll-on/roll-off systems is the fastest-growing segment.
The onboard integrated system accounted for more than 58.00% market share in 2025 because of the advantage provided by the permanent nature of the calibrated devices used, ensuring high accuracy in measurement and faster preparation for missions than the modular type. Dedicated systems have been favored by air navigation service providers in the operation of a national fleet of flight inspections due to the accuracy and fast preparation of such systems, and further development in digital mission control will only continue to strengthen its position within the flight inspection system market.
Portable roll-on/roll-off systems is expected to grow at the fastest CAGR of 5.20% during the forecast period, supported by increasing demand for flexible, multi-aircraft-compatible calibration equipment among smaller air navigation service providers and defense agencies with limited dedicated fleet budgets. Growing preference for cost-efficient, rapidly deployable inspection capability is prompting providers to adopt modular roll-on/roll-off systems that can be transferred across multiple aircraft platforms, further accelerating segment growth across emerging market flight inspection service programs.
By End-User, commercial airports dominated the flight inspection market, while defense & military airports is the fastest-growing segment.
Commercial airports have been the leading segment in terms of market share in 2025 due to the fact that the number of times calibration is needed periodically according to ICAO and national aviation authorities regulations is very frequent. The commercial airports will continue to form the main customer group for flight inspections due to the fact that there is a large number of navigation aids that require validation, while the growing global air traffic as well as the building of new airports in developing countries will further boost this trend.
Defense & military airports is anticipated to grow at the fastest CAGR of 5.80% through 2035, driven by rising defense aviation infrastructure investment and stringent operational readiness requirements for military navigation and communication systems. Growing geopolitical emphasis on airspace security and combat readiness is encouraging defense agencies to expand dedicated flight inspection fleet procurement, further supporting adoption across national military airbase calibration and compliance programs worldwide.
By Inspection Type, periodic routine inspection dominated the flight inspection market, while on-demand inspection is the fastest-growing segment.
The dominant market player in 2025 is driven by routine periodic inspection due to the compulsory periodic calibration schedules that are part of the ICAO and other national regulations, which must be followed in order to keep the navigation aid certification. For air navigation service providers, the routine periodic inspections ensure compliance with safety requirements in airspace at all times, whereas existing scheduling and aircraft deployment processes continue to support periodic routine inspections as the preferred procedure worldwide.
On-demand inspection is expected to grow at the fastest CAGR of 5.40% during the forecast period, driven by rising need for rapid-response calibration following equipment malfunctions, new navigation aid commissioning, or unscheduled regulatory audits. Growing airport infrastructure expansion and new system installations are increasing demand for flexible, rapid-turnaround inspection capability, further accelerating segment growth across airports requiring urgent navigation aid validation outside standard periodic maintenance cycles.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.00% |
|
Europe |
Germany |
24.00% |
|
Asia Pacific |
China |
34.00% |
|
Middle East & Africa |
UAE |
26.00% |
|
Latin America |
Brazil |
30.00% |
North America Flight Inspection Market Insights
North America is the largest region in the flight inspection market, supported by extensive commercial and defense aviation infrastructure, stringent FAA regulatory compliance mandates, and continued investment in NextGen navigation system modernization underpinning sustained regional demand.
The United States is the dominant player in the North America flight inspection market during the forecast period, due to the high volume of flight inspection fleet purchases and the increasing regulatory focus on the validation of satellite-based navigation. Canada is supporting regional growth via the expansion of investments in airport infrastructure and modernization of air navigation service providers.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Flight Inspection Market Insights
Europe was one of the key markets for flight inspection during the year 2025 owing to factors like SESAR standardization program within the region, dense cross-border corridors of airspace in the region, and the increased need for regulatory harmonization led by EASA.
Germany is one of the major markets in Europe owing to its extensive airport infrastructure and strong regulatory compliance framework under EASA oversight. Other countries such as France and the UK are also contributing to market growth through expanding air navigation service provider fleet modernization programs.
Asia Pacific Flight Inspection Market Insights
Asia Pacific is the fastest-growing market in the flight inspection industry, driven by China's large-scale airport construction programs and rapid expansion of aviation infrastructure supported by stringent national air safety compliance requirements.
China is one of the main growth drivers in the Asia Pacific flight inspection market, owing to rapid airport expansion and rising investment in navigation aid modernization under national aviation infrastructure programs. India and Japan are also contributing to regional growth through expanding domestic airport construction and performance-based navigation procedure deployment.
Middle East & Africa and Latin America Flight Inspection Market Insights
Middle East & Africa and Latin American regions are gradually expanding flight inspection adoption as airport infrastructure and defense aviation investment grows across both regions, supported by increasing regulatory emphasis on navigation aid compliance and airspace modernization.
Brazil is set to be a prominent Latin American market fueled by growing airport infrastructure investment and rising demand for navigation aid calibration services. The Middle East & Africa region has the UAE and Saudi Arabia investing in modern aviation infrastructure that is gradually increasing demand for flight inspection across their expanding commercial and defense aviation sectors.
Market Dynamics
Growth Drivers: Rising air traffic volumes and airport infrastructure modernization driving market growth
Increasing global air traffic volumes and rising airport infrastructure investment are among the primary drivers of the flight inspection market, as growing passenger and cargo aviation demand requires continuous expansion and calibration of navigation aid networks. Stringent ICAO and national aviation authority regulatory mandates requiring periodic validation of Instrument Landing Systems, VOR, DME, and GNSS-based navigation procedures continue to sustain structural demand for specialized flight inspection aircraft and services across commercial and defense aviation sectors worldwide.
Market forces that are driving the industry include increasing application of performance based navigation procedures and satellite aided communications, navigation, and surveillance systems, which will necessitate new calibration and inspection services. The increase in the modernization programs for defense aviation focusing on airspace security and readiness, alongside investments in automation of data transfer by the service providers, will continue to drive the demand throughout the forecast period.
Restraints: High fleet procurement costs and lengthy deployment timelines limiting market expansion
One of the factors that acts as a barrier to market growth is the high capital cost of procuring and equipping specialized flight inspection aircraft with calibration sensors and avionics systems, which can restrict fleet expansion among smaller air navigation service providers and defense agencies with constrained budgets.
Furthermore, the long duration required in the procurement process of certifying new aircraft inspection fleets is another challenge in the expansion of flight inspection services providers in developing countries with very little infrastructure. The reliance on special equipment calibration companies adds to the cost burden and makes it difficult to offer such services consistently.
Opportunities: Expansion of automated inspection technology and emerging market airport development creating new growth avenues
The market is witnessing new growth avenues driven by increasing provider investment in AI-driven analytics, automated data transfer, and digital mission control systems that improve inspection accuracy and reduce mission turnaround time, addressing rising demand for real-time compliance monitoring across commercial and defense aviation networks.
There is considerable growth opportunity in expanding flight inspection service and aircraft procurement penetration across emerging Asia Pacific, Middle East, and Latin American markets undergoing large-scale airport infrastructure development. Continued investment in Flight Inspection as a Service (FIaaS) contract models is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
- 2025: The FAA awarded a fleet modernization contract to Bombardier Specialized Aircraft integrating digital mission control and GNSS signal validation across its flight inspection aircraft.
- 2025: Aerodata AG delivered its upgraded flight inspection system to a European air navigation service provider for satellite-based navigation aid calibration.
- 2026: Collins Aerospace introduced an enhanced automated flight inspection suite integrating AI-driven analytics for real-time ILS and VOR calibration reporting.
- 2026: Norwegian Special Mission AS expanded its flight inspection fleet with a new Beechcraft King Air 350 platform equipped for GNSS and PBN procedure validation.
Flight Inspection Market key players are:
- Aerodata AG
- Norwegian Special Mission AS
- Safran S.A.
- Textron Inc.
- Bombardier Inc.
- Collins Aerospace (RTX Corporation)
- Leonardo S.p.A.
- Thales Group
- Honeywell International Inc.
- Elbit Systems Ltd.
- L3Harris Technologies, Inc.
- Universal Avionics Systems Corporation
- Garmin Ltd.
- Saab AB
- Diamond Aircraft Industries GmbH
- Pilatus Aircraft Ltd.
- Sierra Nevada Corporation
- Cobham Aviation Services
- Flight Precision Ltd.
- Aerotech Flight Inspection Services Ltd.
Flight Inspection Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 9.64 Billion |
| Market Size by 2035 | USD 1.69 Billion |
| CAGR | CAGR of 4.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Platform Type (Fixed-Wing Aircraft, Rotary-Wing Aircraft) • By System Architecture (Onboard Integrated Systems, Portable Roll-On/Roll-Off Systems) • By End-User (Commercial Airports, Defense & Military Airports) • By Inspection Type (Periodic Routine Inspection, On-Demand Inspection, Commissioning/ Site Acceptance) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Aerodata AG, Norwegian Special Mission AS, Safran S.A., Textron Inc., Bombardier Inc., Collins Aerospace (RTX Corporation), Leonardo S.p.A., Thales Group, Honeywell International Inc., Elbit Systems Ltd., L3Harris Technologies, Inc., Universal Avionics Systems Corporation, Garmin Ltd., Saab AB, Diamond Aircraft Industries GmbH, Pilatus Aircraft Ltd., Sierra Nevada Corporation, Cobham Aviation Services, Flight Precision Ltd., Aerotech Flight Inspection Services Ltd. |
Frequently Asked Questions
The Flight Inspection Market is expected to grow at a CAGR of 4.60% from 2026 to 2035.
The Flight Inspection Market was valued at USD 6.15 Billion in 2025.
The market is driven by rising global air traffic volumes and increasing regulatory mandates requiring periodic calibration of navigation aids and airport systems.
The Fixed-Wing Aircraft segment dominated the Flight Inspection Market in 2025, accounting for more than 70.00% market share.
The North America region dominated the Flight Inspection Market in 2025, accounting for the largest share of total revenue.
