
Integrated Cloud Management Platform Market Report Scope & Overview:
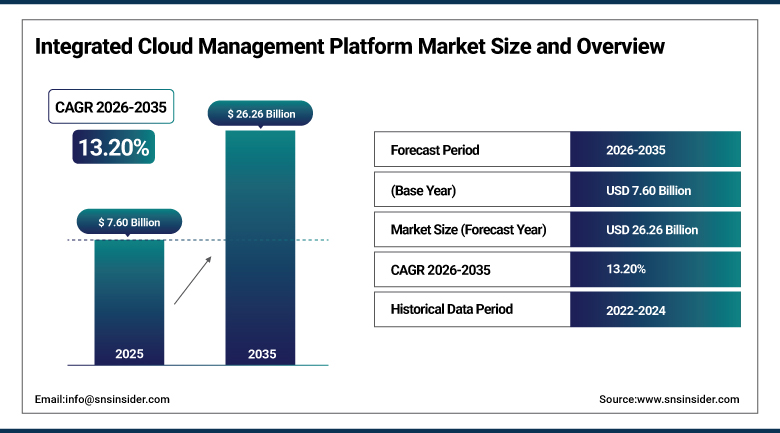
The Integrated Cloud Management Platform Market was valued at USD 7.60 Billion in 2025 and is expected to reach USD 26.26 Billion by 2035, growing at a CAGR of 13.20% from 2026-2035.
The Integrated Cloud Management Platform Market covers software and services that give enterprises a single control layer to provision, govern, monitor, secure, automate and optimize workloads across public clouds, private clouds, data centers and edge sites. Core functions include self-service catalogs, orchestration, cost visibility and FinOps, policy and compliance, observability, and lifecycle management of virtual machines, containers and, increasingly, AI and GPU workloads. Demand is rising because most enterprises run several clouds, cloud and AI bills are growing quickly, and licensing changes among virtualization vendors are pushing customers to re-evaluate infrastructure. Vendors are adding agentic automation, sovereignty controls and cost governance, and many are consolidating through acquisitions to offer end-to-end platforms for hybrid operations.
⮞Hybrid platforms are being rebuilt around AI and sovereignty. At its NEXT 2026 conference in Chicago in April 2026, Nutanix announced that Nutanix Cloud Platform gained capabilities for running AI workloads, planned support for the AWS European Sovereign Cloud and Google Cloud C3 bare-metal instances, and added on-premises cost governance and usage metering in Nutanix Cloud Manager. The company also detailed a planned NetApp ONTAP external storage option for the second half of 2026, NKP Metal for bare-metal Kubernetes, and updates to its Agentic AI stack, with more than 100 partners participating.
To Get more information Integrated Cloud Management Platform Market - Request Free Sample Report
Integrated Cloud Management Platform Market Trends
- Consolidation of FinOps, cost governance and automation into single platforms
- Migration of virtualization customers to alternative private cloud stacks
- Support for GPU, AI and Kubernetes workloads alongside virtual machines
- Rising demand for sovereign cloud and data residency controls
- Autonomous execution of optimization actions instead of dashboards
- Expansion of managed services and partner ecosystems for multi-cloud operations
U.S. Integrated Cloud Management Platform Market Outlook
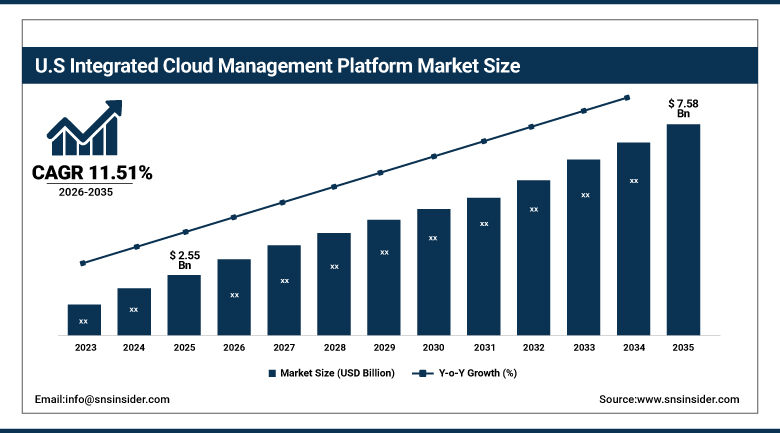
The U.S. Integrated Cloud Management Platform Market was valued at USD 2.55 Billion in 2025 and is expected to reach USD 7.58 Billion by 2035, growing at a CAGR of 11.51% from 2026-2035.
The U.S. Integrated Cloud Management Platform Market is the largest national market in North America, anchored by the world's biggest hyperscalers, the headquarters of most leading platform vendors and a large base of enterprises that run workloads across several clouds. Banks, healthcare systems, retailers, technology firms and federal agencies buy platforms for governance, cost control and security, and the rapid growth of AI spending is pushing finance and engineering teams to adopt FinOps practices. Licensing changes in the virtualization market are prompting large customers to renegotiate or migrate, which is reshaping vendor competition. Demand is steady rather than explosive because many buyers already operate mature tools.
⮞Virtualization's largest vendor is repositioning as a private cloud platform. On June 17, 2025, Broadcom announced general availability of VMware Cloud Foundation 9.0, a single private cloud platform spanning data centers, edge and managed cloud environments. The release adds a unified management console, developer self-service blueprints, embedded Kubernetes, cost visibility with showback and chargeback, and VMware Private AI Foundation with NVIDIA with GPU-as-a-Service. Broadcom says 87% of its top 10,000 VMware customers have committed to the platform, and support for VCF 8 ends in October 2027.
Integrated Cloud Management Platform Market Segment Analysis
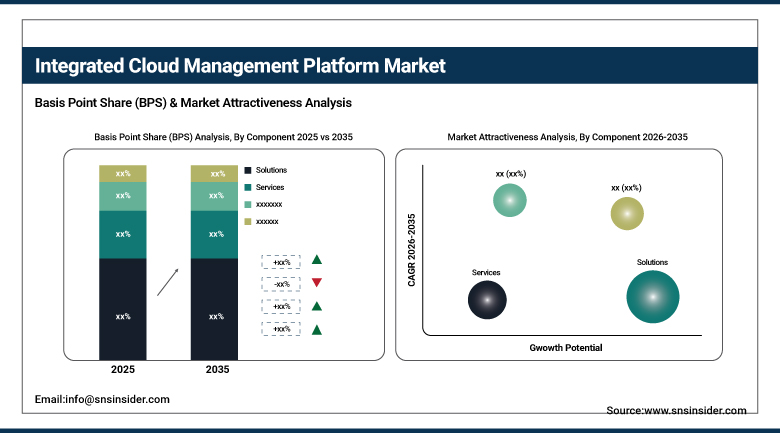
- By Component, the Solutions segment dominated the Integrated Cloud Management Platform Market with approximately 66.40% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 15.30%.
- By Deployment Model, the Public Cloud segment dominated the Integrated Cloud Management Platform Market with approximately 44.80% share in 2025, while the Hybrid Cloud segment is the fastest growing with a CAGR of approximately 15.60%.
- By Application, the Cost Management and Optimization segment dominated the Integrated Cloud Management Platform Market with approximately 27.60% share in 2025, while the Security and Compliance segment is the fastest growing with a CAGR of approximately 16.20%.
- By Enterprise Size, the Large Enterprises segment dominated the Integrated Cloud Management Platform Market with approximately 64.30% share in 2025, while the Small and Medium Enterprises segment is the fastest growing with a CAGR of approximately 15.40%.
- By End-User, the IT and Telecom segment dominated the Integrated Cloud Management Platform Market with approximately 24.80% share in 2025, while the Healthcare and Life Sciences segment is the fastest growing with a CAGR of approximately 16.00%.
By Component, Solutions Dominates the Integrated Cloud Management Platform Market and Services Grows Fastest
Solutions lead because software licenses and subscriptions for provisioning, orchestration, cost management, governance and monitoring form the core of every deployment. Vendors such as Broadcom, Nutanix, IBM, Flexera, HPE and ServiceNow sell platforms that enterprises use for years, and upgrades add recurring revenue. Because customers need the software before they can use any service, solutions take the largest share even as professional and managed services grow around them.
Services are growing fastest as enterprises seek help with migration, integration and ongoing operations across several clouds. Programs such as CloudBolt's EZShift, introduced in 2025 to guide VMware customers moving automation to its platform, show how vendors bundle advisory support with software. Managed services providers also run multi-cloud environments for companies lacking skills, and FinOps consulting is rising as AI spending increases. Skills shortages sustain demand for expert services.
By Deployment Model, Public Cloud Dominates the Integrated Cloud Management Platform Market and Hybrid Cloud Grows Fastest
Public cloud leads because most enterprise cloud spending still goes to AWS, Microsoft Azure and Google Cloud, and platforms are used first to control cost, security and governance in these environments. Software-as-a-service management tools connect easily to public cloud accounts and deliver quick results, such as rightsizing and commitment management. The large and growing size of public cloud bills makes this the largest deployment area for management software.
Hybrid cloud is growing fastest as organizations keep sensitive and legacy workloads on private infrastructure while using public clouds for scale. VMware Cloud Foundation 9.0 and Nutanix Cloud Platform both target this need with unified private cloud and multi-cloud management, and sovereignty requirements in Europe push customers toward hybrid designs. Enterprises want one interface, one policy model and consistent cost reporting across environments, which favors integrated platforms.
By Application, Cost Management and Optimization Dominates the Integrated Cloud Management Platform Market and Security and Compliance Grows Fastest
Cost management and optimization is at the forefront as cloud and AI costs have become one of the big ticket items and finance professionals expect transparency. FinOps platforms enable showback, chargeback, forecasting and automation of rightsizing, and vendors have begun to consolidate themselves to be able to deliver an entire suite. Flexera purchased Spot by NetApp’s FinOps platform business in 2025, and ProsperOps and Chaos Genius in January 2026.
Security and compliance is growing fastest as regulators tighten rules on data residency, operational resilience and AI governance. Platforms add policy engines, configuration checks, confidential computing support and compliance dashboards, such as the SecOps dashboard in VMware Cloud Foundation 9.0. Sovereign cloud requirements in Europe and sector rules in banking and healthcare force buyers to centralize controls, making this the application with the highest growth.
By Enterprise Size, Large Enterprises Dominates the Integrated Cloud Management Platform Market and Small and Medium Enterprises Grows Fastest
Large enterprises lead because they run the most complex multi-cloud estates, with thousands of workloads across providers and business units, and they have the budgets and governance needs to justify enterprise platforms. They negotiate multi-year contracts, require integrations with ITSM and security tools, and often operate private clouds alongside public ones. Their scale means that even small percentage savings from optimization produce large returns, which supports high spending.
Small to medium-sized businesses are the fastest-growing sectors since cloud governance is easily available on simpler and subscription-based platforms without huge teams. Pay-as-you-go payment systems, automation and guided onboarding reduce the amount of work needed, and resellers package cloud management with cloud services. This comes against the backdrop of an increase in charges and security needs among many small businesses using more than one cloud service or SaaS solution.
By End-User, IT and Telecom Dominates the Integrated Cloud Management Platform Market and Healthcare and Life Sciences Grows Fastest
IT and telecom lead because service providers, software companies and network operators run the largest and most dynamic cloud footprints and were early adopters of automation. They manage multi-tenant platforms, edge sites and customer workloads, and they need metering, orchestration and observability at scale. Nutanix's tools for providers, including usage metering and monetization, reflect this demand. Their technical expertise also makes them fast adopters of new platform features.
Healthcare and life sciences are growing fastest as hospitals, insurers and pharmaceutical firms move clinical systems, imaging and research workloads to hybrid environments. They must satisfy strict privacy rules, so they favor platforms with strong policy enforcement, audit trails and data residency controls. Growth in genomics, medical imaging and AI-driven research also raises compute use, which increases the need to manage cost and performance across clouds.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
83.50 |
|
Europe |
United Kingdom |
28.30 |
|
Asia Pacific |
China |
36.40 |
|
Middle East & Africa |
United Arab Emirates |
31.20 |
|
Latin America |
Brazil |
45.60 |
North America Integrated Cloud Management Platform Market Insights
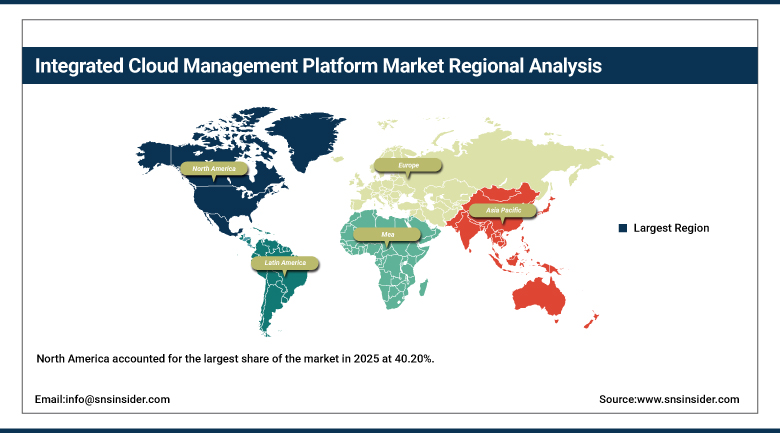
North America accounted for the largest share of the market in 2025 at 40.20%. The United States holds most regional value through hyperscalers, platform vendors such as Broadcom, IBM, Flexera, CloudBolt and ServiceNow, and a deep base of enterprise buyers. Canada contributes through banking, telecom and public sector deployments.
Competition is shaped by virtualization licensing changes, with many customers evaluating alternatives to their incumbent stack. Flexera has expanded its FinOps portfolio through acquisitions, and Nutanix held its .NEXT 2026 conference in Chicago. Growth is steady because the base is mature and buyers are consolidating tools rather than adding new ones.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Integrated Cloud Management Platform Market Insights
Europe held significant share of the market in 2025. The United Kingdom, Germany, France and the Nordic countries lead, with banking, manufacturing and public sector buyers prioritizing compliance and data sovereignty. The region's regulations on data residency, operational resilience and AI create strong demand for governance features.
Sovereign cloud offerings are a major theme, and Nutanix planned support for the AWS European Sovereign Cloud in 2026. European customers also seek alternatives to dependence on a single hyperscaler or virtualization vendor, which favors open, multi-platform management layers. Local service providers and integrators play a large role in implementation.
Asia Pacific Integrated Cloud Management Platform Market Insights
Asia Pacific is the fastest-growing region, advancing at a CAGR of 16.80% during 2026-2035. China, India, Japan, Australia and Southeast Asia lead through rapid cloud adoption, digital transformation programs and growth of data center capacity. Enterprises in India and Southeast Asia move quickly to public and hybrid clouds, creating demand for governance and cost control.
Regional hyperscalers and local cloud providers compete with global platforms, and governments encourage local cloud and AI infrastructure. AI investment in the region is growing GPU workloads that need scheduling and cost tracking. Managed service providers and system integrators, including Indian IT firms that partner with Nutanix, extend platform reach to mid-sized companies.
MEA & Latin America Integrated Cloud Management Platform Market Insights
The Middle East and Africa Integrated Cloud Management Platform Market is growing at a strong pace. The United Arab Emirates and Saudi Arabia lead through national cloud and AI strategies and the arrival of hyperscaler regions, while South Africa adds enterprise demand. Government programs require sovereign controls, which favors platforms with local hosting and policy features.
Latin America Integrated Cloud Management Platform Market is also experiencing robust growth. Brazil and Mexico lead through banking, retail and telecom, and growing local cloud regions help adoption. Currency volatility and skills shortages restrain spending, but managed services and subscription pricing make integrated platforms accessible to more companies.
Market Dynamics
Growth Drivers: Multi-Cloud Complexity, Rising Cloud and AI Spend and Hybrid Strategies
Multi-cloud complexity is the primary driver. Most large enterprises use several public clouds plus private infrastructure, and each has different tools, policies and billing. An integrated platform reduces duplicated effort, enforces consistent controls and gives a single view of resources, which becomes essential as environments grow.
Rising cloud and AI spend and hybrid strategies add momentum. AI training and inference raise compute bills quickly, so finance teams demand cost governance, and platforms that automate savings, such as those Flexera acquired in 2026, find ready buyers. Hybrid strategies, driven by sovereignty and performance needs, keep private clouds relevant and expand the scope of management software.
Restraints: Integration Complexity, Vendor Lock-In Concerns and Skills Shortages
The challenges of integration make it difficult to adopt, since linking a management platform to multiple clouds, legacy solutions, identity providers, and ticketing systems is a cumbersome task. The variations between the API of the different providers and the fast pace at which clouds services evolve make it difficult to maintain up-to-date integrations.
Vendor lock-in concerns and skills shortages add friction. Buyers worry about relying on a single platform vendor after licensing changes in the virtualization market, and many delay decisions while they evaluate alternatives. Shortages of cloud architects and FinOps specialists also slow rollouts and reduce the value captured from advanced features.
Opportunities: Agentic Automation, FinOps for AI and Sovereign Cloud
Agentic automation offers a significant opportunity, as platforms move from dashboards to autonomous execution of optimization, remediation and provisioning tasks. Flexera's stated aim that organizations need execution, not only dashboards, and Nutanix's agentic AI stack show vendors converting recommendations into automated action, which can justify higher prices.
FinOps for AI and sovereign cloud provide further opportunities. Tracking GPU, token and data cloud consumption requires new metering and allocation tools, and Snowflake and Databricks optimization is a growing niche. Sovereign cloud mandates in Europe and the Middle East create demand for platforms that enforce residency and operate in air-gapped or locally hosted environments.
Recent Developments:
- 2026: Flexera acquired ProsperOps, an autonomous cloud commitment management provider that manages about USD 6 billion of annual cloud usage, and Chaos Genius, a data FinOps platform for Snowflake and Databricks, extending its suite toward FinOps for AI and data clouds.
- 2025: Flexera agreed to acquire Spot by NetApp's FinOps business, adding Kubernetes cost management and commitment management to its portfolio and expanding its ecosystem of FinOps managed service providers.
- 2025: CloudBolt introduced EZShift, a guided migration program that helps VMware customers move self-service automation from Aria Automation to its platform and manage vSphere, OpenShift Virtualization, Proxmox and Hyper-V from one console.
Integrated Cloud Management Platform Market Key Players are:
- Broadcom Inc. (VMware)
- Nutanix, Inc.
- IBM Corporation (Apptio, HashiCorp)
- Hewlett Packard Enterprise (Morpheus Data)
- Flexera
- CloudBolt Software
- Microsoft Corporation
- Amazon Web Services
- Google Cloud
- Oracle Corporation
- Red Hat, Inc.
- ServiceNow, Inc.
- Salesforce, Inc.
- BMC Software
- Cisco Systems
- Dell Technologies
- Rubrik
- CloudZero
- Scalr
- Snow Software
Integrated Cloud Management Platform Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 7.60 Billion |
| Market Size by 2035 | USD 26.26 Billion |
| CAGR | CAGR of 13.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Solutions, Services) • By Deployment Model (Public Cloud, Private Cloud, Hybrid Cloud) • By Application (Cost Management and Optimization, Security and Compliance, Performance Monitoring, Workload and Resource Management, Cloud Automation and Orchestration, Others) • By Enterprise Size (Large Enterprises, Small and Medium Enterprises) • By End-User (IT and Telecom, BFSI, Healthcare and Life Sciences, Retail and E-Commerce, Government, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Broadcom Inc. (VMware), Nutanix, Inc., IBM Corporation (Apptio, HashiCorp), Hewlett Packard Enterprise (Morpheus Data), Flexera, CloudBolt Software, Microsoft Corporation, Amazon Web Services, Google Cloud, Oracle Corporation, Red Hat, Inc., ServiceNow, Inc., Salesforce, Inc., BMC Software, Cisco Systems, Dell Technologies, Rubrik, CloudZero, Scalr, Snow Software |

Frequently Asked Questions
Key players include Broadcom (VMware), Nutanix, IBM, HPE, Flexera, CloudBolt, Microsoft, Amazon Web Services, Google Cloud, Oracle, Red Hat, ServiceNow, BMC Software, Cisco and Dell Technologies.
Key opportunities include agentic automation that executes optimization actions, FinOps for AI and data clouds, and sovereign cloud platforms for regulated and government buyers.
The major growth factor is the complexity of multi-cloud and hybrid environments, combined with rapidly growing cloud and AI spending that requires unified governance and cost control.
By Component, the Solutions segment dominated the market with approximately 66.40% share in 2025, owing to the central role of platform software in provisioning, governance and cost control.
North America dominated the market with a share of 40.20% in 2025, supported by hyperscalers, leading platform vendors and a large base of enterprises in the United States.
