
Laboratory Centrifuges Market Report Scope & Overview:
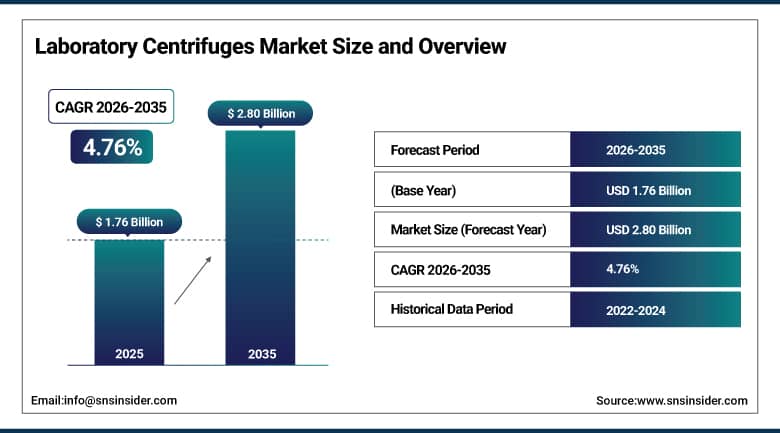
The Laboratory Centrifuges Market was valued at USD 1.76 Billion in 2025 and is expected to reach USD 2.80 Billion by 2035, growing at a CAGR of 4.76% from 2026-2035.
Laboratory centrifuges spin samples at controlled speeds to separate components by density, a function that sits quietly behind an enormous share of everyday clinical diagnostics, drug discovery workflows, and academic research. The equipment spans compact benchtop microcentrifuges used for routine molecular biology work through floor-standing ultracentrifuges capable of separating subcellular particles at hundreds of thousands of times the force of gravity, and the accessories market surrounding rotors, tubes, and adapters continues to generate meaningful recurring revenue alongside the core instruments themselves. Growth is supported by increased investment in research and development, wider availability of research grants across academic and government institutions, and a rising prevalence of infectious and chronic disease that continues to drive higher volumes of sample testing and cell-based research.
In August 2026, Thermo Fisher Scientific launched its X2 and S2 Series Centrifuges, becoming the first manufacturer to offer a complete refrigerated centrifuge portfolio featuring natural refrigerants under its GreenCool Technology, which carries a low global warming potential of 3 and complies with both European Union and U.S. Environmental Protection Agency F-gas regulations.
To Get More Information On Laboratory Centrifuges Market - Request Free Sample Report
Laboratory Centrifuges Market Trends
-
Rising adoption of natural refrigerant cooling systems replacing higher global-warming-potential refrigerants.
-
Growing demand for single-use, closed-system centrifuges supporting gene and cell therapy manufacturing.
-
Expanding integration of app-compatible remote monitoring and data management within centrifuge platforms.
-
Increasing adoption of tool-free rotor exchange systems reducing turnaround time in busy multi-user labs.
-
Rising replacement demand as ageing centrifuge fleets across academic and clinical labs reach end of service life.
-
Growing acquisition activity as established manufacturers expand product breadth through targeted purchases.
U.S. Laboratory Centrifuges Market Overview
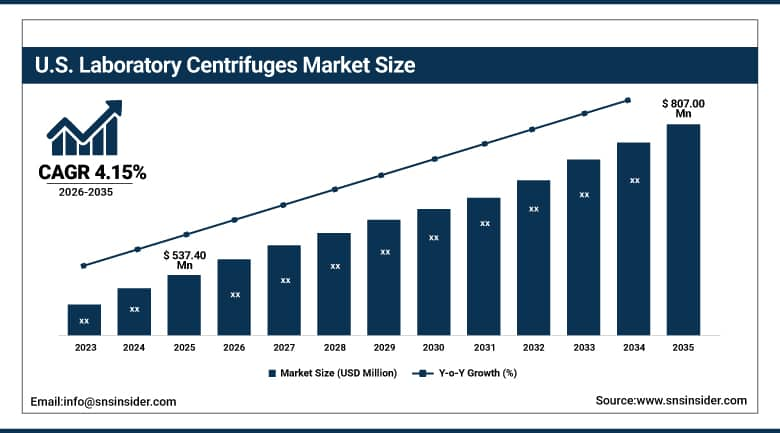
The U.S. Laboratory Centrifuges Market was valued at USD 537.40 Million in 2025 and is expected to reach USD 807.00 Million by 2035, growing at a CAGR of 4.15% from 2026-2035.
The U.S. Laboratory Centrifuges Market benefits from a highly developed healthcare system with extensive hospital and research laboratory networks, sustained government and private research funding, and the presence of leading centrifuge manufacturers headquartered in the country that continue to compete on automation, safety, and sustainability. Continued clinical diagnostics volume, reinforced by an ageing population and rising chronic disease prevalence, continues to sustain steady replacement and new-purchase demand across hospital and reference laboratory networks nationwide. Leading manufacturers continue to introduce natural refrigerant cooling technology and tool-free rotor exchange systems aimed at improving both sustainability credentials and day-to-day operational efficiency for busy, multi-user clinical and research environments. Continued growth in precision medicine and high-throughput genomic testing is expected to sustain strong demand growth for advanced refrigerated and floor-model centrifuge systems throughout the forecast period.
In April 2025, Thermo Fisher Scientific introduced its Cryofuge series of refrigerated floor models, targeting precision medicine and high-throughput clinical laboratories with enhanced automation and efficiency capabilities designed to support increasingly demanding sample processing volumes.
Laboratory Centrifuges Market Segment Analysis
-
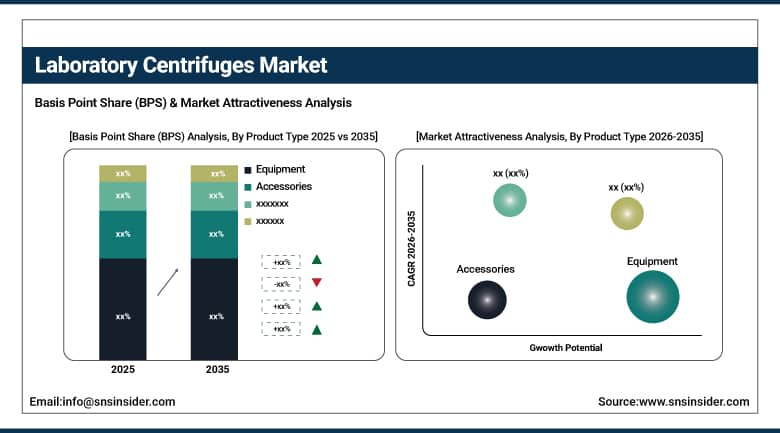
By Product Type, the Equipment segment dominated the market with a 76.47% share in 2025, while the Accessories segment is the fastest growing with a CAGR of 7.12% during 2026-2035.
-
By Equipment Type, the Multipurpose Centrifuges segment dominated the market with a 41.30% share in 2025, while the Ultracentrifuges segment is the fastest growing with a CAGR of 6.45% during 2026-2035.
-
By Intended Use, the Clinical segment dominated the market with a 52.79% share in 2025, while the Pre-Clinical Research segment is the fastest growing with a CAGR of 6.36% during 2026-2035.
-
By Application, the Diagnostics segment dominated the market with a 37.34% share in 2025, while the Genomics and Proteomics segment is the fastest growing with a CAGR of 6.95% during 2026-2035.
-
By End User, the Hospitals and Diagnostic Laboratories segment dominated the market with a 46.90% share in 2025, while the Biotech and Pharma Companies segment is the fastest growing with a CAGR of 6.88% during 2026-2035.
By Product Type, Equipment Dominates the Market and Accessories Grows Fastest
Equipment dominated the market in 2025 with a 76.47% share. The physical centrifuge units themselves, spanning benchtop, floor-standing, and specialised research platforms, represent the primary capital purchase for every laboratory building or upgrading its sample processing capability, and this fundamental equipment requirement continues to anchor the product type as the clear largest category across the broader laboratory centrifuges market. Because centrifuges are durable, long-lived instruments that a laboratory typically expects to run reliably for a decade or more, the equipment purchase decision carries substantial weight, and manufacturers continue to differentiate on safety features, automation, and total cost of ownership rather than price alone, reflecting how central these instruments are to a laboratory's overall sample processing workflow and how disruptive an equipment failure or unplanned downtime event can genuinely be to ongoing clinical or research operations.
Accessories are projected to be the fastest-growing product category over the forecast period, registering a CAGR of 7.12%. As replacement demand accelerates and laboratories continue investing in existing equipment fleets rather than purchasing entirely new units, ongoing demand for rotors, tubes, adapters, and other consumable components continues to generate reliable, recurring revenue that grows faster than the underlying equipment market itself. This dynamic mirrors a pattern common across capital equipment industries more broadly, where a large, ageing installed base of durable equipment generates a steadily expanding stream of aftermarket consumable and replacement part demand that can grow considerably faster than new unit sales, particularly as manufacturers continue introducing specialised rotor designs optimised for increasingly narrow research applications.
By Equipment Type, Multipurpose Centrifuges Dominates the Market and Ultracentrifuges Grows Fastest
Multipurpose centrifuges dominated the market in 2025 with a 41.30% share. Their versatility across a broad range of routine clinical and research applications, from blood separation through general sample preparation, continues to make them the default choice for laboratories that need a single, adaptable instrument capable of handling diverse daily workflows rather than a specialised, single-purpose system. Smaller laboratories and clinics in particular often standardise around a single multipurpose platform capable of handling the full range of everyday sample processing tasks they encounter, and this practical versatility, combined with generally lower capital cost relative to specialised ultracentrifuge or high-speed floor-model alternatives, continues to sustain multipurpose centrifuges as the largest equipment type category by a considerable margin.
Ultracentrifuges are projected to be the fastest-growing equipment type over the forecast period, registering a CAGR of 6.45%, as rising gene therapy and virus vector research continues to demand the extremely high rotational speeds these systems provide for separating the smallest subcellular particles and macromolecules. Continued expansion of cell and gene therapy manufacturing pipelines is expected to sustain above-market growth for this specialised, higher-value equipment category through the forecast period, and because ultracentrifuges typically command substantially higher price points than general-purpose alternatives, this category's growing volume share represents an even more pronounced shift in overall market revenue mix toward specialised, high-value equipment relative to more commoditised general-purpose platforms.
By Intended Use, Clinical Dominates the Market and Pre-Clinical Research Grows Fastest
Clinical applications dominated the market in 2025 with a 52.79% share, reflecting the sheer volume of routine diagnostic testing performed across hospital laboratories, reference labs, and blood banks worldwide. Centrifugation remains an indispensable step in an enormous share of everyday clinical testing workflows, from basic blood chemistry through more specialised diagnostic panels, sustaining clinical applications as the largest intended-use category by a considerable margin. The predictable, recurring nature of clinical testing volume, driven by routine patient care rather than discretionary research funding cycles, continues to give this intended-use category an unusually stable demand base that holds up well even during periods of broader economic uncertainty when research budgets elsewhere may face genuine pressure.
Pre-clinical research is projected to be the fastest-growing intended-use category over the forecast period, registering a CAGR of 6.36%, as increased investment in drug discovery and translational research continues to expand demand for centrifuges within academic, government, and pharmaceutical research settings. Rising research grant availability and expanding biotechnology funding continue to support sustained above-market growth for this category relative to the broader clinical-dominated intended-use mix, and as pharmaceutical companies continue pursuing increasingly complex biologic and cell-based drug candidates, the sample preparation and purification workflows underlying pre-clinical research continue to demand more sophisticated centrifugation capability than earlier generations of small-molecule drug discovery ever required.
By Application, Diagnostics Dominates the Market and Genomics and Proteomics Grows Fastest
Diagnostics dominated the market in 2025 with a 37.34% share. This application continues to serve as the cornerstone of the broader laboratory centrifuges market, given the sheer scale of routine testing volume clinical laboratories process daily, and this established, high-volume application continues to anchor diagnostics as the clear leading category across the broader market. From routine blood chemistry panels through more specialised infectious disease and cancer diagnostic testing, centrifugation continues to serve as an essential, largely invisible step that clinicians and patients alike rarely think about directly but that nonetheless underpins an enormous share of the diagnostic information modern medicine depends upon every single day across every type of healthcare setting.
Genomics and proteomics is projected to be the fastest-growing application over the forecast period, registering a CAGR of 6.95%, as the shift toward personalised medicine and expanding genomic and proteomic research continues to require precise, high-speed separation of nucleic acids and proteins from complex biological samples. Continued growth in precision medicine investment is expected to sustain above-market growth for this increasingly important application category, and as genomic sequencing costs continue falling while diagnostic and research applications for genomic and proteomic data continue expanding, the underlying volume of samples requiring specialised centrifugation for nucleic acid and protein purification continues to climb at a pace that outstrips the broader diagnostics-dominated application mix.
By End User, Hospitals and Diagnostic Laboratories Dominates the Market and Biotech and Pharma Companies Grows Fastest
Hospitals and diagnostic laboratories dominated the market in 2025 with a 46.90% share. The continuous, high-volume sample processing these facilities perform on a daily basis, spanning routine blood work through more complex diagnostic panels, continues to anchor this end-user category as the largest source of laboratory centrifuge demand across the broader market. These facilities also tend to operate the largest individual fleets of centrifuges of any end-user category, often maintaining redundant equipment across multiple departments and shifts to ensure continuous testing capability, and this operational scale continues to reinforce hospitals and diagnostic laboratories' position as the clear anchor of overall market demand.
Biotech and pharma companies are projected to be the fastest-growing end-user category over the forecast period, registering a CAGR of 6.88%, as gene-therapy pipelines continue to scale and demand single-use, closed-system centrifuges capable of meeting stringent contamination control and regulatory requirements. Continued biopharmaceutical manufacturing capacity expansion is expected to sustain above-market growth for this end-user category relative to the broader hospital-dominated end-user mix, as these organisations increasingly require centrifugation capability validated to genuinely exacting Good Manufacturing Practice standards that differ meaningfully from the equipment specifications sufficient for conventional clinical or academic research use.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
82.60% |
|
Europe |
Germany |
29.15% |
|
Asia Pacific |
China |
37.40% |
|
Latin America |
Brazil |
25.60% |
|
Middle East & Africa |
United Arab Emirates |
22.90% |
North America Laboratory Centrifuges Market Insights
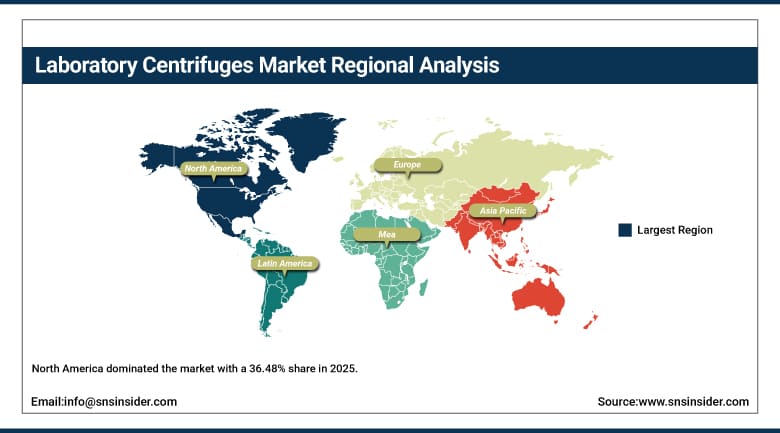
North America dominated the market with a 36.48% share in 2025. Advanced healthcare infrastructure, extensive hospital and research laboratory networks, and the concentration of leading centrifuge manufacturers headquartered within the region continue to underpin a strong foundation of both clinical and research-driven demand. The region's deep base of academic medical centres, national laboratories, and venture-backed biotechnology companies continues to generate sustained, diversified demand across every equipment category, from routine clinical multipurpose centrifuges through specialised ultracentrifuge systems supporting the most advanced gene therapy research programs anywhere in the world.
Canada contributes meaningful incremental regional demand through its own publicly funded healthcare and research infrastructure, supported by consistent government research funding that continues to sustain laboratory equipment budgets across major academic institutions. Continued investment in precision medicine, biopharmaceutical manufacturing, and clinical diagnostics capacity is expected to keep North America in the lead through the forecast period, even as its growth rate trails the faster-scaling markets of Asia Pacific, where healthcare and research infrastructure continues to expand rapidly from a comparatively smaller installed base.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Laboratory Centrifuges Market Insights
Asia Pacific is projected to be the fastest-growing region over the forecast period, registering a CAGR of approximately 7.76%. Rapidly expanding healthcare infrastructure, growing biopharmaceutical manufacturing capacity, and rising government investment in research and diagnostics continue to accelerate regional adoption of laboratory centrifuge technology across both established and emerging regional markets. Several major regional governments have made biotechnology and precision medicine an explicit strategic priority, and this policy focus continues to translate directly into new laboratory construction and equipment procurement across both public research institutions and private biopharmaceutical manufacturers.
China anchors regional demand through its expanding hospital network and growing domestic biopharmaceutical manufacturing base, supported by sustained government investment aimed at building genuine self-sufficiency across critical life sciences supply chains. Japan and South Korea contribute additional regional depth through established research and diagnostics sectors with decades of laboratory infrastructure investment behind them, while India's rapidly expanding private hospital and clinical laboratory sector continues to add meaningful incremental regional growth as domestic healthcare access and diagnostic testing volume both continue climbing steadily.
Europe Laboratory Centrifuges Market Insights
Europe holds a significant share of the global market, anchored by Germany's substantial hospital sector and its position as home to leading laboratory equipment manufacturers with deep research and development capability built over decades of serving some of the world's most demanding clinical and industrial customers. The region's mature healthcare and research infrastructure continues to sustain steady demand across every major centrifuge category, reinforced by a dense network of academic medical centres and publicly funded research institutes that maintain consistent equipment replacement budgets year after year.
The United Kingdom, France, and Italy add consistent regional demand as national health systems and research institutions continue extending diagnostic and research capacity, supported by strong national commitments to publicly funded healthcare and biomedical research infrastructure. Continued regional investment in precision medicine and biopharmaceutical manufacturing is expected to sustain steady growth across the broader European market through the forecast period, even as overall regional growth continues trailing the faster-expanding markets developing across Asia Pacific.
MEA and Latin America Laboratory Centrifuges Market Insights
The Middle East and Africa region is supported by growing healthcare infrastructure investment across the United Arab Emirates and Saudi Arabia, where regional governments continue expanding hospital and diagnostic laboratory capacity as part of broader healthcare modernisation strategies aimed at building world-class medical infrastructure to serve rapidly growing, increasingly urbanised regional populations.
Latin America is anchored by Brazil, where a growing domestic healthcare and research sector sustains steady demand for laboratory centrifuge technology, supported by the country's substantial public health infrastructure and its position as a significant regional pharmaceutical manufacturing hub. Mexico contributes further incremental growth as regional healthcare access and diagnostic capacity continue to expand gradually, reinforced by the broader region's growing integration into global pharmaceutical and diagnostics supply chains.
Market Dynamics
Growth Drivers: Research Investment and Rising Disease Testing Volumes
Increased investment in research and development, combined with wider availability of research grants across academic and government institutions, stands as the primary growth driver, as expanding funding continues to support laboratory infrastructure investment across universities, government research institutes, and biopharmaceutical companies worldwide. National governments across several major economies have expanded life sciences research budgets meaningfully in recent years, recognising biotechnology as a strategic economic priority, and this sustained funding environment continues to support laboratory equipment purchasing at a pace that has outstripped general inflation across most major research markets globally.
A rising prevalence of infectious and chronic diseases represents a second major driver, as this trend continues to drive higher volumes of clinical sample testing and cell-based research across hospital and diagnostic laboratory networks. Technological advancements, including innovative rotor designs and expanding applications for laboratory centrifuges beyond conventional diagnostics, continue to further reinforce sustained demand across the broader market, as an ageing global population combined with rising rates of chronic conditions including cancer, diabetes, and cardiovascular disease continues to generate a steadily growing volume of diagnostic testing that shows little sign of levelling off in the foreseeable future.
Restraints: Trade Policy Impact and High Equipment Replacement Costs
Recent trade policy shifts, including tariffs affecting cross-border equipment and component trade, present a genuine restraint, with recent industry analysis attributing a measurable reduction in forecast growth directly to the impact of tariffs between the United States and other countries on this globally traded equipment category, since centrifuge manufacturing and component supply chains typically span multiple countries and remain genuinely sensitive to disruptions in cross-border trade policy that can meaningfully affect both equipment pricing and delivery timelines.
High equipment replacement costs present a further restraint, as advanced refrigerated and ultracentrifuge systems continue to command substantial capital investment, a cost profile that can delay replacement cycles for smaller laboratories and budget-constrained academic institutions operating with more limited capital equipment funding, particularly in emerging markets where currency fluctuation can add further unpredictability to the effective cost of importing sophisticated laboratory equipment from established international manufacturers.
Opportunities: Sustainability Innovation and Single-Use System Development
Continued development of natural refrigerant and energy-efficient cooling technology represents a substantial opportunity, as manufacturers that can deliver genuinely more sustainable centrifuge systems stand to capture demand from laboratories increasingly prioritising environmental credentials alongside performance and reliability in their equipment purchasing decisions, a shift that continues to gain momentum as institutional sustainability commitments increasingly extend down to individual departmental procurement choices rather than remaining purely aspirational corporate policy statements.
Continued expansion of single-use, closed-system centrifuge technology offers a further avenue for growth, as manufacturers that can deliver reliable, contamination-controlled systems suited to gene and cell therapy manufacturing are positioned to capture demand from a rapidly scaling advanced therapy manufacturing sector requiring genuinely differentiated equipment beyond conventional clinical and research centrifuges, particularly as regulatory agencies continue tightening contamination control expectations for advanced therapy manufacturing in ways that make conventional, reusable centrifuge systems increasingly difficult to validate for the most sensitive cell and gene therapy applications.
Recent Developments:
-
In September 2026, Eppendorf launched the SpinPro 8 R refrigerated high-speed centrifuge, its first floor-standing centrifuge developed following the integration of the Himac centrifuge business. The system supports capacities up to 6 L, 35 rotor options, sustainable CO₂-based cooling, and connected workflow features.
-
In June 2026, Thermo Fisher Scientific introduced its Thermo Scientific M Series Centrifuges, a new centrifuge platform developed for laboratory workflows requiring flexible capacity, performance, and ease of use. The launch expands Thermo Fisher’s centrifugation portfolio across research and laboratory applications.
-
In June 2026, Haier Biomedical launched the LX-155T750R high-speed refrigerated benchtop centrifuge, featuring ECO fastBlast pre-cooling technology. The 3-liter system is designed for high-throughput molecular biology and temperature-sensitive sample processing, with rapid cooling intended to reduce energy consumption and waiting time.
-
In May 2026, Drucker Diagnostics launched the DASH 24 high-capacity STAT centrifuge, designed for hospital laboratories. The system accommodates up to 24 tubes, reaches 4,000 ×g, and includes a digital touchscreen with programmable protocols for applications such as serum chemistry, coagulation, plasma, and urine processing.
Laboratory Centrifuges Market Key Players
-
Thermo Fisher Scientific Inc.
-
Danaher Corporation (Beckman Coulter)
-
Eppendorf SE
-
Andreas Hettich GmbH & Co. KG
-
Sartorius AG
-
Agilent Technologies, Inc.
-
Becton, Dickinson and Company
-
Qiagen N.V.
-
Kubota Corporation
-
NuAire, Inc.
-
Cardinal Health, Inc.
-
Labnet International, Inc.
-
Corning Incorporated
-
OHAUS Corporation
-
Hermle Labortechnik GmbH
-
Drucker Diagnostics
-
Fisherbrand (Thermo Fisher)
-
Sigma Laborzentrifugen GmbH
-
Grant Instruments Ltd.
-
Rotanta (Hettich)
Laboratory Centrifuges Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.76 Billion |
| Market Size by 2035 | USD 2.80 Billion |
| CAGR | CAGR of 4.76% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Equipment and Accessories) • by Equipment Type (Multipurpose Centrifuges, Microcentrifuges, Ultracentrifuges, and Floor-Standing Centrifuges) • by Intended Use (Clinical and Pre-Clinical Research) • by Application (Diagnostics, Drug Discovery, Genomics and Proteomics, and Blood Banking) • by End User (Hospitals and Diagnostic Laboratories, Biotech and Pharma Companies, and Academic and Research Institutes) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Thermo Fisher Scientific Inc., Danaher Corporation (Beckman Coulter), Eppendorf SE, Andreas Hettich GmbH & Co. KG, Sartorius AG, Agilent Technologies, Inc., Becton, Dickinson and Company, Qiagen N.V., Kubota Corporation, NuAire, Inc., Cardinal Health, Inc., Labnet International, Inc., Corning Incorporated, OHAUS Corporation, Hermle Labortechnik GmbH, Drucker Diagnostics, Fisherbrand (Thermo Fisher), Sigma Laborzentrifugen GmbH, Grant Instruments Ltd., Rotanta (Hettich) |

Frequently Asked Questions
Key players include Thermo Fisher Scientific Inc., Danaher Corporation, Eppendorf SE, Andreas Hettich GmbH & Co. KG, and Sartorius AG, among other laboratory equipment manufacturers.
Continued development of natural refrigerant, energy-efficient cooling technology and continued expansion of single-use, closed-system centrifuge technology represent the primary opportunities.
Growth is primarily driven by increased research and development investment, combined with rising prevalence of infectious and chronic diseases driving higher sample testing volumes.
By Product Type, Equipment dominated the market with a 76.47% share in 2025, reflecting its role as the primary capital purchase for laboratory sample processing capability.
North America dominated the market with a 36.48% share in 2025, supported by advanced healthcare infrastructure and extensive research laboratory networks.
