
Laminating Adhesives Market Report Scope and Overview
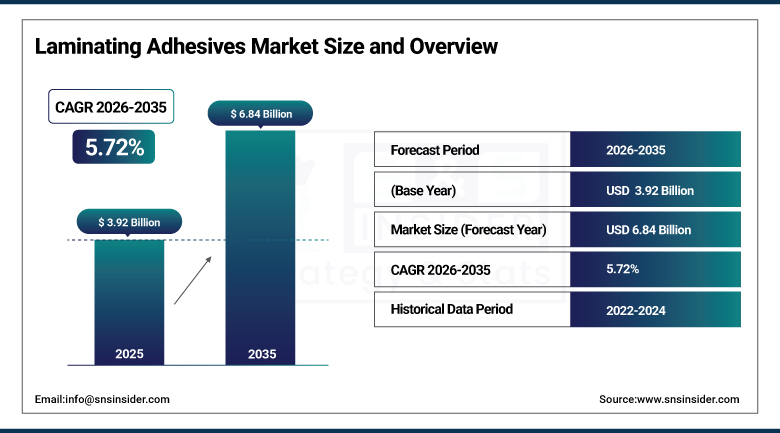
The Laminating Adhesives Market was valued at USD 3.92 Billion in 2025 and is estimated at USD 4.14 Billion in 2026. The market is forecast to reach USD 6.84 Billion by 2035, registering a CAGR of 5.72% from 2026 to 2035. Growth reflects rising use of multilayer flexible packaging for food, beverages, and pharmaceuticals, a steady shift toward solvent-free and recyclable lamination systems, and expanding output of automotive and industrial laminates. The scope covers polyurethane, acrylic, and other adhesives that bond films, foils, paper, and other substrates into laminated structures, sold as solvent-based, water-based, solventless, and other systems.
To Get more information Laminating Adhesives Market - Request Free Sample Report
Key Market Trends & Insights
-
By resin: Polyurethane held the largest market share of 49.18% in 2025.
-
By technology: Solvent-based held the largest market share of 43.26% in 2025.
-
By application: Packaging held the largest market share of 63.54% in 2025.
-
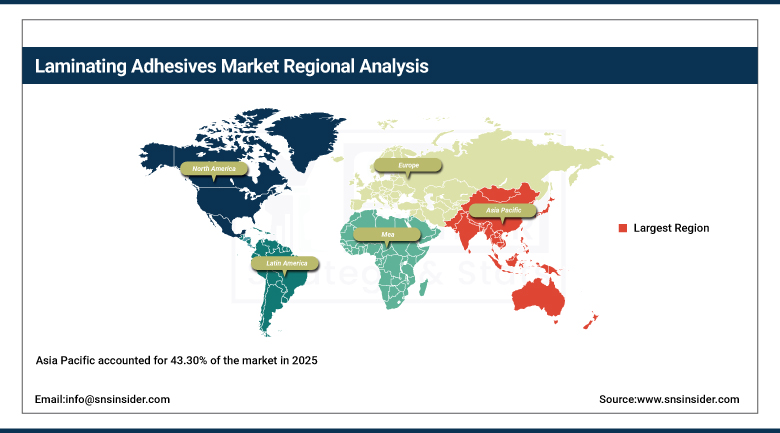
Asia Pacific accounted for the largest regional share of 43.30% in 2025.
-
Asia Pacific is projected to register the fastest regional CAGR of 6.74% from 2026 to 2035.
-
The U.S. is the leading country market, supported by a large flexible packaging industry, strict food contact rules, and demand from pharmaceutical and industrial converters.
Growth Outlook
Packaging law in Europe is reshaping how converters design laminated structures. In August 2026, the European Commission began applying the Packaging and Packaging Waste Regulation, which requires all packaging placed on the EU market to be recyclable and sets performance grades that tighten from 2030. Brand owners are moving from mixed-material pouches toward mono-material films, and each redesign needs adhesives that bond reliably without blocking recycling. Suppliers with qualified solventless and low-migration systems gain specification wins as these programs move from pilot to commercial volume.
Demand for flexible packaging in the United States continues to expand at a steady pace. In April 2026, the Flexible Packaging Association reported that U.S. flexible packaging sales reached USD 42.60 Billion in 2024, an increase of 2.90% from the previous year. Pouches, lidding films, and wraps depend on laminates that combine barrier, sealing, and print layers, and every layer requires an adhesive. Growth in snacks, ready meals, pet food, and medical packaging therefore translates directly into higher consumption of lamination adhesives across the region.
Market Dynamics
Driver: Flexible Packaging Growth and the Shift to Solvent-Free Systems Support Demand
Plastics continue to be the most common material for flexible packaging, with continuous growth in the volume of production. According to Plastics Europe in October 2025, the world production of plastics was 430.90 million tonnes in 2024, and the major end use is in packaging. The lamination of films aids in protecting the food products and medicines from environmental factors like moisture, oxygen, and light, thus increasing the shelf life and minimizing the wastage. Urbanization, internet grocery shopping, and single serve packs have increased the packs per customer, and each multilayered pack requires a layer of adhesive.
Adhesives are converting solvent-based coating lines to solvent-free lines, reducing energy and emissions. In September 2025, the circular economy program for flexible packaging, known as CEFLEX, revised its design guide and set an adhesive and coatings limitation of no more than 5.00% of the pack weight, pushing formulators towards thinner coat weights and suitable chemistries. Solvent-free coating systems require less energy for drying and have higher speeds on modern laminators, thus increasing productivity while meeting the customer's requirements for recycled content and reduced carbon footprint. Machine manufacturers today offer laminators suitable for solvent-free adhesives, thus reducing the payback period for converters who invest in such equipment.
Restraint: Raw Material Volatility and Chemical Regulation Raise Cost and Complexity
The prices of polyurethane adhesives are linked to isocyanates and polyols, which are derived from petrochemical feedstock, hence being affected by energy and crude oil prices. In March 2026, the U.S. Environmental Protection Agency made final amendments to the emission standards for the production of polyether polyol, affecting 23 manufacturing plants, and existing plants have three years to comply. Compliance costs incurred at the upstream plants may be passed to the customers of adhesives through increased prices of resins, but formulators may not be able to do so to converters who work on narrow margins and with long-term contracts.
In 2023, the European Union started making it compulsory to have documentation for the training of industrial and professional use of products having diisocyanates concentration greater than 0.10%. The training will be provided at an interval of not less than five years. The small converters will have to dedicate their resources for training and documentation while the suppliers will have to alter their product designs to reduce monomer concentrations. Food contact approval requirements are different in different regions and hence delay the time taken by a single adhesive to enter multiple markets.
Opportunity: Recyclable Laminates, Food Contact Compliance, and Specialty Applications Open New Revenue
Safe chemistry will soon become an important sales argument. In January 2025, the U.S. Food and Drug Administration declared that 35 food contact notifications for PFAS-based grease-proofing coatings are no longer valid, which means stricter controls on substances contacting food. Adhesive suppliers that provide low-migration, bisphenol-free, and PFAS-free grades will find customers among brand owners that audit their supply chains. Documentation, test support, and quick regulatory updates are highly appreciated by converters supplying into multiple countries. Retort pouches for food and sterilized medical goods are emerging and require high temperature resistance. Sterile barrier systems used in medical devices also require reliable bonding.
The second growth driver will be recyclable laminates. In June 2025, the revised positive list for synthetic resin food contact materials will take effect in Japan. It defines which substances may come into contact with food and encourages using the listed materials. Mono-polyethylene and mono-polypropylene pouches require adhesives that do not interfere with sorting and washing, while compostable films require adhesives compatible with their end-of-life process. Specialty uses in batteries, photovoltaic modules, and electronics add higher-value applications. Suppliers that develop adhesives for recycled films can also help converters reach customer recycled content targets. Growth in flexible electronics and lithium-ion battery pouches adds further need for engineered laminating systems.
Market Characteristics & Concentration
The Laminating Adhesives Market is Moderately Consolidated. A handful of global adhesive groups supply large converters under multiyear contracts, while regional formulators serve local printers and laminators with tailored products. Technical service, speed of qualification, and the ability to support customers with food contact documentation weigh heavily in supplier choice, and price competition is strongest in commodity solvent-based grades. Customers often qualify two suppliers for each laminate to protect continuity of supply.
Portfolio moves have been frequent in recent years. Large groups have bought and sold flexible packaging adhesive units to concentrate on areas where they have scale in resin chemistry and application knowledge. Raw material suppliers have also integrated forward, and ink and coating producers have added adhesives to offer converters a single point of supply for printing, coating, and bonding. Smaller regional formulators remain attractive acquisition targets for groups that want local technical teams.
Regulation shapes product design. In April 2026, FEICA, the European adhesives association, informed members that packaging adhesive obligations under the new packaging rules would require supplier information for conformity files, with recyclability assessed for the whole pack. Suppliers that can provide full composition data, migration studies, and recycling test results hold an advantage over competitors that lack documentation. Regional rules on food contact materials also differ, which favors suppliers with regulatory teams in several markets.
Analyst Perspective
Laminating adhesives are a small but essential part of the packaging value chain, and their growth follows the shift to flexible formats and the redesign of packs for recycling. Polyurethane systems will remain the workhorse for demanding structures, while solventless technology gains share as converters seek lower energy use and cleaner operations. Raw material prices and chemical regulation will keep margins under pressure, so suppliers with strong technical service will be best placed. An SNS Insider Analyst, Santosh Bhul, commented, "Suppliers that pair solvent-free chemistry with proven food contact compliance and recycle-ready bonding performance will outgrow the market, and Asia Pacific will add the largest volumes through 2035."
Segment Analysis
Resin Insights
Polyurethane held the largest share of 49.18% in 2025. Two-component polyurethane adhesives deliver high bond strength, heat resistance, and resistance to boiling and retort conditions, which suits pouches for ready meals, sauces, and pet food. They bond a wide range of films and foils, and converters have long experience with their handling and curing. Product ranges now include aliphatic and ultra-low-monomer grades that meet strict food safety limits, which supports their continued leadership in demanding structures. Converters also value stable supply from established suppliers. Their performance record lowers the risk for converters that run high-value pouches.
Acrylic adhesives are projected to grow at the fastest CAGR of 7.42% from 2026 to 2035. Water-based and solvent-based acrylics offer good clarity, easy application, and lower odor, and they are widely used in paper-to-film and film-to-film laminates for dry food, labels, and general packaging. They avoid isocyanate handling rules and are simpler to run in plants with limited ventilation. Newer grades with improved heat and moisture resistance are widening their use in medium-performance structures. Lower cost per kilogram helps them compete in price-sensitive packaging categories. Suppliers also offer water-based acrylics for paper laminates.
Technology Insights
Solvent-based systems held the largest share of 43.26% in 2025. They are familiar to converters, deliver consistent bond quality across many substrates, and run on installed laminators with drying tunnels and solvent recovery. Their lower cost per kilogram and wide formulation range support use in mid-performance and high-performance structures. Environmental rules and energy costs push users toward alternatives, but the large base of installed lines keeps solvent-based adhesives dominant in many regions. Solvent recovery units limit emissions at many plants. Suppliers also provide technical support for line optimization and cleaning.
Solventless technology is expected to expand at the fastest CAGR of 7.18% from 2026 to 2035. These adhesives are applied without solvent carriers, which removes drying ovens, cuts energy use, and eliminates solvent emissions and residual solvent in packs. Modern solventless laminators run at high speed, and suppliers have developed grades that reach safe migration levels within short times. Large converters adopt them to meet customer sustainability targets and to reduce operating costs per square meter of laminate. Lower inventory of solvents also reduces fire risk and storage cost at converting plants.
Application Insights
Packaging held the largest share of 63.54% in 2025. Food and beverage pouches, lidding films, snack wraps, and pharmaceutical blister and sachet structures all rely on laminated films that combine print, barrier, and sealing layers. Brand owners demand stronger barriers with less material, and retort, hot-fill, and microwave packs call for adhesives with high heat resistance. Pack variety and shorter product cycles lead to frequent qualification of new adhesive and film combinations, which sustains demand. Contract converters serving several brands often run many small jobs, which favors adhesives with stable performance.
Pharmaceutical and medical packaging is projected to grow at the fastest CAGR of 6.92% from 2026 to 2035 among the major applications. Blister lidding, sachets, and sterile barrier pouches require adhesives with low extractables, strong seals, and full documentation. Aging populations, rising prescription volumes, and growth in single-dose formats increase output of laminated packs. Automotive, construction, and electronics laminates add further demand where durability and temperature resistance are needed. Regulators and quality auditors also expect traceability for every batch of adhesive used. Sterilization compatibility is another requirement for many pharmaceutical structures.
Regional Insights
North America accounted for 25.30% of the global market in 2025. The region has a mature flexible packaging industry, large food and pharmaceutical producers, and a base of converters that invest in solventless lines. In May 2026, California approved regulations under its packaging responsibility law that set a goal of 65.00% recycling of single-use packaging by 2032, which pushes brand owners toward recyclable laminates. Canada adds demand through food processing and specialty film production. Food exporters also drive demand for durable packs.
Get Customized Report as per Your Business Requirement - Enquiry Now
U.S. Laminating Adhesives Market
The U.S. market was valued at USD 833.08 Million in 2025 and is expected to register a CAGR of 5.58% from 2026 to 2035. Food contact rules set by federal regulators, including limits on adhesive components in food packaging, make documentation and low-migration chemistry central to supplier selection. Large converters operate multiple plants serving snacks, frozen foods, and pet food, and they are adding solventless laminators to cut energy use and meet customer sustainability goals. Equipment makers and adhesive suppliers cooperate closely on line trials.
Recycling goals from retailers and consumer goods companies fuel the need for mono-material pouches and suitable adhesive tapes. Medical device and pharmaceutical packaging provide additional stable requirements along with well-defined quality management systems. High value specialty applications like battery foils, solar module backings, and automotive interior film provide additional volume. Technical services, on-site services, and fast deliveries to factories nationwide make up the competition among the suppliers. The pharma facilities need validated suppliers with reliable batch-to-batch consistency. Supplier training for converters is provided by the suppliers.
Europe Laminating Adhesives Market
Europe accounted for 23.40% of the global market in 2025, with Germany, Italy, France, and the United Kingdom as the largest country markets. In April 2026, the United Kingdom tax authority HM Revenue and Customs raised the plastic packaging tax rate for packaging with less than 30.00% recycled content, which increases interest in recycled films and lighter laminates. Strict food contact rules and the new EU packaging regulation make Europe a lead market for solventless and recycle-ready systems.
Asia Pacific Laminating Adhesives Market
Asia Pacific accounted for 43.30% of the market in 2025 and is anticipated to register the fastest regional CAGR of 6.74% from 2026 to 2035. In March 2025, China issued an amendment to its national standard for additives used in food contact materials, which tightens control over adhesive ingredients. China, India, Japan, South Korea, and Southeast Asia have large packaging industries supported by rising incomes, processed food, and e-commerce, and local formulators expand capacity to serve both domestic and export demand.
Latin America Laminating Adhesives Market
Latin America represented 4.70% share of the market in 2025, with Brazil being the top market followed by Mexico and Argentina. Flexible laminates require food and beverage packaging, personal care and agri-export products. Brazil is working on recycling policies and recovery content regulations for plastics packaging; thus, they will affect adhesive selection over time, and Mexico is aided by packaging facilities for export and local brands. Laminator machines are installed slowly by converters in the region.
Middle East & Africa Laminating Adhesives Market
Middle East & Africa accounted for 3.30% of the market in 2025, with Saudi Arabia, the United Arab Emirates, Turkey, South Africa, and Egypt as the main country markets. Growth in food processing, bottled beverages, and consumer goods supports flexible packaging output, and Gulf countries invest in packaging film plants linked to local petrochemical supply. Africa has rising demand for affordable packaged food, although imports of adhesives and films remain high. New plants in free zones attract regional food producers.
Key Laminating Adhesives Market Company Insights
Companies in the laminating adhesives market are focusing on solvent-free and low-migration products, recycle-ready bonding for mono-material laminates, technical service close to converters, and portfolio reshaping through acquisitions. Raw material suppliers, ink makers, and coating producers are also entering adjacent categories to serve converters from a single source. Partnerships with film makers and machine builders remain central to product qualification.
Key Laminating Adhesives Companies:
-
Henkel
-
H.B. Fuller
-
Arkema
-
Sun Chemical
-
Toyo Ink
-
COIM
-
Mitsui Chemicals
-
Sika
-
Uflex
-
Pidilite
-
Morchem
Recent Developments
-
In October 2026, Sika agreed to acquire the adhesives business of Resonac, adding capacity in Japan, China, and Taiwan, mainly for automotive applications.
-
In October 2026, Henkel completed the acquisition of Stahl Group, a supplier of coatings and treatments for flexible materials.
-
In September 2026, Pidilite announced a partnership with Hwaseung Chemical to bring advanced footwear adhesive technology to India.
-
In July 2026, Arkema reported higher second-quarter earnings, with its adhesive solutions business as one of the main contributors to growth.
-
In June 2026, H.B. Fuller announced a recommended cash offer for Advanced Medical Solutions Group, which expands its presence in medical adhesives.
-
In April 2026, Toyo Ink announced price increases of more than 20.00% on laminating adhesives, gravure inks, and flexographic inks, citing supply disruption of solvents and resins.
-
In January 2026, Sun Chemical introduced SunLam QA-8000, a solvent-free ultra-low-monomer laminating adhesive for demanding flexible packaging.
Scope and Research Methodology
This report defines the laminating adhesives market as the revenue generated from adhesives sold to bond films, foils, paper, and other substrates into laminated structures. Coverage includes polyurethane, acrylic, and other resin types, supplied as solvent-based, water-based, solventless, and other technologies, and used in packaging, automotive and transportation, industrial, and other applications. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are stated in USD. Pressure-sensitive label adhesives, construction sealants, and non-lamination bonding are outside the scope. Adhesives used only for converting inputs outside lamination, such as film extrusion tie layers, are also excluded.
The research program combines secondary and primary work. Secondary research draws on company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with executives, product and business heads, converters, procurement managers, and other stakeholders across the value chain. These conversations validate assumptions, adoption rates, and pricing, and they test the direction of demand in each region and application before any figure is finalized for the study. Interviews cover both adhesive supplier and converter perspectives, which helps to test pricing, qualification cycles, and technology adoption across regions.
Market engineering follows a bottom-up build from adhesive consumption by laminate type, converter capacity, and supplier revenue, cross-checked top-down against flexible packaging output and end-use industry indicators. Estimates are triangulated across these routes until the results converge within an acceptable range. Forecasts incorporate the drivers that shape demand, including regulation, technology maturity, and macroeconomic conditions. Senior analysts review every estimate, assumption, and narrative section for consistency before release, and figures are checked against the segment and regional totals so that the final model remains internally coherent. Updates follow major company announcements and regulatory changes.
Laminating Adhesives Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.92 Billion |
| Market Size by 2035 | USD 6.84 Billion |
| CAGR | CAGR of 5.72% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Resin (Polyurethane, Acrylic, and Others) • By Technology (Solvent-Based, Water-Based, Solventless, and Others) • By Application (Packaging, Automotive and Transportation, Industrial, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Henkel, H.B. Fuller, Arkema, Sun Chemical, Toyo Ink, COIM, Mitsui Chemicals, Sika, Uflex, Pidilite, Morchem |

Frequently Asked Questions
The market was valued at USD 3.92 Billion in 2025 and is projected to reach USD 6.84 Billion by 2035.
The market is expected to register a CAGR of 5.72% from 2026 to 2035.
Asia Pacific led the market with a 43.30% share in 2025.
Asia Pacific is expected to grow the fastest, at a CAGR of 6.74% from 2026 to 2035.
Polyurethane led the resin segment with a 49.18% share in 2025, and packaging led the application segment.
Key players include Henkel, H.B. Fuller, Arkema, Sun Chemical, and Toyo Ink.
