
Fresh Food Packaging Market Report Scope & Overview:
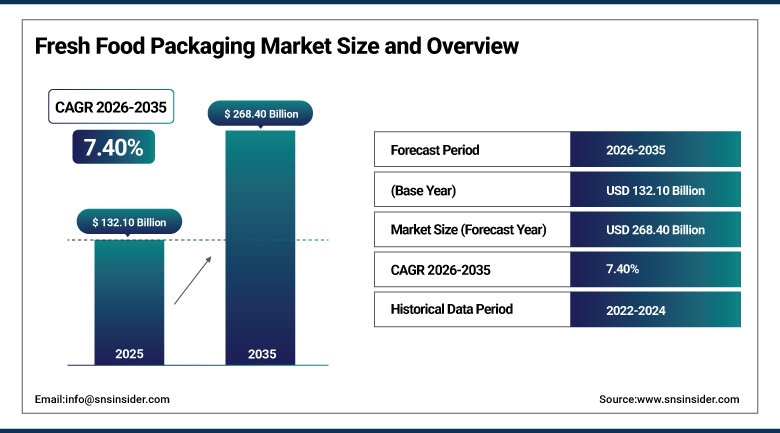
The Fresh Food Packaging Market was valued at USD 132.10 Billion in 2025 and is expected to reach USD 268.40 Billion by 2035, growing at a CAGR of 7.40% from 2026 to 2035.
Fresh food packaging carries a harder brief than most other packaging categories, it has to keep a genuinely perishable product looking appealing and staying safe for days or weeks, without the shelf-stable chemistry that canned or frozen goods can rely on. Vacuum skin packaging and modified atmosphere packaging have become the two workhorse technologies for meeting that brief, tightly controlling the oxygen and moisture environment around meat, seafood, and produce in ways that meaningfully extend shelf life without additives. Rising consumer demand for food safety and quality, combined with growing e-commerce grocery delivery that puts fresh products through a longer, less controlled journey than a simple retail shelf trip, continues pushing packaging suppliers toward more sophisticated barrier and monitoring technology.
In 2025, Pactiv Evergreen Inc. became part of Novolex Holdings, LLC, combining fresh food and beverage packaging manufacturing capabilities across North America.
To Get more information Fresh Food Packaging Market - Request Free Sample Report
Fresh Food Packaging Market Trends
-
Vacuum skin packaging continues expanding across meat and seafood categories for its shelf-life and presentation advantages.
-
Paper and paperboard trays are gaining share as brands respond to plastic-reduction regulation without sacrificing barrier performance.
-
E-commerce grocery delivery is driving demand for packaging engineered specifically for multi-hour, less-controlled shipping journeys.
-
Smart labels tracking cold-chain temperature history are expanding across premium fresh meat and seafood categories.
-
Flexible packaging formats are gaining ground as brands look to reduce material use and freezer or fridge case footprint.
U.S. Fresh Food Packaging Market Outlook
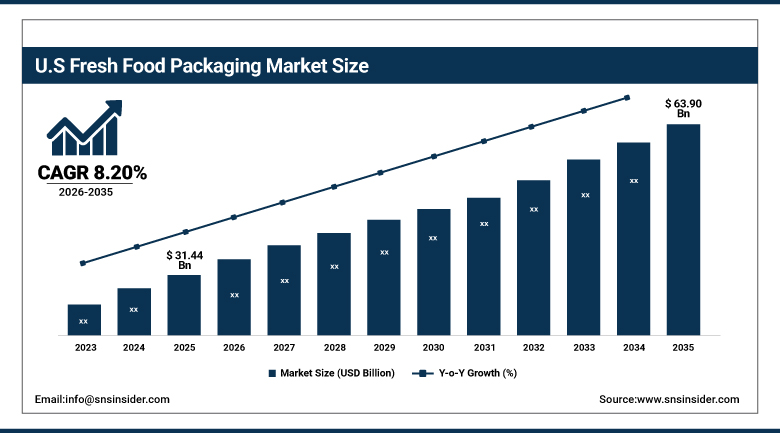
The U.S. Fresh Food Packaging Market was valued at USD 31.44 Billion in 2025 and is projected to reach USD 63.90 Billion by 2035, growing at a CAGR of 8.20% during 2026-2035.
Grocery retailers have steadily expanded fresh food department footprint over the past several years, and that shelf-space growth is pulling packaging demand along with it as brands compete for visibility across meat, produce, and prepared food sections. Rising demand for convenience and on-the-go consumption continues favoring ready-to-eat and portion-controlled fresh formats, categories where packaging has to do more work supporting both shelf presentation and immediate consumption than traditional bulk fresh formats require. Meal-kit and grocery-delivery services have added a distinct demand line too, requiring packaging engineered specifically for multi-hour transit rather than short retail-to-home trips. State-level plastic-reduction regulation is pushing fresh food brands toward recyclable paperboard and mono-material film options faster than they might have moved otherwise.
In August 2024, Pactiv Evergreen Inc. launched Recycleware Reduced-Density Polypropylene meat trays, recognized by the Association of Plastic Recyclers as meeting its highest design guidance criteria for recyclability.
Fresh Food Packaging Market Segment Analysis
-
By Material Type, Plastic segment dominated the Fresh Food Packaging Market in 2025 with 40.00% share; Paper & Paperboard segment is the fastest-growing segment, registering a CAGR of 9.20% from 2026 to 2035.
-
By Packaging Format, Rigid Packaging segment dominated the market in 2025 with 46.00% share; Flexible Packaging segment is the fastest-growing segment, registering a CAGR of 8.60% from 2026 to 2035.
-
By Application, Fruits & Vegetables segment dominated the market in 2025 with 28% share; Ready-to-Eat Foods segment is the fastest-growing segment, registering a CAGR of 9.80% from 2026 to 2035.
-
By Technology, Vacuum Skin Packaging segment dominated the market in 2025 with 35.00% share; Modified Atmosphere Packaging segment is the fastest-growing segment, registering a CAGR of 8.80% from 2026 to 2035.
By Material Type, Plastic Leads the Fresh Food Packaging Market While Paper & Paperboard Gains Ground Fastest
Plastic holds 40.00% of the Fresh Food Packaging Market, remaining the default choice largely because it maintains the moisture and oxygen barrier that fresh food requires without cracking or becoming brittle across the wide temperature range products move through between processing, distribution, and retail storage. Compatibility with advanced packaging systems like vacuum skin and modified atmosphere technology also keeps plastic the most versatile material for fresh food's demanding barrier requirements.
Paper & Paperboard is growing at a 9.20% CAGR, the fastest pace among materials, as brands respond to plastic-reduction regulation and consumer demand for curbside-recyclable packaging by adopting freezer and moisture-grade coated fiber alternatives that would have struggled to meet fresh food's barrier requirements a decade ago. Continued improvement in coating technology is helping paperboard close the performance gap with plastic across an expanding range of fresh food categories.
By Packaging Format, Rigid Packaging Dominates While Flexible Packaging Registers the Fastest Growth
Rigid Packaging holds 46.00% of the market by format, the largest single category, valued for the durable protection it offers dairy, meat, poultry, and other high-impact perishable goods that need to withstand distribution handling without deforming or compromising their barrier seal. Established rigid tray and container manufacturing infrastructure across the industry keeps this format the default choice for products where structural protection matters as much as barrier performance.
Flexible Packaging is growing fastest, at an 8.60% CAGR, as brands increasingly favor lighter, more material-efficient formats that reduce shipping weight and take up less retail case space per unit of product than rigid alternatives require. Growing e-commerce grocery delivery has reinforced this shift, since flexible formats generally ship more efficiently and generate less packaging waste per delivery than bulkier rigid containers.
By Application, Fruits & Vegetables Dominates While Ready-to-Eat Foods Registers the Fastest Growth
Fruits & Vegetables accounts for 28% of application demand, the largest single category, reflecting the sheer volume of fresh produce moving through global retail and the genuine complexity of packaging a living, respiring product that continues ripening and losing moisture after harvest. Transparent packaging that lets consumers visually assess freshness at the shelf continues playing an outsized role in purchase decisions for this category specifically.
Ready-to-Eat Foods is the fastest-growing application, expanding at a 9.80% CAGR, as busy households and rising grocery delivery adoption drive demand for convenient, heat-and-eat or grab-and-go fresh meal options. Packaging for this category has to support both freezer or fridge storage and often direct microwave or oven heating in the same format, which is pushing continued innovation in dual-ovenable, compartmentalized tray designs.
By Technology, Vacuum Skin Packaging Dominates While Modified Atmosphere Packaging Registers the Fastest Growth
Vacuum Skin Packaging holds 35.00% of the market by technology, the largest single category, valued for the tight, form-fitting seal it creates directly against the product's surface, which both extends shelf life and gives meat and seafood products a premium, glossy shelf presentation that loose overwrap formats can't match. This dual benefit, functional and aesthetic, has made vacuum skin packaging the preferred technology across premium fresh protein categories in particular.
Modified Atmosphere Packaging is growing fastest, at an 8.80% CAGR, as its broad applicability across produce, bakery, and ready-to-eat categories, not just meat and seafood, gives it a wider addressable application base than more specialized technologies like vacuum skin packaging. Continued advances in gas mixture optimization for specific product types are reinforcing this technology's expanding role across an increasingly diverse range of fresh food applications.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
85.40% |
|
Asia Pacific |
China |
36.20% |
|
Europe |
Germany |
25.60% |
|
Middle East & Africa |
UAE |
17.20% |
|
Latin America |
Brazil |
26.80% |
North America Fresh Food Packaging Market Insights
North America is growing faster than any other region in this market, driven by rising demand for convenience, expanding adoption of eco-friendly packaging solutions, and healthy eating habits that continue pushing more fresh, minimally processed food through the region's retail system. Even though the region trails Asia Pacific in overall market size, growth here reflects genuine format and material innovation rather than simple volume expansion.
The United States accounts for approximately 85.40% of the North American market, reflecting its large fresh food retail and distribution infrastructure. Canada contributes a smaller but steady share, tied to its own packaging waste regulations and comparably mature fresh food retail sector.
Asia Pacific Fresh Food Packaging Market Insights
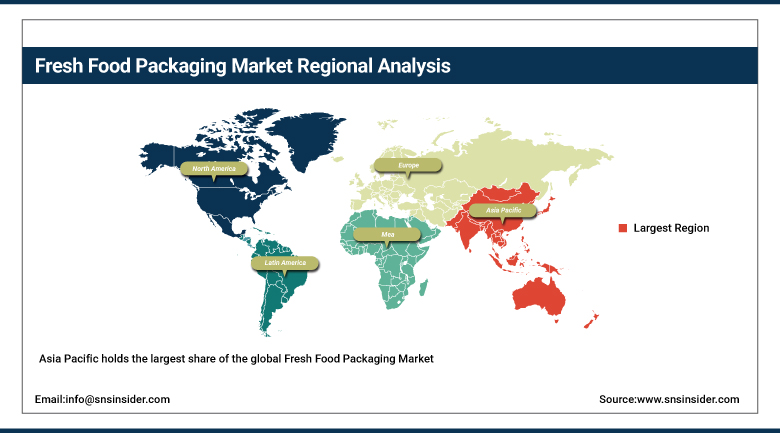
Asia Pacific holds the largest share of the global Fresh Food Packaging Market, driven by expanding organized retail infrastructure, rapid urbanization, and rising middle-class demand for packaged fresh food across the region's large population base. Modern retail formats replacing traditional wet markets in Chinese and Southeast Asian cities continue expanding demand for the kind of branded, packaged fresh food that organized grocery retail depends on.
China holds roughly 36.20% of the regional market, supported by its expanding fresh food manufacturing base and rapidly growing organized retail sector. India is growing quickly as cold-chain logistics investment expands and modern retail penetration increases, while Japan and South Korea contribute through their mature, well-established fresh food retail sectors.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Fresh Food Packaging Market Insights
Europe's fresh food packaging market is mature and steady, shaped by strong sustainability mandates and widespread packaged produce usage across the region's large consumer base for fresh food. European retailers have invested heavily in plastic replacement materials, driving large-scale adoption of cellulose-based films and fiber packaging ahead of most other regions.
Germany leads the European market with a 25.60% share, supported by its large fresh food retail sector and strict sustainability compliance standards. France and the United Kingdom follow, with demand in both countries tied to established fresh food retail infrastructure and growing recyclable packaging adoption.
Middle East & Africa and Latin America Fresh Food Packaging Market Insights
The Middle East & Africa region is growing steadily as cold-chain retail infrastructure expands across the Gulf states, supported by rising fresh food import volumes and growing modern grocery penetration. Latin America's growth follows a similar arc, driven by expanding fresh food manufacturing capacity in Brazil and growing urban demand for packaged fresh and ready-to-eat products.
The UAE leads the Middle East & Africa market with a 17.20% share, supported by its role as a regional fresh food distribution hub. Brazil represents 26.80% of the Latin American market, reflecting its large fresh food manufacturing base, with Mexico also contributing through its expanding organized retail footprint.
Market Dynamics
Growth Drivers: Convenience Demand and Food Safety Standards Fueling Market Growth
Rising consumer demand for food safety and quality is the clearest driver behind this market's growth, as regulatory standards and consumer expectations both push packaging suppliers toward more sophisticated barrier and monitoring technology than older fresh food packaging formats provided. Growing preference for convenience and on-the-go consumption is reinforcing this demand, as ready-to-eat and portion-controlled fresh formats require packaging engineered to support both freshness and immediate consumption in a single format.
Expanding e-commerce grocery delivery is adding a meaningful additional demand line, as fresh products increasingly need to survive a longer, less controlled shipping journey than a traditional retail shelf trip ever required.
Restraints: Material Cost Volatility and Barrier Performance Trade-offs Limiting Market Expansion
Resin and paperboard costs have both been volatile in recent years, making it difficult for packaging suppliers to hold pricing steady with fresh food brands operating on already thin margins. Freezer and refrigeration-grade performance requirements also limit how quickly brands can switch to newer sustainable materials, since a paperboard or mono-material substitute that fails to prevent moisture loss or contamination is not a viable substitute regardless of its sustainability credentials.
A meaningful share of fresh food packaging, particularly multilayer barrier structures, still is not accepted in most curbside recycling programs, which puts brands under growing pressure as extended producer responsibility fees increasingly get tied to recyclability performance.
Opportunities: Smart Packaging and Recyclable Barrier Innovation Creating New Growth Avenues
Smart, temperature-tracking packaging represents a genuine growth opportunity, particularly for premium fresh meat and seafood categories where buyers are willing to pay for verified cold-chain integrity throughout distribution. Manufacturers who can integrate reliable monitoring technology into standard packaging formats stand to capture meaningful share in this expanding premium application.
Recyclable barrier coating innovation offers a second clear opportunity, particularly as brands seek formats that can move away from multilayer plastic structures without sacrificing the freezer and refrigeration performance fresh food packaging absolutely requires.
Recent Developments:
-
January 2025: Pactiv Evergreen Inc. launched a new line of molded fiber packaging products, made from wood pulp and recycled paper, designed as a compostable and recyclable alternative to traditional plastic fresh food trays and containers.
-
2025: Amcor plc launched a recycle-ready frozen and fresh food packaging format in Latin America featuring a 38% reduced carbon footprint compared with prior multilayer structures.
-
2025: Sonoco Products Company introduced a recyclable paperboard tray system for fresh and frozen retail packs, designed to replace multilayer plastic trays across major U.S. grocery chains.
-
2025: Huhtamaki Oyj launched compostable and recyclable packaging made from certified paperboard with a bio-based coating, keeping plastic content below 10%, for fresh and frozen food applications.
Fresh Food Packaging Market key players are:
-
Amcor plc
-
Graphic Packaging International, LLC
-
Sealed Air Corporation
-
Smurfit Westrock plc
-
Anchor Packaging LLC
-
Ball Corporation
-
Coveris Holdings S.A.
-
Interflex Group, Inc.
-
International Paper Company
-
LINPAC Packaging Limited
-
Pactiv Evergreen Inc.
-
Reynolds Consumer Products Inc.
-
Sonoco Products Company
-
Mondi Group
-
Huhtamaki Oyj
-
Tetra Pak International S.A.
-
Constantia Flexibles Group GmbH
-
Bemis Manufacturing Company
-
Genpak LLC
-
Placon Corporation
Fresh Food Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 132.10 Billion |
| Market Size by 2035 | USD 268.40 Billion |
| CAGR | CAGR of 7.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material Type (Plastic, Paper & Paperboard, Metal, Others) • By Packaging Format (Rigid Packaging, Flexible Packaging) • By Application (Fruits & Vegetables, Meat & Poultry, Seafood, Dairy Products, Bakery & Confectionery, Ready-to-Eat Foods) • By Technology (Vacuum Skin Packaging, Modified Atmosphere Packaging, Aseptic Packaging, Retort Processing) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amcor plc, Graphic Packaging International, LLC, Sealed Air Corporation, Smurfit Westrock plc, Anchor Packaging LLC, Ball Corporation, Coveris Holdings S.A., Interflex Group, Inc., International Paper Company, LINPAC Packaging Limited, Pactiv Evergreen Inc., Reynolds Consumer Products Inc., Sonoco Products Company, Mondi Group, Huhtamaki Oyj, Tetra Pak International S.A., Constantia Flexibles Group GmbH, Bemis Manufacturing Company, Genpak LLC, Placon Corporation |
Frequently Asked Questions
Key players include Amcor plc, Graphic Packaging International, LLC, Sealed Air Corporation, Smurfit Westrock plc, Anchor Packaging LLC, Ball Corporation, Pactiv Evergreen Inc., and Sonoco Products Company, alongside other established fresh food packaging manufacturers.
Key opportunities include smart temperature-tracking packaging for premium fresh meat and seafood categories, recyclable barrier coating innovation that maintains freezer and refrigeration performance, and packaging formats engineered for e-commerce grocery delivery.
The market is driven by rising consumer demand for food safety and quality, growing preference for convenience and on-the-go consumption, and expanding e-commerce grocery delivery.
The Plastic segment dominated the Fresh Food Packaging Market in 2025.
The Asia Pacific region dominated the Fresh Food Packaging Market in 2025, driven by expanding organized retail infrastructure and rapid urbanization.
