
Linear Motion Bearing Market Report Scope & Overview:
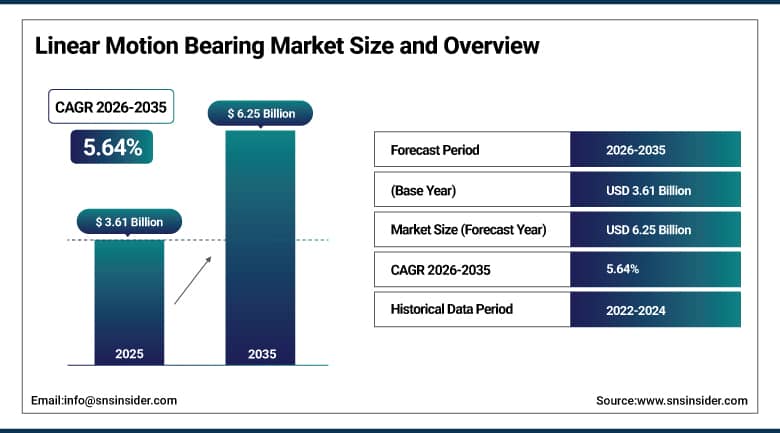
The Linear Motion Bearing Market was valued at USD 3.61 Billion in 2025 and is expected to reach USD 6.25 Billion by 2035, growing at a CAGR of 5.64% from 2026-2035.
The Linear Motion Bearing Market is growing at a consistent pace with factory automation, semiconductor equipment, medical products, and electric vehicles driving up the number of precise axes in use around the globe. Ball bearing and roller bearing types continue to be the operational heart of the market, with ceramic and plastic variants playing roles in applications such as cleanroom environments, washdown operations and corrosive environments. Machine designers call for bearings with reduced friction, longer periods between lubrications, and more precise positioning, while distributors offer interchangeable models to reduce downtime in maintenance procedures. APAC leads in production volumes while NA and EU lead in value-added precision and aftermarket sales.
⮞The International Federation of Robotics reported on 24 September 2026 that more than 600,000 new industrial robots were installed worldwide in 2025, an increase of 11%, lifting the global operational stock to about 5 million units. Every robot axis relies on linear and rotary guidance components.
To Get More Information On Linear Motion Bearing Market - Request Free Sample Report
Linear Motion Bearing Market Trends
-
Profiled rail and roller-based designs are replacing round-shaft bushings in machine tools and automation cells that need higher rigidity.
-
Ceramic hybrid and polymer bearings are gaining use in semiconductor, food and medical equipment that cannot tolerate oil or particles.
-
Pre-lubricated and maintenance-free units with long service intervals are becoming standard to reduce unplanned downtime.
-
ISO-aligned interchangeable linear guide ranges are spreading, which shortens replacement lead times for machine builders.
-
Integrated sensing and condition monitoring in bearing carriages is advancing predictive maintenance on connected production lines.
U.S. Linear Motion Bearing Market Outlook
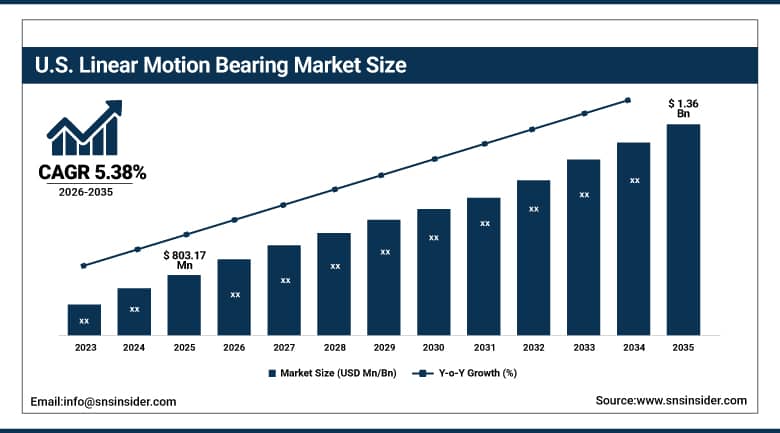
The U.S. Linear Motion Bearing Market was valued at USD 803.17 Million in 2025 and is expected to reach USD 1.36 Billion by 2035, growing at a CAGR of 5.38% from 2026-2035.
The U.S. Linear Motion Bearing Market is the largest national market in North America, supported by aerospace manufacturing, medical device production, semiconductor equipment and a broad base of machine builders. Reshoring programs and federal incentives for chip and battery plants are adding new automated lines, each requiring many precision guides. Industrial distributors and online catalog suppliers keep stocked ranges close to end users, which supports aftermarket sales. U.S. demand for replacement bearings is steady because plants run extended shifts. Machine tool builders are also moving toward higher-rigidity profile rails. Shipments of linear guides into medical and aerospace programs often require documented traceability, which favors qualified suppliers.
⮞The Association for Advancing Automation reported on 12 August 2025 that North American companies ordered 17,635 robots in the first half of 2025, up 4.3%, with automotive OEM orders rising 34%.
Linear Motion Bearing Market Segment Analysis
-
By Type, the Ball Bearings segment dominated the Linear Motion Bearing Market with approximately 43.62% share in 2025, while the Roller Bearings segment is the fastest growing with a CAGR of approximately 6.54%.
-
By Material, the Steel segment dominated the Linear Motion Bearing Market with approximately 53.84% share in 2025, while the Ceramic segment is the fastest growing with a CAGR of approximately 7.46%.
-
By Application, the Industrial Machinery segment dominated the Linear Motion Bearing Market with approximately 36.18% share in 2025, while the Medical Devices segment is the fastest growing with a CAGR of approximately 7.83%.
-
By End-User, the OEMs segment dominated the Linear Motion Bearing Market with approximately 69.74% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 6.47%.
By Type, Ball Bearings Dominates the Linear Motion Bearing Market and Roller Bearings Grows Fastest
Ball bearings lead the type landscape because recirculating ball bushings and profile rail carriages deliver low friction, smooth travel and wide size availability at accessible prices. Packaging lines, 3D printers, pick-and-place units and general automation rely on them, and designers can select from many interchangeable catalog sizes. Ball formats also tolerate moderate misalignment, which eases installation in less rigid frames. Their long production history gives buyers confidence in life calculations and replacement planning. Distributors report that catalog ball bushings and compact carriages move quickly because designers can substitute equivalent sizes across brands without redesigning the mounting frame.
Roller bearings are advancing faster as machine tools, semiconductor equipment and heavy handling systems demand higher stiffness and load capacity within compact envelopes. Line contact between rollers and raceways reduces elastic deflection, improving cutting accuracy and positioning repeatability. Suppliers have introduced roller guide ranges with longer life in contaminated environments. Needle and plain bearings continue to serve compact, low-speed or washdown applications, but the growth emphasis is shifting toward roller designs. Competition between Japanese, Taiwanese, German and Chinese producers keeps the roller category innovative, with ranges now covering cross roller, needle roller and profile roller formats.
⮞HepcoMotion announced on 19 June 2025 that it would open three new sites near its Tiverton headquarters, including manufacturing and assembly space for its GFX linear guidance range, expanding its footprint by 25% to 30%.
By Material, Steel Dominates the Linear Motion Bearing Market and Ceramic Grows Fastest
Steel continues to be the industry standard since bearing-grade chrome and stainless steels provide a good combination of hardness, fatigue resistance, and favorable cost. Hardened steel raceways and balls can withstand heavy loads in machinery, packaging equipment, and automobiles and benefit from heat treatment to improve service life. The stainless steel variety is designed to accommodate the food and pharmaceutical industries that need corrosion resistance. An established supply chain of manufactured rolled, ground, and polished steel parts ensures stable prices and availability. The food and pharmaceutical processing and packaging machines require corrosion-resistant steel carriages with food-grade lubrication, thus maintaining high prices in steel family.
Ceramic and hybrid bearings are growing fastest because silicon nitride balls run cooler, resist corrosion, tolerate vacuum and avoid magnetic interference. Semiconductor, medical imaging and laboratory equipment value these traits, even at a higher unit price. Plastic and composite bearings add self-lubricating, lightweight options for dust-sensitive or chemical environments, where grease is undesirable. Manufacturers are broadening polymer ranges to compete with metal units in clean and dry-running applications. Producers are also testing coated steel raceways and hybrid steel-ceramic sets, which offer a path for customers who want better performance without moving to full ceramic assemblies.
⮞In February 2025, igus introduced a PTFE-free drylin W linear guide with a snap function for precise positioning, extending its lubrication-free polymer range.
By Application, Industrial Machinery Dominates the Linear Motion Bearing Market and Medical Devices Grows Fastest
Industrial machinery remains the largest application because machine tools, packaging lines, textile equipment, printing systems and assembly cells all use linear guidance on several axes. Spending on new equipment depends on capacity utilization and capital budgets, and orders for metal cutting machines have recently recovered in the United States and Japan. Builders prefer rails that offer high rigidity and repeatable accuracy. Replacement cycles for worn carriages add recurring demand across installed fleets. Textile and printing equipment, although mature, still generate steady demand for round-shaft bearings and rails that are replaced as machines are modernized or relocated.
Medical devices are the fastest-growing application as imaging systems, surgical robots, diagnostic analyzers and lab automation platforms need quiet, smooth and contamination-free motion. Miniature rails and ceramic bearings suit compact devices with strict cleanliness rules. Automotive plants use linear bearings for welding and assembly robots, aerospace builders for composite layup and inspection systems, and electronics makers for wafer handling and placement machines, which broadens the demand base. Electronics assembly is a related growth area, because surface-mount and display manufacturing lines use compact, high-speed linear stages that call for low-noise miniature guides.
⮞The Association for Manufacturing Technology reported on 12 February 2026 that U.S. manufacturing technology orders reached USD 5.74 billion in 2025, up 22.5%, with a monthly record in December.
By End-User, OEMs Dominates the Linear Motion Bearing Market and Aftermarket Grows Fastest
Original equipment manufacturers account for most purchases because machine builders, robot makers and semiconductor tool suppliers design bearings into new equipment and buy in volume under long-term supply agreements. Early involvement in engineering lets suppliers specify preload, accuracy class and lubrication, which locks in product choice for each machine generation. Strong order books at aerospace and automation builders lift OEM demand. Cooperation on customized rail lengths and carriage designs strengthens these relationships. Large automation integrators often negotiate framework contracts that cover rail lengths, carriage types and delivery schedules for several years, giving suppliers visibility into production planning.
The aftermarket is growing faster as the global installed base of machines ages and operators emphasize uptime. Plants keep standard sizes in inventory, and distributors offer rapid shipment of interchangeable carriages and rails. Condition monitoring helps maintenance teams replace bearings before failure, which supports planned purchases. Refurbishment of rails and relubrication services form additional revenue streams for suppliers with service networks, and online ordering platforms are making replacement parts easier to source. Digital catalogs and configurators are making it easier for small machine shops to order small quantities, which is gradually blurring the line between OEM and aftermarket channels.
⮞Boeing delivered 600 aircraft in 2025, an increase of 72% and its highest total since 2018, according to figures reported in January 2026.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
46.92% |
|
North America |
United States |
84.37% |
|
Europe |
Germany |
31.58% |
|
Latin America |
Brazil |
41.73% |
|
Middle East & Africa |
Saudi Arabia |
27.64% |
Asia Pacific Linear Motion Bearing Market Insights
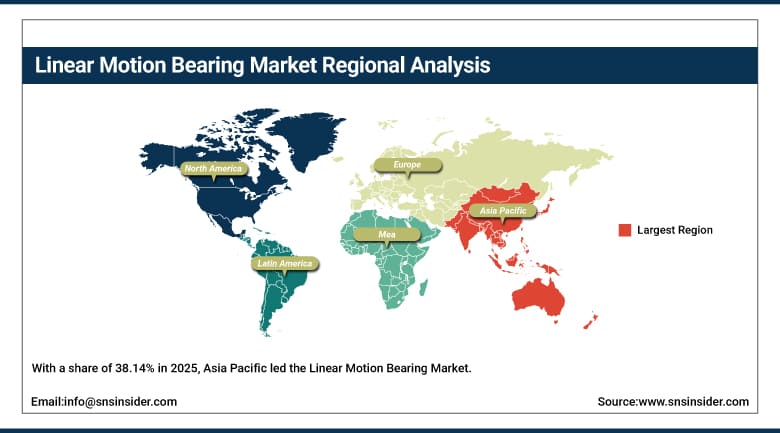
With a share of 38.14% in 2025, Asia Pacific led the Linear Motion Bearing Market, anchored by China, Japan, Taiwan, South Korea and India. The region hosts the major producers of linear guides, including THK, NSK, Hiwin and NB Corporation, and a dense base of machine tool, robot and electronics factories that consume them. Japan supplies precision grades for semiconductor tools, Taiwan exports profile rails worldwide, and China is scaling local output of mid-range guides. Taiwan combines a deep supplier cluster with export reach, and manufacturers there have been adding capacity for roller and wide-body rails to meet requests from machine tool customers abroad.
Asia Pacific is also the fastest-growing region, with a CAGR of 6.72% projected for 2026-2035. Robot installations, electric vehicle plants, battery lines and new fabs raise demand for precision motion axes, and India is building electronics and automotive capacity under production-linked incentives. Local suppliers are narrowing quality gaps and competing on lead time, while global brands localize production. Price competition remains strong, but rising precision requirements lift average selling prices in semiconductor and medical equipment. India is establishing local assembly for rails and carriages, and Southeast Asian countries such as Vietnam and Thailand are attracting electronics and automotive plants that buy imported guides.
⮞China's National Bureau of Statistics data, reported in 2026, showed industrial robot output of 773,074 units in 2025, an increase of 28%.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Linear Motion Bearing Market Insights
North America holds the second-largest share, with the United States and Canada driving demand for high-precision and aftermarket bearings. Aerospace and defense programs, medical device clusters, semiconductor investments and a recovering machine tool sector sustain orders. Machine builders favor suppliers that provide technical support, short lead times and stocked inventory through industrial distributors. Thomson Industries and Bishop-Wisecarver operate from the region, serving automation customers with linear bushings and guide systems. Medical device manufacturers in states such as Minnesota and Massachusetts buy miniature and ceramic bearings for imaging and surgical systems, while Texas and Arizona host expanding semiconductor and aerospace plants.
Reshoring and federal incentives are creating new plants for chips, batteries and pharmaceuticals, and each facility requires automated lines with many precision axes. Labor shortages encourage investment in robots and automated inspection. Canada contributes through aerospace and automotive supply chains. Buyers in the region pay attention to certification, traceability and total cost of ownership, which favors suppliers with local service. Growth is moderate, led by upgrades in existing facilities. Distributors play a particularly strong role in the region, and many offer same-day shipment, cutting and machining of rails, and application engineering that complements the manufacturers' own sales teams.
⮞Schaeffler announced in May 2025 that it would launch its KUEM miniature profile rail guide and KLLT X-arrangement profile rail guide at Automate Detroit.
Europe Linear Motion Bearing Market Insights
Europe is a major market defined by premium machine tools, packaging machinery and automation equipment built in Germany, Italy, Switzerland and the Nordic countries. Bosch Rexroth, Schaeffler, Schneeberger, HepcoMotion and Rollon design and produce linear guidance in the region and compete on accuracy, rigidity and integrated mechatronic modules. Machine builders export a large portion of their output, so European bearing demand follows global capital spending cycles. Italian and Swiss producers specialize in miniature and high-precision rails for medical and watch-making equipment, while German firms concentrate on heavy-duty guides for machine tools and presses.
Energy-efficiency regulations, Industry 4.0 initiatives, and electric cars are influencing product development in the direction of low friction, long life, and sensing carriages. Higher energy and labor costs compel companies to invest in automation. This market is one of the front-runners in cleanroom and medical devices development, and is therefore favorable for selling bearings made of ceramics and polymers. German demand was weakened by a decrease in machine tools order books, but further order normalization and military orders will help to keep this demand steady over the forecast period. Resilient supply chains and defense capability development in the EU are encouraging investments in machining equipment manufacturing.
⮞Eurostat data, reported in August 2026, showed that European Union machinery and equipment output rose 3.3% in 2025.
MEA & Latin America Linear Motion Bearing Market Insights
Latin America is a smaller market centered on Brazil and Mexico, where automotive assembly, aerospace supply chains and food processing consume linear bearings. Mexico serves as a manufacturing base for North American customers, and its machine tool and automation purchases are rising. Brazil relies on imports for precision grades and on local distributors for aftermarket supply. Currency swings and import costs affect pricing, but nearshoring investment is improving the outlook. Chile and Colombia contribute demand through mining and food processing machinery, and regional distributors supply replacement parts for imported equipment.
Middle East and Africa are growing from a small base due to establishment of industrial clusters by Gulf nations, while Saudi Arabia and United Arab Emirates are setting up automated machinery plants. In addition, South Africa is maintaining its demand for mining and automotive sectors. The majority of the bearings being used are imported and thus demand depends upon the distributors and project cycle. Gradually capabilities are building through local assembly and training initiatives. Turkey, Egypt and Morocco are building automotive and appliances sectors, thus increasing the demand for automation machinery, while exhibitions and governmental initiatives are assisting foreign suppliers in establishing local tie-ups.
⮞Saudi Arabia's Ministry of Industry and Mineral Resources reported in January 2026 that it issued 168 new industrial licenses in December 2025, and that 117 plants began production.
Market Dynamics
Growth Drivers: Automation and Semiconductor Equipment Investment Drive Growth in the Linear Motion Bearing Market
Factory automation is the largest driver because robots, gantries, packaging lines and inspection systems all use linear guidance on multiple axes. Labor shortages and quality demands push manufacturers to automate welding, assembly and handling tasks. Every added axis creates a bearing requirement, and higher duty cycles shorten replacement intervals. Electric vehicle and battery plants add a further wave of equipment. Rising wages in China, Europe and North America are accelerating adoption of collaborative robots and automated guided systems that use compact linear modules. Higher production volumes at electric vehicle and battery makers also increase the installed base of presses, coaters and stackers that depend on durable guides.
Semiconductor investment provides another driver. New fabrication plants and advanced packaging lines need ultra-precise stages, wafer handlers and inspection tools that depend on high-accuracy rails and ceramic bearings. Government incentives in the United States, Europe, Japan, South Korea and India support construction of these facilities. Equipment spending cycles translate into orders for precision motion components. Photolithography, deposition and inspection tools require stages with nanometer-level repeatability, which creates demand for high-grade crossed roller and air-supported alternatives alongside conventional rails. Equipment makers qualify bearings over long periods, so suppliers that win a design position can expect recurring orders for years.
⮞SEMI forecast in October 2025 that global 300mm fab equipment spending would reach USD 107 billion in 2025, up 7%, and rise to USD 116 billion in 2026.
Restraints: Cyclical Machine Tool Demand and Price Competition Restrain Growth in the Linear Motion Bearing Market
Demand for bearings depends on capital goods cycles and hence low orders for machinery and tools translate to low shipment levels very fast. High interest rates and low export demand cause delays in construction by project developers, who opt to utilize existing inventory instead. Uncertainty in automotive transition creates reluctance in making decisions regarding tooling. Large fixed capacities in suppliers translate to reduced utilization during economic downturns, thereby putting pressure on profits. Reduction in distributor inventories will cause such fluctuations as distributors reduce orders significantly when there is low demand. Customers in price sensitive areas may turn to local brands, making it difficult for top brands to raise prices.
Price competition from Asian producers of mid-range guides compresses margins for established brands. Counterfeit and low-quality bearings occasionally enter distribution channels, undermining trust. Steel and energy costs affect production economics, and trade tariffs complicate cross-border supply. Buyers also extend maintenance intervals through better lubrication, which can limit replacement volumes in the short term. Currency movements between the yen, euro, new Taiwan dollar and U.S. dollar change relative pricing among exporters, and shifts can reduce competitiveness without any change in product quality. Qualification cycles for new suppliers are lengthy, which protects incumbents, but also slows the adoption of innovations that could otherwise reduce cost.
⮞The German Machine Tool Builders' Association reported in March 2025 that German machine tool orders fell 19% in 2024 and production fell 4%, with a 10% production decline forecast for 2025.
Opportunities: Aerospace Production Ramp-Ups and Condition Monitoring Create Opportunities in the Linear Motion Bearing Market
Commercial aircraft manufacturing is rebounding towards unprecedented backlogs, which will drive demand for precise tooling, composite layup machines, assembly jigs, and testing machines. Aerospace manufacturers will require rails that maintain strict tolerance along longer travel distances, while qualifications lean in favor of proven brand names. Modernization efforts within the defense sector are driving demand for additional machining and inspection capabilities. Requirements from space and defense projects will bring special requirements for rails that function under extremes of temperature and vacuum, thereby allowing aerospace suppliers to market high-value engineered products. Passenger cabins in commercial aircraft include seats and galley storage units that utilize linear guidance mechanisms, translating into steady demand for lightweight systems.
Smart bearings with embedded sensors offer a second opportunity. Carriages that report vibration, temperature and load allow maintenance teams to schedule replacements, reducing downtime. Suppliers can bundle software and service contracts, creating recurring revenue. Medical robotics, laboratory automation and electric mobility also open new application areas that value compact, quiet and clean linear motion. Linear motors and integrated drive modules offer another route, since they pair guides with sensing and control to create complete axes that machine builders can install quickly. Training and digital twin tools that help designers size bearings accurately may further differentiate suppliers by shortening engineering time and reducing field failures.
⮞Airbus reported on 12 January 2026 that it delivered 793 commercial aircraft in 2025, up 4%, and ended the year with a record backlog of 8,754 aircraft.
Recent Developments:
-
2025: THK introduced the CurviLinear Wheel Guide, a guide system that combines straight and curved rails with rollers using double-row angular contact bearings. The product supports speeds up to 5 meters per second and curved segments in 75, 150 and 300 millimeter radii, addressing layouts that conventional straight rails cannot handle.
-
2025: NSK presented its DH and DS series long-life linear guides and RA series roller guides at EMO Hannover. The company states that the DH and DS guides offer more than twice the running distance of its NH and NS series, which targets machine tool builders that value longer service intervals.
-
2025: Hiwin introduced its UR heavy-duty roller guide, available in sizes 35, 45 and 55 from early 2026. The company reports up to 34% higher static and 19% higher dynamic load capacity and 70% longer life, supporting use in machine tools and heavy automation.
-
2026: Rollon, a Timken company, launched HVC-MG and H1C-MG telescopic rails with integrated magnets for sequential opening. The redesigned ball cage increases load capacity, and the rails suit compact equipment cabinets and medical device enclosures.
Linear Motion Bearing Market Key Players are:
-
THK Co., Ltd.
-
NSK Ltd.
-
NB Corporation
-
Hiwin Technologies Corp.
-
Schaeffler AG
-
Bosch Rexroth AG
-
Nippon Thompson Co., Ltd. (IKO)
-
igus GmbH
-
Thomson Industries (Regal Rexnord)
-
HepcoMotion
-
Rollon S.p.A.
-
Bishop-Wisecarver Group
-
Chieftek Precision Co., Ltd. (CPC)
-
Schneeberger AG
Linear Motion Bearing Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.61 Billion |
| Market Size by 2035 | USD 6.25 Billion |
| CAGR | CAGR of 5.64% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Ball Bearings, Roller Bearings, Needle Bearings, and Plain Bearings) • By Material (Steel, Ceramic, Plastic, and Composite) • By Application (Industrial Machinery, Automotive, Medical Devices, Aerospace and Defense, and Electronics) • By End-User (OEMs and Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | THK Co., Ltd., NSK Ltd., NB Corporation, Hiwin Technologies Corp., Schaeffler AG, Bosch Rexroth AG, Nippon Thompson Co., Ltd. (IKO), igus GmbH, Thomson Industries (Regal Rexnord), HepcoMotion, Rollon S.p.A., Bishop-Wisecarver Group, Chieftek Precision Co., Ltd. (CPC), Schneeberger AG |

Frequently Asked Questions
The key players in the Linear Motion Bearing Market include THK Co., Ltd., NSK Ltd., NB Corporation, Hiwin Technologies Corp., Schaeffler AG, Bosch Rexroth AG, among others.
Key opportunities include aerospace production ramp-ups, semiconductor and medical equipment growth, and smart bearings with condition monitoring that support service revenue.
The major growth factor is the expansion of factory automation and semiconductor equipment investment, which adds precision linear axes and raises replacement demand.
The Ball Bearings segment dominated the Linear Motion Bearing Market with approximately 43.62% share in 2025, supported by low friction, wide availability and broad automation use.
Asia Pacific dominated the Linear Motion Bearing Market with a 38.14% share in 2025, driven by robot, machine tool and electronics manufacturing in China, Japan, Taiwan and South Korea.
