
Lutein Market Report Scope & Overview:
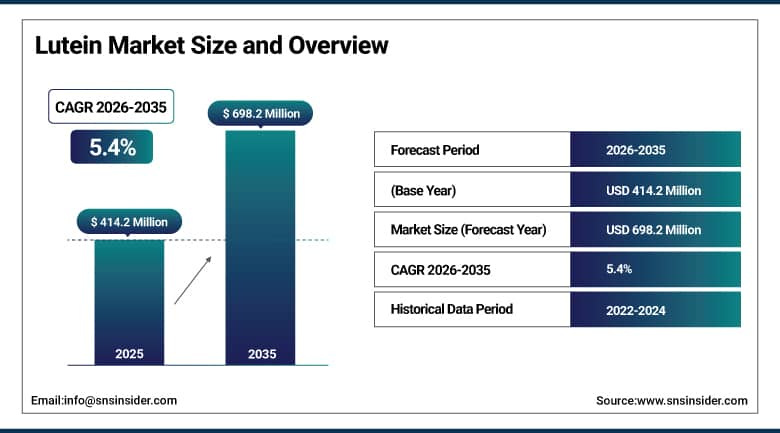
The global Lutein Market was valued at USD 414.2 Million in 2025 and is expected to reach USD 698.2 Million by 2035, growing at a CAGR of 5.4% from 2026 to 2035.
The global Lutein Market is growing steadily, owing to rising awareness about eye health and the growing incidences of age-related eye problems. Growing consumer awareness about healthcare and health supplements has been boosting the demand for lutein because of its antioxidant properties and health benefits to the macula. Increasing use of lutein in dietary supplements, functional food and beverages, pharmaceutical products, and animal nutrition has opened up new avenues for the market. Product innovations such as beadlets, oil suspensions, powders, and emulsions have enhanced the product formulation and increased the product bioavailability. In addition, rising population aged, rising healthcare spending, and adoption of health-conscious lifestyles have fueled the market demand.
Kemin Industries continues to operate its vertically integrated FloraGLO platform, with marigold flowers grown and hand-picked in India before being shipped to the company's Des Moines, Iowa headquarters for processing into unesterified lutein, reflecting the scale of supply chain integration that leading players maintain to secure raw material sourcing and mitigate geopolitical risks across the global lutein value chain.
Market Size and Forecast
-
Market Size in 2026E: USD 436.6 Million
-
Market Size by 2035: USD 698.2 Million
-
CAGR: 5.4% from 2026 to 2035
-
Fastest Growing Region: North America
-
Largest Region: Europe
To Get More Information On Lutein Market - Request Free Sample Report
Lutein Market Trends
-
Growing supercritical CO2 extraction and microencapsulation technologies are enhancing lutein stability, solubility, and absorption across diverse product formats.
-
Rising microalgae-based production research is emerging as a natural alternative to traditional marigold sourcing, with productivity rates several times higher.
-
Expanding lipid-based delivery system development is improving lutein bioavailability across dietary supplements, functional foods, and pharmaceutical applications.
-
Increasing consumer demand for clean-label, plant-based formulations continues to reinforce natural lutein's premium positioning over synthetic alternatives.
-
Growing cosmetics and personal care sector adoption is emerging as a rapidly growing application segment beyond traditional dietary supplement use cases.
U.S. Lutein Market Outlook
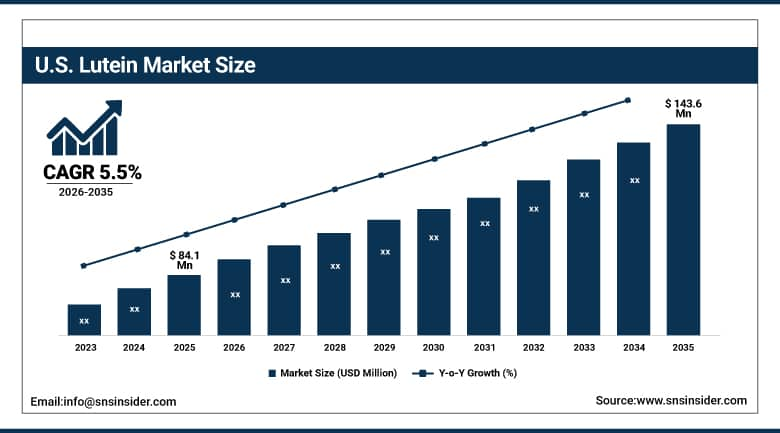
The U.S. Lutein Market was valued at USD 84.1 Million in 2025 and is projected to reach USD 143.6 Million by 2035, growing at a CAGR of 5.5% during 2026-2035.
The U.S. Lutein Market is experiencing steady growth, due to the growing awareness about eye health and the need for antioxidants in preventive nutrition. Increased instances of problems in relation to vision with age is causing people to use lutein dietary supplements. The increasing demand for functional food, beverages, and nutraceuticals is also helping to fuel demand for lutein products. The increased use of lutein in pharmaceuticals, cosmetics, personal care products, and animal feed has also provided new avenues for market growth. The development of products that provide better absorption, such as beadlets, suspensions, and emulsions is aiding the growth of this market.
Kemin Industries completed the acquisition of CJ Youtell Biotech, an enzymes and fermentation subsidiary, in September 2025, strengthening the company's overall biotechnology and fermentation platform and providing a strategic advantage for potential future alternative, non-agricultural lutein production methods, reinforcing Kemin's continued investment in long-term supply resilience beyond its traditional marigold-derived production model.
Lutein Market Segment Analysis
-
By Source, Natural led the Lutein Market with a 62.30% share in 2025, while Synthetic is the fastest-growing source segment with a CAGR of 6.20% from 2026-2035.
-
By Form, Powder & Crystalline led the Lutein Market with a 42.47% share in 2025, while Beadlet is the fastest-growing form segment with a CAGR of 6.40% from 2026-2035.
-
By Application, Dietary Supplements led the Lutein Market with a 46.60% share in 2025, while Cosmetics & Personal Care is the fastest-growing application segment with a CAGR of 8.20% from 2026-2035.
-
By Production Process, Extraction from Botanical Materials led the Lutein Market with a 58.60% share in 2025, while Algae Route is the fastest-growing production process segment with a CAGR of 9.40% from 2026-2035.
By Source, Natural Dominates the Lutein Market While Synthetic Emerges as the Fastest-Growing Source
Natural dominated the Lutein Market owing to the preference of consumers toward natural carotenoids and the growing need for natural nutritional ingredients. The use of natural lutein, mainly the one extracted from marigold flowers, is preferred for use in dietary supplements, functional foods, and eye-health products, due to their proven safety and acceptance by customers. The awareness of preventive eye health, usage of plant-derived ingredients, and established methods of extraction drive the growing consumption of lutein.
Synthetic is the fastest-growing source segment in the Lutein Market, due to the rising demand for the purity and controlled composition of the ingredients. The use of synthetic lutein provides manufacturers control over the specification and availability of the ingredient, which makes it applicable in standardized applications. The growing demand from nutrition and personal care manufacturers encourages investment in the production technologies.
By Form, Powder & Crystalline Dominate the Lutein Market While Beadlet Registers the Fastest Growth
Powder & Crystalline dominated the Lutein Market owing to its versatility, stability, and applicability. Powder & Crystalline form of lutein is highly popular as it can be formulated easily into capsules, tablets, and powdered mixes. Consumers' interest in eye-care supplements and preventative nutrition is compelling manufacturers to provide an increased range of such products on the basis of stable powder & crystalline forms of lutein.
Beadlet is the fastest-growing form segment in the Lutein Market, due to enhanced stability, controlled-release, and protection from degrading agents. Lutein beads allow for protecting lutein from light, oxygen, and other processing factors. Increasing demand for convenient forms of dosage and improved ingredient characteristics is compelling manufacturers to adopt beadlet technology. Recent advancements in formulation technology are also creating new opportunities for lutein beads.
By Application, Dietary Supplements Dominate the Lutein Market While Cosmetics & Personal Care Experiences the Fastest Growth
Dietary Supplements dominated the Lutein Market owing to the increasing awareness about eye health, preventive healthcare expenditures, and the acceptance of carotenoids as nutritional products among consumers. Lutein is used widely in capsules, tablets, softgels, and various combinations to promote eye wellness. Factors such as an increase in the aging population, screen exposure, and the desire to maintain good eye health over time are driving demand for the segment. Existing distribution channels, expansion in nutraceutical range, and increased presence via pharmacies, specialty stores, and online retailers bolster the segment's leadership position.
Cosmetics & Personal Care is the fastest-growing application segment in the Lutein Market, due to the interest in antioxidants and multibenefit beauty ingredients. The demand for lutein in cosmetic and personal care products is increasing due to its antioxidant benefits and its ability to help in skin protection against oxidative stress. Increasing consumer preference for premium and science-backed personal care products is motivating manufacturers in this regard. Growing trends in clean beauty, skin wellness, and carotenoid-based active ingredients are opening up opportunities for lutein in topical products.
By Production Process, Extraction from Botanical Materials Dominates the Lutein Market While Algae Route Emerges as the Fastest-Growing Process
Extraction from Botanical Materials dominated the Lutein Market as the Marigold Flowers had already been used as a natural source of lutein. This method has an advantage due to the developed technologies of extraction, well-established supply chain, and a natural inclination of consumers to consume products of natural origin. It is possible to produce lutein for dietary supplements, functional foods, etc. while preserving its natural profile. Development of better extraction, purification, and processing technologies adds to the scale of the segment.
Algae Route is the fastest-growing production process segment in the Lutein Market, due to the interest in the development of other biological sources for natural ingredients and more sustainable production of lutein. The advantage of algae-based production is that it allows for constant supply of the raw materials and more effective use of resources compared with traditional botanical sourcing. The increasing demand for carotenoids and biotechnological development encourages companies to produce lutein from algae.
Regional Insights
|
Region |
Country |
Share (2025) |
|---|---|---|
|
Europe |
Germany |
24.80% |
|
North America |
United States |
84.60% |
|
Asia Pacific |
India |
36.60% |
|
Middle East & Africa |
UAE |
20.60% |
|
Latin America |
Brazil |
22.60% |
Europe Lutein Market Insights
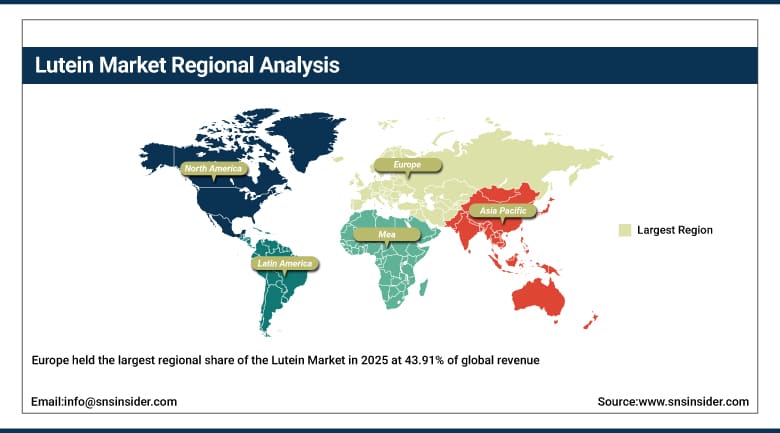
Europe held the largest regional share of the Lutein Market in 2025 at 43.91% of global revenue, supported by a dense concentration of leading carotenoid and lutein technology companies headquartered across the region and strong regulatory frameworks favoring natural, functional ingredients. Growing aging population spending on lutein-based dietary supplements continues to reinforce Europe's leadership position across the broader lutein landscape.
Germany led the European market with a 24.80% regional share in 2025, supported by its strong domestic nutraceutical manufacturing base and concentration of leading carotenoid ingredient suppliers. France, Switzerland, and the Netherlands are also contributing meaningfully to regional growth, supported by leading global lutein technology developers headquartered across the region.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Lutein Market Insights
North America is anticipated to be the fastest-growing regional market for the Lutein Market, driven by rising consumer awareness regarding eye health and increasing demand for natural ingredients in dietary supplements and functional foods. The United States is projected to be the fastest-growing individual country market, supported by strong innovation in extraction technology and clean-label formulation.
The United States accounted for approximately 84.60% of the North American market in 2025, reflecting its concentration of leading lutein ingredient suppliers and strong consumer demand for eye health and antioxidant supplementation. Canada is contributing to regional growth through steady dietary supplement adoption and growing consumer interest in natural, plant-based nutritional ingredients.
Asia Pacific Lutein Market Insights
Asia Pacific represented a meaningful share of the global Lutein Market in 2025, anchored by India's substantial marigold cultivation base supported by government initiatives including the National Horticulture Mission promoting horticulture cultivation of lutein source materials. Rising domestic dietary supplement consumption continues to reinforce steady regional demand for both raw material supply and finished lutein products.
India accounted for approximately 36.60% of the Asia Pacific market in 2025, supported by its position as a leading global marigold cultivation and lutein extraction hub benefiting from national horticulture mission subsidies and technical support. China, Japan, and South Korea are also contributing meaningfully to regional growth, with China's expanding domestic supplement manufacturing capacity reinforcing sustained regional demand.
Middle East & Africa and Latin America Lutein Market Insights
The Middle East & Africa region holds significant untapped potential, alongside South America, particularly in marigold-rich nations bolstering extraction and processing capabilities while capitalizing on cost-effective raw material availability. Regulatory harmonization and an influx of foreign investment in food processing continue to position these regions for accelerated market development in the coming years.
The UAE led the Middle East & Africa market with a 20.60% regional share in 2025, supported by growing dietary supplement retail infrastructure and rising consumer health awareness. Brazil represented 22.60% of the Latin American market in 2025, while marigold-rich nations including Mexico and Peru continue bolstering extraction and processing capabilities, with regional foreign investment supporting accelerated market development.
Growth Drivers: Eye Health Awareness and Clean-Label Ingredient Demand Driving Market Growth
The Lutein Market is being driven primarily by rising consumer awareness regarding eye health, increasing demand for natural ingredients in dietary supplements and functional foods, and expanding applications in pharmaceuticals and personal care products. The rising prevalence of age-related macular degeneration represents a significant driver, as lutein and zeaxanthin are recognized for their role in protecting the macula, leading to a surge in demand for lutein supplements among individuals seeking to safeguard vision and delay or prevent AMD progression.
Growing supercritical CO2 extraction and microencapsulation technologies continue to enhance lutein stability, solubility, and absorption across diverse product formats. Rising microalgae-based production research is emerging as a natural alternative to traditional marigold sourcing, with productivity rates significantly higher. Expanding lipid-based delivery system development is further improving lutein bioavailability across dietary supplements, functional foods, and pharmaceutical applications, reinforcing sustained category investment.
Restraints: Raw Material Supply Concentration and Consumer Price Sensitivity Limiting Market Expansion
Despite favorable underlying demand, the market faces meaningful restraints related to geographic concentration of marigold cultivation in a limited number of producing regions, creating potential supply chain vulnerability for manufacturers dependent on consistent raw material availability. Synthetic lutein alternatives, despite their cost advantages, continue to face resistance from consumers, particularly in developed markets with high clean-label awareness, limiting synthetic segment penetration in premium application categories.
High energy requirements associated with microalgal biomass disruption processes, which can require substantially more energy than marigold flower crushing, continue to constrain broader commercial adoption of algae-based production despite superior productivity potential. Weather-dependent crop yield variability affecting marigold cultivation also continues to introduce supply chain unpredictability that complicates long-term procurement planning for lutein manufacturers and downstream customers.
Opportunities: Microalgae Production Innovation and Personal Care Expansion Creating New Growth Avenues
Substantial opportunity exists in continued development of microalgae-based lutein production technology capable of delivering measurable productivity improvements over traditional marigold extraction while reducing dependence on geographically concentrated agricultural supply chains. Companies that successfully commercialize scalable algae cultivation platforms stand to capture significant share of category growth as the technology continues maturing toward broader commercial viability.
Growing cosmetics and personal care sector adoption presents a further significant growth avenue, as lutein's antioxidant properties gain increasing recognition for topical skin health applications beyond conventional dietary supplement and food fortification use cases. Expanding infant formula and functional food applications, where natural ingredients command premium pricing, also represent meaningful untapped opportunity for lutein ingredient suppliers.
Recent Developments:
-
2026: DSM-Firmenich rolled out a vitamin transformation initiative, weaving precision fermentation technologies into its production to boost margins and enhance manufacturing sustainability.
-
2023: OmniActive Health Technologies launched its 'Lutein for Every Age' campaign to enhance awareness of macular carotenoids in children's brain and eye health.
-
2025-2026: Marigold-rich nations including Mexico and Peru continued bolstering extraction and processing capabilities amid rising foreign investment in regional food processing infrastructure.
-
2025-2026: Leading lutein manufacturers continued advancing microalgae-based production research, with studies showing lutein productivity rates several times higher than traditional marigold extraction.
Lutein Companies are:
-
Kemin Industries, Inc.
-
BASF SE
-
DSM-Firmenich N.V.
-
OmniActive Health Technologies
-
Allied Biotech Corporation
-
E.I.D. Parry (India) Limited
-
Divi’s Laboratories Limited
-
Merck KGaA
-
Piveg, Inc. (Industrial Orgánica)
-
Synthite Industries Pvt. Ltd.
-
Zhejiang Medicine Co., Ltd.
-
Döhler GmbH
-
Lycored Ltd.
-
FENCHEM Biotek Ltd.
-
Katra Phytochem Pvt. Ltd.
-
Xi’an Healthful Biotechnology Co., Ltd.
-
Chenguang Biotech Group Co., Ltd.
-
Bio-gen Extracts Pvt. Ltd.
-
Sabinsa Corporation
-
Naturex (Givaudan)
Lutein Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 414.2 Million |
| Market Size by 2035 | USD 698.2 Million |
| CAGR | CAGR of 5.4% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Source (Natural, Synthetic) • By Form (Powder & Crystalline, Oil Suspension, Beadlet, Emulsion) • By Application (Dietary Supplements, Food & Beverages, Pharmaceuticals, Cosmetics & Personal Care, Animal Feed) • By Production Process (Extraction from Botanical Materials, Chemical Synthesis, Fermentation, Algae Route) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Kemin Industries, Inc., BASF SE, DSM-Firmenich N.V., OmniActive Health Technologies, Allied Biotech Corporation, E.I.D. Parry (India) Limited, Divi’s Laboratories Limited, Merck KGaA, Piveg, Inc. (Industrial Orgánica), Synthite Industries Pvt. Ltd., Zhejiang Medicine Co., Ltd., Döhler GmbH, Lycored Ltd., FENCHEM Biotek Ltd., Katra Phytochem Pvt. Ltd., Xi’an Healthful Biotechnology Co., Ltd., Chenguang Biotech Group Co., Ltd., Bio-gen Extracts Pvt. Ltd., Sabinsa Corporation, Naturex (Givaudan) |

Frequently Asked Questions
The Lutein Market is expected to grow at a CAGR of 5.4% from 2026 to 2035.
The Lutein Market was valued at USD 414.2 Million in 2025.
The market is driven by rising consumer awareness regarding eye health, increasing demand for natural ingredients in dietary supplements and functional foods, and expanding pharmaceutical applications.
The Natural segment dominated the Lutein Market in 2025.
The Europe region dominated the Lutein Market in 2025.
