
Microcontroller Market Report Scope & Overview:
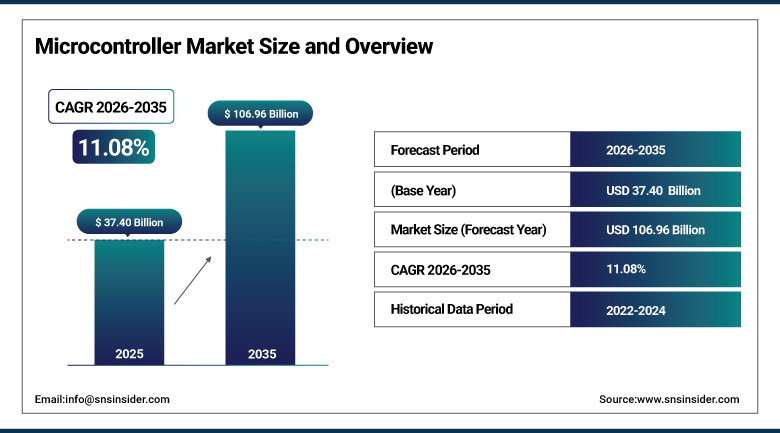
The Microcontroller Market was valued at USD 37.40 Billion in 2025 and is expected to reach USD 106.96 Billion by 2035, growing at a CAGR of 11.08% from 2026-2035.
The Microcontroller Market covers single-chip computers that combine a processor core, memory and input and output peripherals, which are embedded in products to sense, decide and control. They are found in cars, appliances, industrial controllers, medical devices, wearables, wireless modules and countless connected objects. Product choices span 8-bit and 16-bit parts for simple control to 32-bit Arm and RISC-V devices with wireless radios, security engines and neural accelerators, and 64-bit parts for richer edge workloads. Vehicle electrification, factory automation and the spread of connected sensors are raising the number of controllers in each product, while supply security and design cost push makers toward open architectures and longer-lived platforms through 2035. Design wins today lock in demand for many years.
⮞The Semiconductor Industry Association reported on 6 August 2026 that global semiconductor sales in the second quarter of 2026 rose 35.1% from the first quarter, reflecting strong demand across chip categories.
To Get more information Microcontroller Market - Request Free Sample Report
Microcontroller Market Trends
-
Neural processing units are being added to controllers so that keyword spotting, anomaly detection and image classification can run locally at milliwatt power levels.
-
RISC-V controllers are multiplying across wireless, storage and automotive designs as companies seek open and customizable architectures.
-
Automotive controllers are moving to advanced process nodes with hardware security, post-quantum cryptography and high-speed in-vehicle networking.
-
New non-volatile memories such as ferroelectric and phase-change types are being embedded as scalable alternatives to flash.
-
Wireless controllers supporting Matter, Bluetooth Low Energy and Wi-Fi 6 are expanding connected products in homes, buildings and factories.
U.S. Microcontroller Market Outlook
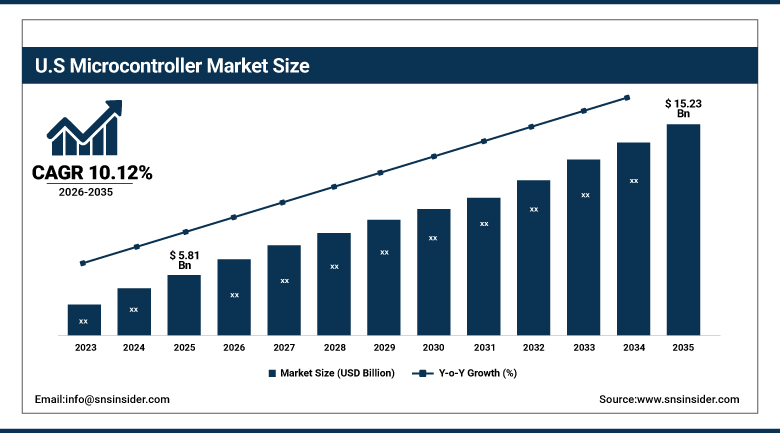
The U.S. Microcontroller Market was valued at USD 5.81 Billion in 2025 and is expected to reach USD 15.23 Billion by 2035, growing at a CAGR of 10.12% from 2026-2035.
The U.S. Microcontroller Market is the largest national market in North America, supported by leading chip designers, automotive and aerospace programs, industrial automation, medical device makers and a vibrant community of start-ups building connected products. Federal incentives for local chip manufacturing and research are encouraging new fabrication and packaging capacity, while defense and space programs buy secure and radiation-tolerant controllers. Automotive assembly in the Midwest and South, together with growing battery and charging infrastructure, increases demand for automotive grade parts. Developers rely on mature ecosystems of software tools, cloud services and distributors that shorten design cycles, which supports strong growth through 2035. Government laboratories add research demand.
⮞The Federal Reserve reported on 17 July 2026 that the June 2026 industrial production index for semiconductors and related components stood at 181.9, with 2017 equal to 100.
Microcontroller Market Segment Analysis
-
By Product, the 32-Bit segment dominated the Microcontroller Market with approximately 53.86% share in 2025, while the 64-Bit segment is the fastest growing with a CAGR of approximately 15.21%.
-
By Architecture, the ARM segment dominated the Microcontroller Market with approximately 67.34% share in 2025, while the RISC-V segment is the fastest growing with a CAGR of approximately 16.43%.
-
By Memory, the Embedded Flash segment dominated the Microcontroller Market with approximately 86.27% share in 2025, while the FRAM segment is the fastest growing with a CAGR of approximately 13.08%.
-
By Application, the Consumer Electronics & Telecom segment dominated the Microcontroller Market with approximately 26.74% share in 2025, while the Automotive segment is the fastest growing with a CAGR of approximately 13.37%.
By Product, 32-Bit Dominates the Microcontroller Market and 64-Bit Grows Fastest
The 32-bit class holds approximately 53.86% of the Microcontroller Market in 2025 because it offers the best balance of performance, memory, peripherals and power efficiency for modern products. Designers use these controllers for motor drives, wireless connectivity, graphical displays, security functions and over-the-air updates that outgrow older 8-bit and 16-bit parts. Prices of 32-bit devices have fallen close to those of simpler chips, which encourages migration even in cost-sensitive appliances and toys. A large software ecosystem, real-time operating systems and ready-made libraries reduce development effort, and vendors offer broad families that scale from small to feature-rich variants. Distributors stock these parts widely, so prototypes reach production quickly.
The 64-bit class is the fastest growing, with a CAGR of approximately 15.21% during 2026-2035. These controllers extend beyond traditional embedded control into edge computing, vision, gateways and in-vehicle domain control, where larger address spaces and higher throughput are needed. Integration of neural processing units lets devices run machine learning models for keyword spotting, anomaly detection and image classification locally. Industrial gateways and smart displays also benefit from richer operating systems. Volumes remain small next to 32-bit parts, yet higher selling prices and design wins in automotive and infrastructure equipment are driving rapid revenue growth. Early adopters report faster inference at lower energy.
⮞The Ericsson Mobility Report of June 2026 said cellular IoT connections reached 4.5 billion at the end of 2025 and are expected to reach 8 billion by 2031.
By Architecture, ARM Dominates the Microcontroller Market and RISC-V Grows Fastest
Arm-based cores account for approximately 67.34% share in 2025, since the Cortex-M family is the default choice across consumer, industrial and automotive designs. Broad vendor support means engineers can move code between suppliers, and mature debuggers, compilers and security frameworks reduce risk. Licensing gives chip makers access to proven cores with a range of performance points from ultra-low-power to high-performance, and certified safety packages ease use in vehicles and medical devices. The long installed base of firmware and developer skills keeps new projects aligned with the architecture even as alternatives arrive. Silicon vendors also supply reference designs that cut time to market for small teams.
RISC-V is the fastest growing architecture, with a CAGR of approximately 16.43% through 2035. The open instruction set avoids license fees and gives companies freedom to add custom instructions, which is attractive to wireless, storage and automotive designers. Regional suppliers in Asia have launched large families of RISC-V controllers, and global vendors are announcing automotive roadmaps built on the architecture. Tooling and operating system support are maturing rapidly, narrowing the gap with established ecosystems. Governments and companies seeking supply independence view open architectures as a strategic choice.
⮞RISC-V International reported in its 2025 annual report, published in January 2026, that 17 new members joined the organization during 2025.
By Memory, Embedded Flash Dominates the Microcontroller Market and FRAM Grows Fastest
Embedded flash dominates with approximately 86.27% share in 2025 because it stores firmware on the same die as the processor, supports in-field updates and offers a mature, low-cost process across many nodes. Most general purpose controllers integrate flash blocks from a few kilobytes to several megabytes, and automotive parts use qualified versions with long data retention and high endurance. Software-defined products depend on flash capacity for new features and security patches. However, scaling flash below advanced nodes becomes difficult, prompting suppliers to evaluate alternatives for next generation devices. Customers still value its proven reliability in safety-critical systems.
Ferroelectric RAM is the fastest growing memory type, with a CAGR of approximately 13.08% during 2026-2035. It writes quickly at very low energy and endures far more write cycles than flash, which suits data logging, metering, wearables and energy harvesting designs. Because it retains data without power and avoids the long erase times of flash, it can capture information at the moment of a power loss. Newer non-volatile memories, including magnetic and resistive types, are also entering controllers at advanced nodes, and suppliers promote them as scalable replacements for embedded flash. Qualification for automotive use is progressing.
⮞The World Semiconductor Trade Statistics organization reported on 6 August 2026 that memory sales grew about 305% year on year in the first half of 2026.
By Application, Consumer Electronics & Telecom Dominates the Microcontroller Market and Automotive Grows Fastest
Consumer electronics and telecom applications hold the largest share, at approximately 26.74% in 2025, owing to the sheer number of controllers placed in appliances, personal devices, toys, remote controls, smart speakers, wearables, routers and network equipment. A typical household contains dozens of embedded controllers, from kitchen appliances to chargers. Wireless-enabled devices need controllers with integrated radios and security. Short product cycles and cost pressure favor high volume, low price parts, and the arrival of smart home standards is encouraging manufacturers to embed connectivity into more products. Smart home hubs and routers are particularly strong volume drivers.
Automotive is the fastest growing application, with a CAGR of approximately 13.37% through 2035. Each vehicle contains scores of controllers for powertrain, body, safety, lighting and infotainment functions, and electrification adds battery management, inverters, chargers and thermal control. Advanced driver assistance and zonal architectures consolidate functions into more powerful controllers with strict safety and security requirements. Software-defined vehicle strategies raise memory and processing needs, and long design cycles lead to multi-year supply commitments. Qualification to automotive standards creates entry barriers and supports pricing. Suppliers hold design wins for years.
⮞The Japan Electronics and Information Technology Industries Association reported that Japan's consumer electronic equipment output ran at 114.1% of the prior-year level in June 2026.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
83.46% |
|
Asia Pacific |
China |
42.18% |
|
Europe |
Germany |
29.64% |
|
Latin America |
Brazil |
47.35% |
|
Middle East & Africa |
United Arab Emirates |
28.71% |
North America Microcontroller Market Insights
North America held approximately 18.62% of the Microcontroller Market in 2025, with the United States contributing about 83.46% of regional demand and Canada the balance. The region is home to leading controller designers and a deep base of automotive, aerospace, defense, medical and industrial customers. Public funding for semiconductor manufacturing and research is encouraging new facilities, and defense programs require secure supply chains. Automotive assembly plants in the Midwest and South consume large volumes of automotive grade parts, and the rollout of charging networks and battery factories adds further demand.
Developers in the region lead in edge artificial intelligence, robotics, drones and wearable health products, and cloud providers support them with development platforms. Distributors with broad inventories and technical support help small companies move from prototypes to production. Canada contributes through automotive suppliers, telecom equipment and industrial automation. Strong venture funding supports start-ups that design smart sensors and connected devices, and universities provide talent in embedded systems. Security and safety certification requirements encourage purchases of higher value, qualified controllers. Aerospace primes add demand.
⮞The U.S. Food and Drug Administration authorized 331 artificial intelligence-enabled medical devices in 2025, the most in its history, according to its list updated in March 2026.
Europe Microcontroller Market Insights
Europe accounted for approximately 16.45% of the Microcontroller Market in 2025, led by Germany, France, Italy and the United Kingdom. The region has leading automotive manufacturers and suppliers, industrial automation groups and several of the world's largest controller makers. Safety, security and energy efficiency regulations steer designers toward qualified parts, and manufacturers invest in power electronics for electric vehicles and renewable energy. Public programs aim to strengthen semiconductor capacity in the region, and research institutes collaborate with industry on open architectures and neuromorphic computing. Universities supply skilled engineers.
Germany dominates demand through automotive and machinery, while France, Italy and Spain add volumes through appliances, aerospace and industrial controls. The Nordic countries lead in wireless and low-power designs, with strong clusters of connected device developers. Eastern European countries host growing assembly plants for vehicles and electronics, increasing local purchases. Cyber resilience rules for connected products raise requirements for secure boot and update features, supporting higher-value controllers. Supply disruptions in recent years have encouraged buyers to hold buffer stocks and qualify second sources.
⮞Eurostat data reported on 1 July 2026 showed that electronics and telecommunications made up 23.1% of EU sold production of high-tech products in 2024.
Asia Pacific Microcontroller Market Insights
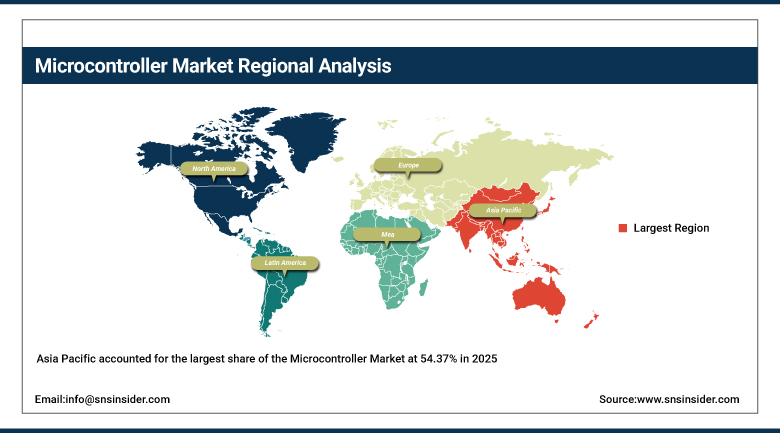
Asia Pacific accounted for the largest share of the Microcontroller Market at 54.37% in 2025 and is also the fastest growing region, expanding at a CAGR of 12.41% during 2026-2035. China, Japan, South Korea, Taiwan and India host the bulk of electronics assembly, consumer appliance production and automotive manufacturing, and the region contains major foundries and packaging houses. Local suppliers in China and Taiwan have built large families of low-cost controllers, while Japanese and Korean companies specialize in automotive and industrial parts. Proximity between designers, manufacturers and customers shortens development cycles.
China is both the largest producer and the largest consumer of controllers, supported by electric vehicle output, appliances, power tools and industrial equipment, with strong government support for local semiconductor supply. India is growing quickly through electronics assembly incentives and vehicle production. Southeast Asia, led by Malaysia, Vietnam and Thailand, hosts testing and assembly operations that bring controller demand closer to the supply base. Taiwan and South Korea contribute through foundry capacity and memory technology. Regional wireless standards and rapid rollout of smart devices also lift volumes.
⮞The China Association of Automobile Manufacturers reported on 16 October 2026 that China's vehicle production reached 23.246 million units in January-September 2026, with exports up 65.8%.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America Microcontroller Market Insights
The Middle East and Africa and Latin America together account for approximately 10.56% of the Microcontroller Market in 2025, with Latin America at 5.60% and the Middle East and Africa at 4.96%. Both regions import most controllers, either directly or inside finished goods, and demand follows local assembly of appliances, vehicles, meters and telecom equipment. In the Middle East, Saudi Arabia and the United Arab Emirates are investing in smart infrastructure, industrial diversification and electronics assembly. Africa is led by South Africa, Egypt and Nigeria, where mobile services and smart metering drive adoption of connected devices.
Latin America is led by Brazil and Mexico. Brazil has a sizeable automotive, appliance and electronics industry supported by local content incentives, while Mexico serves as an assembly hub for vehicles, electronics and medical devices exported to the United States. Argentina, Colombia and Chile add demand through agriculture technology, mining equipment and smart metering. Distributors and design service firms are important because many manufacturers lack in-house semiconductor expertise. Currency swings and import duties influence purchasing, and buyers often favor widely available controllers with strong support.
⮞The GSMA projected in November 2025 that 5G will rise from 7% of connections in the Middle East and North Africa in 2024 to 48% by 2030.
Market Dynamics
Growth Drivers: Vehicle Electrification and Connected Devices Drive Growth in the Microcontroller Market
Vehicle electrification and the growth of in-vehicle software are the strongest forces behind the Microcontroller Market. Electric drivetrains add controllers for battery management, inverters, onboard chargers, thermal systems and charging interfaces, while advanced driver assistance and zonal architectures require powerful safety-rated processors. Suppliers are launching controllers with higher performance, hardware security modules and support for fast in-vehicle networks. Every new electric model increases the number of controllers per vehicle, and long qualification cycles lead to stable multi-year demand for approved suppliers. Charging networks create additional embedded demand.
Connected devices provide a second driver. Industrial sensors, smart meters, wearables, trackers and building systems use controllers with integrated wireless radios and low power modes, and the number of cellular and short-range connections keeps rising. Factory automation, robotics and energy infrastructure also require more distributed intelligence. Edge machine learning increases the compute content of simple devices, encouraging upgrades from 8-bit and 16-bit parts to 32-bit and neural-accelerated controllers. Smart building and energy storage programs add steady orders from installers and utilities worldwide.
⮞The International Energy Agency reported on 20 May 2026 that electric car sales exceeded 20 million in 2025, about a quarter of new cars sold.
Restraints: Supply Chain Disruption and Design Complexity Restrain Growth in the Microcontroller Market
Supply chain fragility is the main restraint on the Microcontroller Market. Controllers depend on a limited number of foundries, packaging sites and specialized materials, and disruptions from export controls, trade disputes or plant shutdowns can halt production of vehicles and equipment. The shortage of recent years showed how long qualification periods make switching suppliers slow, leaving manufacturers exposed. Buyers respond with larger inventories and dual sourcing, which can distort demand and create inventory corrections that depress orders for a time.
Design complexity is a second challenge. Modern controllers require software for security, safety certification and over-the-air updates, and migrating across architectures costs time and money. Rising cybersecurity obligations add testing burdens, while price competition from regional suppliers pressures margins in consumer products. Some makers also face talent shortages in embedded software, and the rapid evolution of artificial intelligence workloads can strand investment in earlier platforms. Geopolitical tension complicates cross-border collaboration. Long lead times for advanced nodes can leave designers waiting many months for approved parts.
⮞The European Automobile Manufacturers' Association warned on 16 October 2025 that a halt in chip deliveries by one supplier could severely disrupt European vehicle production, with stocks expected to last only a few weeks.
Opportunities: Edge AI, RISC-V and Smart Home Standards Create Opportunities in the Microcontroller Market
Edge artificial intelligence creates a major opportunity as controllers gain neural processing units that run small models at milliwatt power levels. Applications include voice commands, predictive maintenance, gesture detection, anomaly detection in sensors and image recognition in battery-powered cameras. Processing data locally lowers latency, protects privacy and reduces cloud costs, which attracts appliance, industrial and health device makers. Suppliers that offer tools to train, compress and deploy models can differentiate and raise average selling prices. Developer communities further speed adoption.
Open architectures and smart home standards add further openings. RISC-V lets regional and start-up suppliers build customized controllers and gives device makers more control over supply. Standards for interoperable smart home devices are encouraging manufacturers to add wireless controllers to lighting, locks, thermostats and sensors that were previously unconnected. Medical wearables, energy harvesting sensors and agricultural monitors also expand the target base, and long-term software support can become a service revenue stream. Certification programs help smaller brands reach buyers. It also lowers risk.
⮞The Connectivity Standards Alliance released Matter 1.6 and Product Security 1.1 in June 2026, adding NFC setup and two assessment levels for connected products.
Recent Developments:
-
2026: Espressif previewed the ESP32-E22, a dual-core RISC-V controller running at up to 500 MHz with tri-band Wi-Fi 6E and Bluetooth 6.0, together with the ESP32-H21, a 96 MHz RISC-V device for Bluetooth Low Energy and 802.15.4, at CES 2026.
-
2026: Microchip launched the PIC32CM PL10 family of Arm Cortex-M0+ controllers, which are 5V-capable, pin-compatible with its AVR line and designed for functional safety use under ISO 26262.
-
2026: STMicroelectronics introduced the Stellar P3E, described as the first automotive controller with built-in artificial intelligence acceleration. It features 500 MHz Cortex-R52+ cores and phase-change memory with twice the density of embedded flash, with production planned for the fourth quarter of 2026.
-
2026: Renesas launched the RH850/U2C, a 28nm automotive controller with four cores at up to 320 MHz and up to 8 MB of flash, supporting ASIL D, CAN-XL, 10BASE-T1S and post-quantum cryptography.
Microcontroller Market Key Players are:
-
NXP Semiconductors N.V.
-
Renesas Electronics Corporation
-
STMicroelectronics N.V.
-
Microchip Technology Inc.
-
Infineon Technologies AG
-
Texas Instruments Incorporated
-
Espressif Systems (Shanghai) Co., Ltd.
-
Silicon Laboratories Inc.
-
Nordic Semiconductor ASA
-
Analog Devices, Inc.
-
Nuvoton Technology Corporation
-
GigaDevice Semiconductor Inc.
-
Geehy Semiconductor Co., Ltd.
-
Raspberry Pi Ltd.
-
Ambiq Micro, Inc.
-
Holtek Semiconductor Inc.
Microcontroller Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 37.40 Billion |
| Market Size by 2035 | USD 106.96 Billion |
| CAGR | CAGR of 11.08% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (8-Bit, 16-Bit, 32-Bit, and 64-Bit) • By Architecture (ARM, RISC-V, 8051, PIC, AVR, and Others) • By Memory (Embedded Flash, FRAM, EEPROM, and Others) • By Application (Automotive, Consumer Electronics and Telecom, Industrial, Medical Devices, Aerospace and Defense, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | NXP Semiconductors N.V., Renesas Electronics Corporation, STMicroelectronics N.V., Microchip Technology Inc., Infineon Technologies AG, Texas Instruments Incorporated, Espressif Systems (Shanghai) Co., Ltd., Silicon Laboratories Inc., Nordic Semiconductor ASA, Analog Devices, Inc., Nuvoton Technology Corporation, GigaDevice Semiconductor Inc., Geehy Semiconductor Co., Ltd., Raspberry Pi Ltd., Ambiq Micro, Inc., Holtek Semiconductor Inc. |

Frequently Asked Questions
The key players in the Microcontroller Market include NXP Semiconductors N.V., Renesas Electronics Corporation, STMicroelectronics N.V., Microchip Technology Inc., Infineon Technologies AG, among others.
Key opportunities include edge artificial intelligence with built-in neural processing units, RISC-V based customized controllers, and smart home standards that add wireless controllers to previously unconnected products.
The major growth factor is vehicle electrification and the spread of connected devices, which raise the number of controllers per vehicle, factory and building.
The 32-Bit segment dominated the Microcontroller Market with approximately 53.86% share in 2025, because it balances performance, memory, peripherals and power efficiency for modern products.
Asia Pacific dominated the Microcontroller Market with a 54.37% share in 2025, driven by electronics assembly, appliance production and automotive manufacturing in China, Japan, South Korea, Taiwan and India.
