
Ostomy Care and Accessories Market Report Scope & Overview:
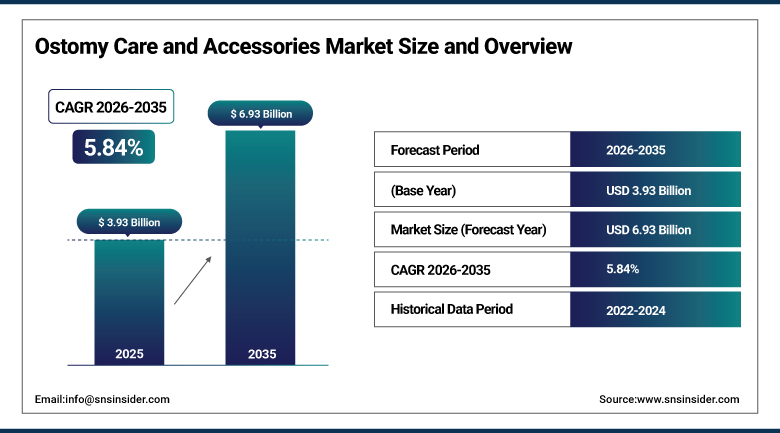
The Ostomy Care and Accessories Market was valued at USD 3.93 Billion in 2025 and is expected to reach USD 6.93 Billion by 2035, growing at a CAGR of 5.84% from 2026-2035.
Ostomy care and accessories market covers pouches, skin barriers, flanges, adhesive removers, belts, deodorants and other products used by people who have a stoma created by surgery for colorectal cancer, inflammatory bowel disease, bladder disease or trauma. Products collect waste, protect the skin around the stoma and let users live normally. Growth is supported by rising rates of bowel and bladder disease, aging populations and better product comfort, while reimbursement limits, skin problems and the shift to home care shape purchases.
⮞In August, 2026, Convatec reported in its half-year results that its Esteem Body ostomy range continued to gain share, reaching annualized revenue of about USD 60.00 million and a segment share of about 15.00%. The company said the Natura Body product is on track for launch in 2027, which would complete its soft convex portfolio, and that Ostomy Care grew 4.30% organically, led by Europe.
To Get more information Ostomy Care and Accessories Market - Request Free Sample Report
Ostomy Care and Accessories Market Trends
- Soft convex and moldable skin barriers that improve fit and reduce leaks
- Black and discreet pouches with easy-to-use closures
- Home care and telehealth support for people with new stomas
- Digital tools and apps for stoma care guidance and product ordering
- Accessories such as adhesive removers, rings and skin protectants
- Direct-to-patient supply models and expansion into new countries
U.S. Ostomy Care and Accessories Market Outlook
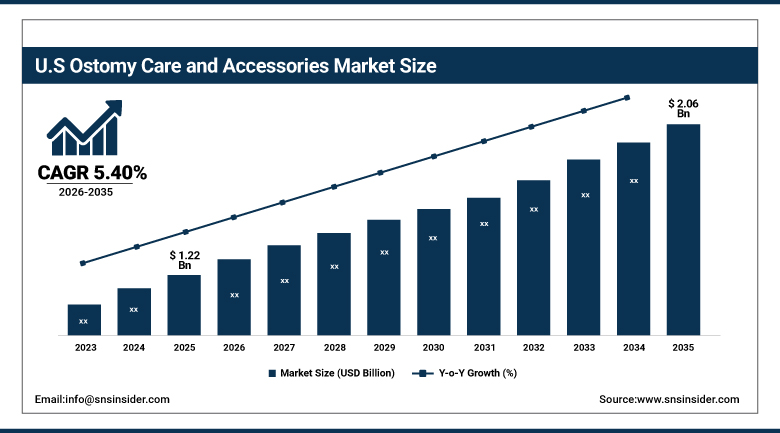
The U.S. Ostomy Care and Accessories Market was valued at USD 1.22 Billion in 2025 and is expected to reach USD 2.06 Billion by 2035, growing at a CAGR of 5.40% from 2026-2035.
The U.S. Ostomy Care and Accessories Market is the largest national market in the region, supported by a high number of colorectal and bladder surgeries, wide insurance coverage through Medicare and private plans, and a strong network of medical suppliers. Patients commonly order through supply companies that deliver monthly. Growth is moderated by reimbursement rules, supplier competition and the pull toward lower-cost products in some plans.
⮞Demand for new pouching systems is strong in the United States. Coloplast reported growth in Ostomy Care revenue, up 5% organically in June 2026, with growth in the United States described as strong double-digit in the third quarter. The company said its SenSura Mio black bags launch was significantly ahead of forecast.
Ostomy Care and Accessories Market Segment Analysis
- By Product, ostomy bags and pouching systems segment dominated the Ostomy Care and Accessories Market in 2025 with an estimated 78.00% share; ostomy accessories segment is the fastest-growing segment, with an estimated CAGR of 7.30% during 2026–2035.
- By Application, colostomy segment dominated the Ostomy Care and Accessories Market in 2025 with an estimated 46.00% share; ileostomy segment is the fastest-growing segment, with an estimated CAGR of 6.40% during 2026–2035.
- By End User, hospitals and clinics segment dominated the Ostomy Care and Accessories Market in 2025 with an estimated 41.00% share; home care settings segment is the fastest-growing segment, with an estimated CAGR of 7.60% during 2026–2035.
- By Distribution Channel, retail pharmacies segment dominated the Ostomy Care and Accessories Market in 2025 with an estimated 38.00% share; online channels segment is the fastest-growing segment, with an estimated CAGR of 11.00% during 2026–2035.
By Product, Ostomy Bags and Pouching Systems Dominates Ostomy Care Market; Ostomy Accessories to Register Fastest Growth.
Ostomy bags and pouching systems dominate the Ostomy Care and Accessories Market because every person with a stoma needs pouches, which are replaced every one to several days. One-piece and two-piece systems, drainable and closed pouches, and urostomy pouches generate steady repeat purchases. Reimbursement programs cover regular supplies, and patients tend to stay with brands that fit well and do not leak. Because pouches must be changed so often, even small gains in comfort or wear time can shift loyalty between brands. Manufacturers also supply sample programs through hospitals and nurses to win new patients at the time of surgery.
Ostomy accessories are projected to register the fastest growth as users and nurses look for ways to extend wear time, protect skin and control odor. Barrier rings, paste, powders, adhesive removers, belts and covers are sold along with pouches, and many are bought outside reimbursement. Product innovation and patient education encourage use of these add-ons. Many accessory items are sold directly to consumers, which gives manufacturers higher margins than reimbursed pouches. Education from nurses and online communities spreads awareness of accessories among patients who might not otherwise try them.
By Application, Colostomy Dominates Ostomy Care Market; Ileostomy to Register Fastest Growth.
Colostomy dominates the Ostomy Care and Accessories Market because surgery for colorectal cancer, diverticular disease and trauma often creates a colostomy, and these stomas are usually permanent. Users require pouches continuously, often for decades. A high number of colorectal procedures in older adults sustains volumes of closed and drainable pouches. Because a permanent colostomy typically lasts for life, the customer relationship runs for decades, which makes repeat sales predictable and encourages manufacturers to invest in long-term user support and loyalty services.
Ileostomy is projected to register the fastest growth as inflammatory bowel disease rises and as temporary ileostomies are used more often after rectal cancer surgery. Output is more liquid and irritating to skin, so users need high-quality barriers, drainable pouches and accessories. Specialist nurses and product makers focus on this group to improve outcomes. Clinical guidelines emphasize skin protection and proper fit for people with high-output stomas, and nutrition and hydration support is part of care. Specialized products for high output and for sensitive skin are an area of active development.
By End User, Hospitals and Clinics Dominates Ostomy Care Market; Home Care Settings to Register Fastest Growth.
Hospitals and clinics dominate the Ostomy Care and Accessories Market because surgery, first fitting and stoma nurse education take place there, and many patients are supplied with their first products by the hospital. Institutional purchasing contracts cover large volumes, and nurses influence which brands patients continue using after discharge. Hospitals also serve as the main point for training family members and caregivers, and they often agree supply contracts that include education materials. This ensures a steady flow of new users into the supply chain.
Home care settings are projected to register the fastest growth as shorter hospital stays shift ongoing care to patients' homes and community nurses. Supply companies deliver products by mail, and telehealth services support users with questions about skin and fit. Digital tools and subscription ordering make it easier to maintain supplies at home. Community nurses and telehealth platforms can check fit and skin condition remotely, which cuts the need for clinic visits. Insurers and health systems favor this model because it reduces hospital readmissions linked to stoma complications.
By Distribution Channel, Retail Pharmacies Dominates Ostomy Care Market; Online Channels to Register Fastest Growth.
Retail pharmacies dominate the Ostomy Care and Accessories Market because many patients collect prescribed products from community pharmacies, where staff can advise on sizing and replacements. In several countries, reimbursement systems direct supplies through pharmacies or dispensing appliance contractors. Established supply relationships and trust in pharmacists keep this channel ahead of others. Dispensing appliance contractors and medical supply companies often handle prescriptions and deliveries, and they bundle accessories with core products. Chains with national coverage have an advantage in negotiating with manufacturers and payers.
Online channels are projected to register the fastest growth as patients and caregivers prefer home delivery, discreet packaging and easy reordering. Specialist online suppliers offer samples and nurse advice, and manufacturers are building direct-to-patient services. Younger users and caregivers are comfortable with digital ordering, which supports expansion. Marketplace platforms also give smaller brands a route to reach consumers without pharmacy contracts. Reviews and discussion forums help buyers compare products, though clinical advice remains important for safe use. Direct-to-patient programs by manufacturers also offer free samples and nurse calls.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Europe |
Germany |
24.00 |
|
North America |
United States |
91.00 |
|
Asia Pacific |
Japan |
33.00 |
|
Latin America |
Brazil |
47.00 |
|
Middle East & Africa |
Saudi Arabia |
27.00 |
Europe Ostomy Care and Accessories Market Insights
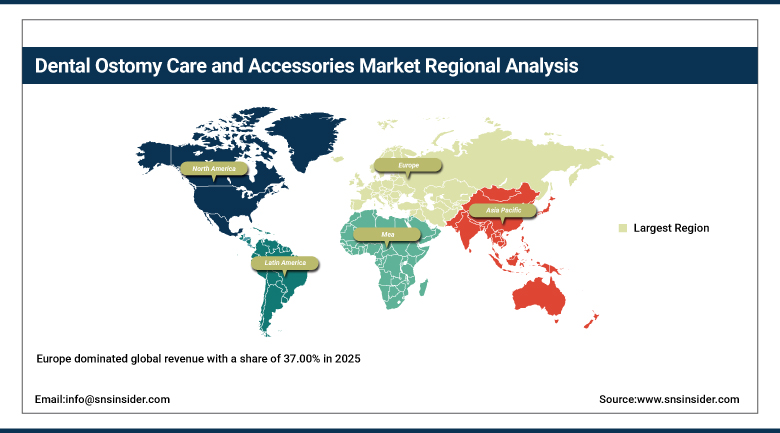
Europe dominated revenue with a share of 37.00% in 2025. Germany, the United Kingdom, France, Italy and Spain lead regional demand. Coloplast, Convatec, Hollister, Dansac, B. Braun, Salts Healthcare, Welland Medical and Eakin supply the region, where several leading manufacturers are headquartered. Public health systems in many countries run national procurement schemes, and supplier performance on service and delivery is monitored closely. Cross-border companies compete on both product range and nurse training programs.
National health systems reimburse ostomy supplies, and specialist stoma nurses guide product choice, which supports high use of modern products. Aging populations and colorectal screening programs sustain demand. Price controls, tender-based purchasing and slow population growth moderate growth, though innovation in comfort and skin protection keeps patients upgrading. Research groups and nursing associations publish guidance on stoma care that shapes hospital protocols. Innovation clusters in Denmark and the United Kingdom keep the region at the center of product development for companies.
⮞In April, 2026, Birmingham-based Salts Healthcare announced a move from working through agents to a direct business model in Australia and New Zealand. To support the launch it introduced Confidence BE go, described as the first ostomy product with an interchangeable cover system, and said it now has offices and operations on all five continents.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Ostomy Care and Accessories Market Insights
North America is the second-largest region. The United States accounts for major share of regional demand, with Canada adding volume. Hollister, Coloplast, Convatec, B. Braun, 3M, Cymed, Nu-Hope and Marlen serve the region. Wide use of home delivery suppliers and large integrated health systems helps standardize care. Mexico provides manufacturing and a growing market, while Canada provincial programs fund supplies in different ways.
High rates of colorectal and bladder surgery, broad insurance coverage and a large home delivery supply industry support sales. Patients have access to specialist nurses and a wide choice of convex and flexible products. Reimbursement scrutiny, competition among suppliers and cost pressure from payers moderate growth, but use of accessories and new-generation barriers continues to rise. Patient advocacy groups, such as ostomy associations, provide peer support and information, and this community helps sustain demand for new products and accessories among experienced users.
Asia Pacific Ostomy Care and Accessories Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 7.80% during 2026-2035. Japan, China, India, South Korea and Australia lead regional demand. Coloplast, Convatec, Hollister, Alcare, Salts Healthcare and local manufacturers are among the companies serving the region. Japan, South Korea and Australia have established reimbursement, while China and India are building supply chains and nurse education. Local firms are entering with lower-priced pouches and basic accessories. Awareness campaigns by patient groups and surgeons are slowly improving acceptance of stoma care in the region.
Rising rates of colorectal cancer, growing hospital capacity and increasing awareness of stoma care are lifting use of modern products. Japan has a mature market with strong reimbursement, while India and China are expanding as surgical volumes rise. Limited reimbursement, price sensitivity and few trained stoma nurses moderate growth, though patient support groups are growing. Hospitals in large cities are adding stoma clinics and training enterostomal therapists, which raises awareness. Multinational firms are partnering with distributors to reach regional hospitals and community pharmacies.
MEA & Latin America Ostomy Care and Accessories Market Insights
In Latin America, Brazil leads, followed by Mexico, Argentina, Colombia and Costa Rica. Public health programs and private insurers fund supplies in some countries, while out-of-pocket purchases are common elsewhere. Manufacturers are building regional supply networks and local production to improve access. Brazil and Mexico anchor regional sales, and regional distributors play a major role. Local manufacturing in Costa Rica has supported supply for several countries in Latin America. Public tenders and donations from international charities also supply products in lower-income countries.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, South Africa and Egypt lead demand. Rising surgical capacity and private hospital growth support demand, while limited reimbursement, supply gaps and few stoma nurses restrain adoption across much of Africa. Gulf countries invest in specialized surgical centers and offer wider coverage, while other markets depend on donations and imported supplies. Training nurses is a priority for improving outcomes across the region. Sterile processing, distribution and customs delays can raise delivery times for imported supplies.
Market Dynamics
Growth Drivers: Colorectal Disease, Aging Populations and Better Products
Rising rates of colorectal cancer, inflammatory bowel disease and bladder conditions lead to more stoma surgeries, especially among older adults. Screening programs for colorectal cancer also find disease earlier, and surgery is often followed by years of stoma care. Growth in ambulatory and day surgery also shortens hospital stays and moves stoma education into outpatient and home care settings, where manufacturers provide training materials and nurse hotlines for new users.
Comfortable, leak-resistant products and stronger nurse support encourage patients to use ostomy care consistently and to try accessories. Greater public openness about stoma life is also reducing stigma and encouraging active use. Product designs that reduce leaks and skin damage increase confidence, helping users return to work, travel and exercise sooner, which supports longer and more frequent use of modern systems.
Restraints: Reimbursement Limits, Skin Complications and Social Stigma
Reimbursement caps and tender pricing limit revenue per patient, and many regions lack coverage for accessories. Rapid changes in reimbursement rules in some countries can reduce margins for suppliers. Cost-containment in public systems can also push patients toward basic products even when advanced products might reduce complications and nursing time over the longer term.
Skin irritation, leaks and embarrassment can reduce confidence, and a shortage of stoma nurses limits education in many countries. Competition from lower-priced pouches also limits pricing power for premium brands. Lack of awareness among general practitioners about modern ostomy products can also delay referrals to specialist nurses and result in less optimal product choices for new patients.
Opportunities: Emerging Markets, Digital Support and Direct-to-Patient Supply
Growing surgical capacity in Asia Pacific, Latin America and the Middle East creates new users, and local production lowers prices. Coverage for accessories is expanding in some markets, which would raise average spending per patient. Partnerships with hospitals, insurers and nurse associations can help manufacturers create evidence of cost savings from better products and fewer complications, which supports wider coverage.
Apps, telehealth and home delivery services can improve adherence and give manufacturers direct relationships with patients. Data from digital tools can also help firms refine product design and improve outcomes. Sustainable materials, recyclable packaging and lower-waste designs are also an emerging opportunity as health systems and consumers look to reduce the environmental impact of disposable products.
Recent Developments:
- In August 2026, Convatec reported that its Esteem Body ostomy range had reached annualized revenue of about USD 60.00 million, and said Natura Body is on track for launch in 2027.
- In July 2026, Coloplast reported nine-month Ostomy Care organic growth of 5%, with strong U.S. growth and a SenSura Mio black bags launch ahead of forecast.
- In April 2026, Salts Healthcare moved to a direct business model in Australia and New Zealand and introduced Confidence BE go.
Ostomy Care and Accessories Market Key Players are:
- Coloplast A/S
- Hollister Incorporated
- Convatec Group plc
- B. Braun Melsungen AG
- Welland Medical Ltd.
- Salts Healthcare Ltd.
- Dansac A/S
- Marlen Manufacturing & Development Co.
- Nu-Hope Laboratories, Inc.
- Cymed Micro Skin
- Torbot Group, Inc.
- 3M Company
- Smith+Nephew plc
- Cardinal Health, Inc.
- Medline Industries, LP
- Eakin Healthcare Group
- Alcare Co., Ltd.
- Trio Healthcare Ltd.
- Genairex, Inc.
- Pelican Healthcare Ltd.
Ostomy Care and Accessories Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.93 Billion |
| Market Size by 2035 | USD 6.93 Billion |
| CAGR | CAGR of 5.84% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Ostomy Bags and Pouching Systems, and Ostomy Accessories) • By Application (Colostomy, Ileostomy, and Urostomy) • By End User (Hospitals and Clinics, Home Care Settings, and Others) • By Distribution Channel (Retail Pharmacies, Hospital Pharmacies, and Online Channels) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Coloplast A/S; Hollister Incorporated; Convatec Group plc; B. Braun Melsungen AG; Welland Medical Ltd.; Salts Healthcare Ltd.; Dansac A/S; Marlen Manufacturing & Development Co.; Nu-Hope Laboratories, Inc.; Cymed Micro Skin; Torbot Group, Inc.; 3M Company; Smith+Nephew plc; Cardinal Health, Inc.; Medline Industries, LP; Eakin Healthcare Group; Alcare Co., Ltd.; Trio Healthcare Ltd.; Genairex, Inc.; Pelican Healthcare Ltd. |

Frequently Asked Questions
Key players include Coloplast A/S, Hollister Incorporated, Convatec Group plc, B. Braun Melsungen AG, Welland Medical Ltd., Salts Healthcare Ltd., Dansac A/S and 3M Company.
Key opportunities include expanding surgical capacity in emerging markets, digital support tools and direct-to-patient supply models.
The major growth factor is the rising number of colorectal and bladder surgeries linked to disease and aging populations.
By Product, the Ostomy Bags and Pouching Systems segment dominated the market in 2025 with an estimated 78.00% share, supported by frequent repeat purchases.
Europe dominated the market with a share of 37.00% in 2025, driven by national reimbursement, specialist nurses and the presence of leading manufacturers.
