
Digital Health Market Report Scope & Overview:
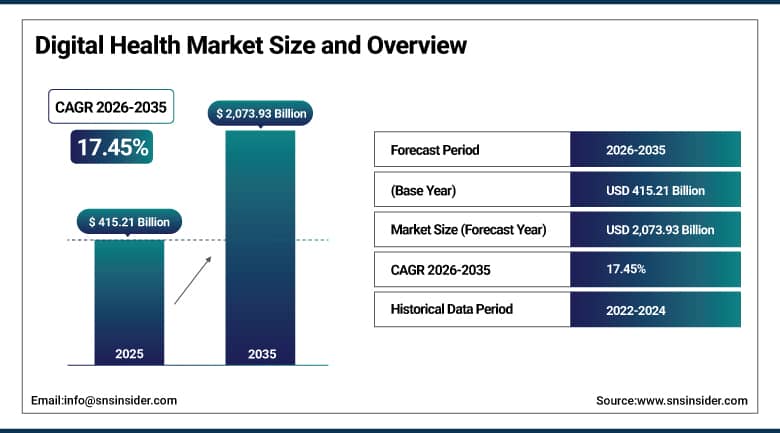
The Digital Health Market was valued at USD 415.21 Billion in 2025 and is expected to reach USD 2,073.93 Billion by 2035, growing at a CAGR of 17.45% from 2026-2035.
The Digital Health Market covers software, devices and services that deliver care, track health and manage medical data through digital channels. It includes telehealth, mobile health apps, electronic health records, wearables, remote monitoring and analytics. Health systems use these tools to widen access and reduce workloads, while consumers use them to manage conditions at home. Artificial intelligence is now built into documentation, imaging and patient messaging. Governments are funding national health apps and data exchange to connect care.
⮞In May 2025, the World Health Organization reported that 129 countries have national digital health strategies, as the World Health Assembly extended the Global Strategy on Digital Health to 2027. National plans are a strong base for investment in digital care.
To Get More Information On Digital Health Market - Request Free Sample Report
Digital Health Market Trends:
-
AI assistants for clinical documentation, coding and patient messaging
-
Remote monitoring and connected wearables for chronic conditions
-
Hybrid virtual and in-person care models
-
National health apps and patient portals
-
Mergers among digital therapeutics, mental health and musculoskeletal care providers
U.S. Digital Health Market Outlook:
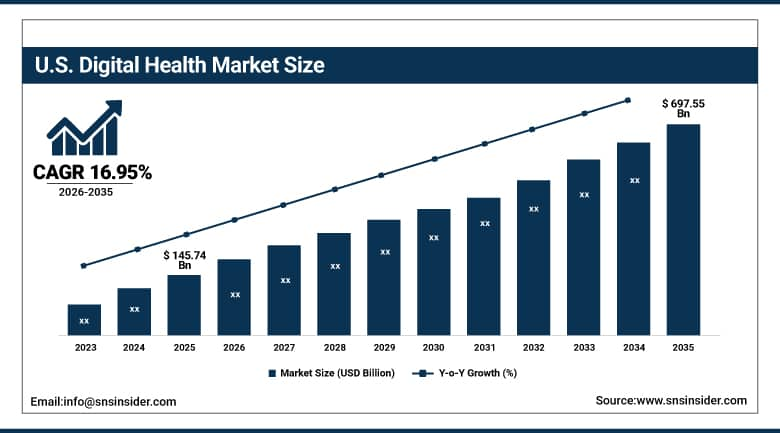
The U.S. Digital Health Market was valued at USD 145.74 Billion in 2025 and is expected to reach USD 697.55 Billion by 2035, growing at a CAGR of 16.95% from 2026-2035.
The U.S. Digital Health Market is the largest national market, supported by widespread electronic health record use, payer coverage for virtual care and a deep base of technology companies. Hospitals are adopting AI tools to reduce paperwork, and employers pay for digital programs for diabetes, musculoskeletal pain and mental health. Federal programs are pushing app-based data sharing. Privacy risks and uneven reimbursement slow some programs.
⮞In April 2026, the Centers for Medicare and Medicaid Services showed that more than 50 companies demonstrated patient-facing apps under its HealthTech Ecosystem, as reported by the American Hospital Association. A Medicare App Library was announced in February 2026.
Digital Health Market Segment Analysis:
-
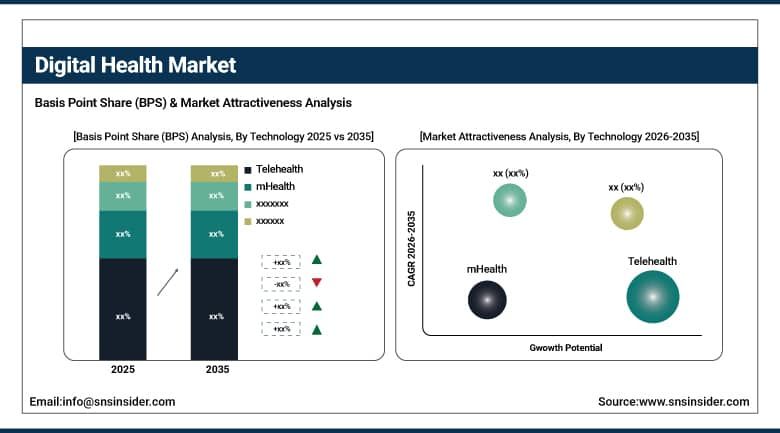
By Technology, the Telehealth segment dominated the Digital Health Market with approximately 43.86% share in 2025, while the mHealth segment is the fastest growing with a CAGR of approximately 18.22%.
-
By Component, the Services segment dominated the Digital Health Market with approximately 52.15% share in 2025, while the Software segment is the fastest growing with a CAGR of approximately 18.34%.
-
By End User, the Patients and Consumers segment dominated the Digital Health Market with approximately 38.66% share in 2025, while the Payers segment is the fastest growing with a CAGR of approximately 17.95%.
-
By Application, the Diabetes segment dominated the Digital Health Market with approximately 25.00% share in 2025, while the Mental Health segment is the fastest growing with a CAGR of approximately 19.45%.
By Technology, Telehealth Dominates the Digital Health Market and mHealth Grows Fastest
Telehealth leads because video visits, remote consultations and virtual follow-ups are now part of routine care. Providers use them to widen access, reduce travel and manage capacity, and payers cover many visit types. Employers and health systems have built permanent virtual programs. Behavioral health, dermatology, primary care and chronic condition follow-up now account for a large share of remote encounters.
mHealth grows fastest as smartphone apps move from tracking to treatment. Patients use apps for medication reminders, symptom logs, coaching and digital therapy, and clinicians receive the data. Wearable sensors connected to phones add to the stream of data and engagement. App stores, device makers and health systems are creating clinically supervised app libraries that physicians can prescribe.
⮞In September 2026, the U.S. Food and Drug Administration list of AI-enabled medical devices reached 1,614 entries, with 335 decisions in 2025, the most of any year. Regulatory clearance of AI-enabled devices is widening what digital tools can do.
By Component, Services Dominates the Digital Health Market and Software Grows Fastest
Services lead because implementation, integration, virtual care delivery, coaching and managed programs make up most of the spending. Health systems rely on partners to deploy platforms and train staff, and recurring service contracts are common. Clinical staff time delivered virtually adds to this base. Cybersecurity, data migration and change management projects also sit within service budgets.
Software grows fastest as clinical documentation, scheduling, population health and patient engagement platforms spread. AI features such as note generation and chart review are being added to existing systems, and cloud delivery speeds rollout. Interoperability rules push providers to upgrade older tools. Subscription pricing lowers upfront costs and allows smaller clinics to adopt tools that were once limited to large hospitals.
⮞In September 2025, the Office of the National Coordinator for Health IT reported that 71% of non-federal acute care hospitals used predictive AI integrated with their electronic health record in 2024, up from 66% in 2023. Hospital software use is growing quickly.
By End User, Patients and Consumers Dominates the Digital Health Market and Payers Grows Fastest
Patients and consumers lead because individuals buy and use apps, devices, virtual visits and subscription programs directly. Online health information is now a normal first step, and wearables and home tests put data in the hands of users. Convenience and cost drive repeat use. Direct-to-consumer prescribing, home testing and subscription weight-management programs have widened the consumer base.
Payers grow fastest as insurers and employers fund digital programs to lower claim costs and improve outcomes. They use virtual care, remote monitoring, care navigation and analytics to manage high-cost conditions. Value-based contracts and member engagement goals support further spending. Payers also use claims data and predictive models to identify members who would benefit from outreach.
⮞In April 2026, Eurostat reported that 54% of EU individuals searched online for physical health information in 2025, according to Sigmalive. High online health use supports consumer-led digital health.
By Application, Diabetes Dominates the Digital Health Market and Mental Health Grows Fastest
Diabetes leads because the condition needs daily monitoring, medication changes and lifestyle coaching, which suit digital tools. Continuous glucose monitors, connected insulin devices and coaching apps are widely covered. Large patient numbers create steady demand for remote programs. Employers and insurers increasingly cover digital diabetes prevention programs for people with elevated blood sugar.
Mental health grows fastest as shortages of clinicians and long waiting times push people toward app-based therapy, virtual counseling and digital coaching. Employers and insurers are adding behavioral health benefits, and stigma is lower when care is accessed privately on a phone. Digital programs also cover anxiety, sleep and substance use, expanding the addressable population.
⮞In September 2026, the U.S. Centers for Disease Control and Prevention stated that about 40.1 million people in the United States, or 12.0%, have diabetes, based on 2023 estimates. The size of the patient group sustains demand for digital management.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
90.00 |
|
Europe |
Germany |
22.00 |
|
Asia Pacific |
China |
36.00 |
|
Latin America |
Brazil |
42.00 |
|
Middle East & Africa |
Saudi Arabia |
24.00 |
North America Digital Health Market Insights
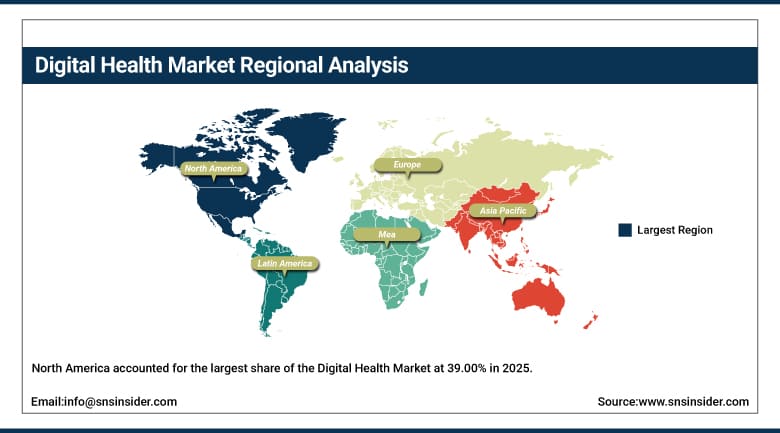
North America accounted for the largest share of the Digital Health Market at 39.00% in 2025, led by the United States and followed by Canada. The region has high electronic health record use, wide payer coverage of virtual care and a deep base of digital health companies. California, Massachusetts, New York and Texas host the largest clusters of start-ups and health system innovation units.
Hospitals are rolling out AI documentation and patient messaging, and employers pay for chronic care and mental health programs. Privacy and security risks and uneven reimbursement limit some programs. Canada is expanding provincial virtual care and electronic record access, though interoperability between provinces remains uneven.
⮞In June 2026, the U.S. Department of Health and Human Services breach portal showed 772 healthcare data breaches of 500 or more records in 2025, a record, affecting 139.7 million people, according to HIPAA Journal. Security is a growing priority for digital health buyers.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Digital Health Market Insights
In 2025, Europe represented around 25.00% of the Digital Health Market share, which includes Germany, the United Kingdom, France, Italy, and Spain. The health care systems within these countries finance their digital initiatives, and the European Health Data Space initiative establishes standards for interoperable data exchanges. The Nordic countries are among those that utilize their digital services the most by their citizens, while the Netherlands and Spain scale remote monitoring efforts.
The German government pays for prescribed health apps, and the United Kingdom has its national app. The diversity in regulations on data sharing and procurement between these countries hinders the process of international market expansion. Strict medical devices and artificial intelligence laws increase the requirements for the scientific proof of the product's efficiency.
⮞In February 2026, the European Commission eHealth indicator study reported that EU average access to electronic health records reached 83% in 2024, up from 72% in 2022, according to Euronews. Patient access is widening quickly.
Asia Pacific Digital Health Market Insights
Asia Pacific held about 22.00% of the Digital Health Market in 2025 and is projected to be the fastest growing region, at a CAGR of 18.62% over 2026-2035. China, India, Japan, South Korea and Australia lead, supported by large populations and high smartphone use. Singapore, Australia and South Korea have mature telehealth frameworks, and Japan is expanding online consultations for aging patients.
Governments are building digital identity and health record systems, and super-apps connect consultations, pharmacy and insurance. Rural access gaps and different standards across countries restrain some growth. Local language support and integration with insurance schemes are key factors for vendors entering these markets.
⮞In May 2026, India's National Health Authority reported that more than 90 crore ABHA health IDs had been created under the Ayushman Bharat Digital Mission, with 49.75% held by women. A national health ID base supports digital records and care.
MEA & Latin America Digital Health Market Insights
Latin America and the Middle East and Africa together hold about 14.00% of the Digital Health Market. In Latin America, Brazil, Mexico, Argentina and Colombia lead, using telemedicine to reach remote areas and expanding national electronic records. Mexico and Chile are also introducing electronic prescription and telehealth rules.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Qatar and South Africa lead. Gulf states fund virtual hospitals and national platforms, while connectivity and funding gaps limit progress in much of Africa. Mobile-based services are helping to bridge access gaps in Kenya, Nigeria and South Africa.
⮞In January 2026, Saudi Arabia's Ministry of Health reported that its Seha Virtual Hospital delivered more than 16 million virtual appointments and consultations in 2025. Large public virtual care programs are expanding in the Gulf.
Market Dynamics:
Growth Drivers: Connectivity Growth and Health System Digitization Drive Growth in the Digital Health Market
The first trend is growth of connectivity. Increased usage of smartphones, mobile broadband, and 5G network provides people with more opportunities to utilize apps, video calls and connected devices. Communities which lack specialist access can use virtual care technology now and cloud delivery reduces cost of access for providers. Cheaper devices and data plans make this kind of services affordable for more people.
Digitization of healthcare sector provides additional momentum. Due to staff shortage and increasing workload, hospitals use AI technologies for documentation, remote monitoring and scheduling to reduce work load for clinicians. Electronic records, interoperability standards and health apps funded by governments serve as a basis for new services. Remote monitoring coding reimbursement serves as a financial motivator for providers to grow.
⮞In November 2025, the International Telecommunication Union reported that almost three-quarters of the world's population is online and 5G covers more than half of the global population. Wider connectivity increases reach for digital health.
Restraints: Data Security Risks and Low Digital Health Literacy Restrain Growth in the Digital Health Market
Data security concerns pose constraints to growth. Medical records are of great importance for attackers, and the breaches may affect millions of patients while costing time and trust to providers. Privacy compliance varies in different countries, which means higher costs and a slower process of cross-country product development. Ransomware attacks on hospitals affect appointment scheduling and make boards careful about adopting new vendors.
Low digital health literacy poses another constraint. Elderly and poorer patients have difficulties with using mobile apps, portals, and remote devices, thus limiting the adoption of such tools. Doctors also require education in this matter, while poor integration with current IT infrastructure increases workloads of clinicians. Poorly adjusted tools lead to alert fatigue.
⮞In 2025, the OECD Health at a Glance report found digital health literacy among primary care users aged 45 and over in 17 mostly European countries was 26% for the higher educated and 18% for the lower educated, according to Euronews. Skills gaps limit patient use.
Opportunities: AI-Enabled Care and National Health Apps Create Opportunities in the Digital Health Market
AI-enabled care offers a major opportunity. Tools that write clinical notes, triage messages, read images and flag risks can lower costs and improve access. Vendors that prove safety and fit into existing workflows can scale across large health systems and insurers. Ambient listening tools already show that documentation time can be reduced, which opens the door to wider clinical use.
National health apps offer further potential. Governments are turning patient portals into daily-use platforms for booking, records, prescriptions and prevention. These platforms create a channel for third-party services and give vendors access to large user bases. Integration of wearable data, vaccination records and test results can turn these apps into personal health hubs.
⮞In December 2025, NHS England reported more than 39 million registered NHS App users and 62.3 million logins in November 2025. Large national platforms show the scale possible for public digital health channels.
Recent Developments:
-
In August 2026, Sword Health agreed to acquire Headspace through its parent OrangeDot in a cash deal, with the price undisclosed. The move links physical therapy and mental health care on one platform.
-
In March 2026, Amazon expanded its Health AI agent beyond One Medical members to a wider U.S. audience. Prime members also receive five free virtual consultations.
-
In September 2025, Apple received U.S. FDA clearance for hypertension notifications on Apple Watch. The feature was trained on more than 100,000 participants and is planned for more than 150 countries.
Digital Health Market Key Players:
-
Hinge Health, Inc.
-
Hims & Hers Health, Inc.
-
Omada Health, Inc.
-
Doximity, Inc.
-
Veeva Systems Inc.
-
Dexcom, Inc.
-
Sword Health, Inc.
-
Oracle Health (Oracle Corporation)
-
Microsoft Corporation
-
Amazon.com, Inc. (One Medical)
-
Apple Inc.
-
American Well Corporation (Amwell)
-
Teladoc Health, Inc.
-
Epic Systems Corporation
-
GE HealthCare Technologies Inc.
Digital Health Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 415.21 Billion |
| Market Size by 2035 | USD 2,073.93 Billion |
| CAGR | CAGR of 17.45% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Telehealth, mHealth, Digital Health Systems, and Health Analytics) • By Component (Services, Software, and Hardware) • By End User (Patients and Consumers, Providers, Payers, and Others) • By Application (Diabetes, Cardiovascular Disease, Mental Health, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Hinge Health, Inc., Hims & Hers Health, Inc., Omada Health, Inc., Doximity, Inc., Veeva Systems Inc., Dexcom, Inc., Sword Health, Inc., Oracle Health (Oracle Corporation), Microsoft Corporation, Amazon.com, Inc. (One Medical), Apple Inc., American Well Corporation (Amwell), Teladoc Health, Inc., Epic Systems Corporation, GE HealthCare Technologies Inc. |

Frequently Asked Questions
Key players include Hinge Health, Hims & Hers Health, Omada Health, Doximity, Veeva Systems, Dexcom, Sword Health, Oracle Health, Microsoft, Amazon (One Medical), Apple, Amwell, Teladoc Health, Epic Systems and GE HealthCare.
Key opportunities include AI-enabled care, national health apps, remote monitoring for chronic disease and fast-growing Asia Pacific demand.
Wider connectivity and the digitization of health systems, driven by staff shortages and government programs, are the main growth factors.
By Technology, the Telehealth segment dominated the market in 2025 with an estimated 43.86% share, supported by routine use of virtual visits.
North America dominated the market with a share of 39.00% in 2025, driven by high electronic record use and payer coverage of virtual care.
