
Parental Control Software Market Report Scope & Overview:
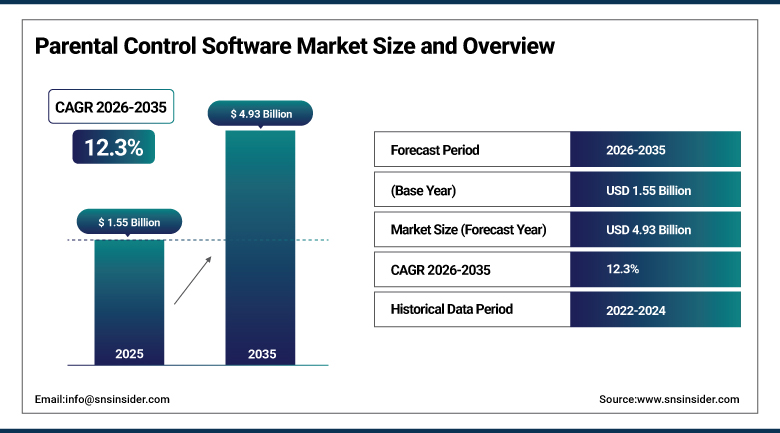
The Parental Control Software Market was valued at USD 1.55 billion in 2025 and is projected to reach USD 4.93 billion by 2035, expanding at a CAGR of 12.3% during the forecast period.
Parental control software enables parents to keep tabs on the activities of their kids online, restricting them from visiting harmful websites, imposing limitations on screen time, and controlling their devices' usage including smartphones, tablets, desktops, and now even smart TVs and gaming consoles. The increasing popularity of smartphone use among children and adolescents, often starting at younger age levels, has increased screen time on an average basis and further spurred the need for parents to have tools that monitor their children online. Increased worries about cybersecurity have driven the need for such tools.
The use of solutions that sync up the settings on all iOS, Android, and Windows platforms under one interface remains very popular among the parents trying to coordinate the children's activities on different kinds of devices and, thus, decrease the difficulty of providing the same kind of safety policy for all devices. The emergence of remote and hybrid education leads to the growth in the number of devices used for learning from home. Therefore, cross-platform applications need to be able to regulate both educational and recreational use within the limits of the single family account. Now the providers of these services tend to focus their marketing on the formation of good family digital practices and discussions about the use of screens rather than the control itself, according to the changing recommendations of experts in this field. This trend is especially noticeable in the targeted marketing among teenagers themselves when the providers try to sell the collaborative family agreement feature rather than the parental restrictions one.
Industry research indicates that nearly 53% of teenagers are now aware of methods to disable or evade parental control software features, with around 47% reportedly using VPNs or proxy servers to bypass restricted content controls, underscoring the ongoing technology arms race between monitoring software providers and increasingly tech-savvy younger users.
To Get more information Parental Control Software Market - Request Free Sample Report
Parental Control Software Market Market Trends
-
Rising adoption of cross-platform solutions synchronizing controls across iOS, Android, and Windows devices
-
Growing integration of AI-based content filtering to detect evolving forms of inappropriate or harmful content
-
Increasing demand for smart TV and gaming console monitoring as children's screen time diversifies beyond mobile devices
-
Rising parental interest in social media and messaging app monitoring amid growing cyberbullying concerns
-
Growing adoption of tiered, subscription-based pricing models expanding access to middle and lower-income households
U.S. Parental Control Software Market Outlook
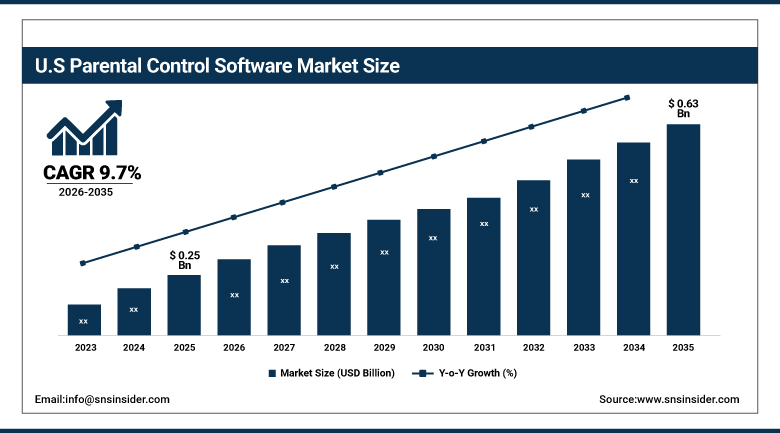
The U.S. parental control software market was valued at USD 0.25 billion in 2025 and is projected to reach USD 0.63 billion by 2035, growing at a CAGR of 9.7% during 2026-2035.
The U.S. market benefits from high smartphone penetration among children and teenagers alongside strong parental awareness of online safety risks, with cloud-based deployment now representing the substantial majority of the domestic market given its scalability, remote accessibility, and simplified software management relative to on-premises alternatives. Residential use continues to dominate U.S. demand, reflecting the market's primary orientation toward individual family device management rather than institutional deployment.
Android phone usage continues to underpin demand in the U.S. operating systems subsegment, owing to the high market presence of Android phones that are commonly used by children, while the parental control software targeting Apple devices is also expected to gain due to the strong penetration of Apple among teenage users. Increasing adoption of device management solutions among school districts on the back of growing one-to-one computing initiatives in K-12 schools is set to drive demand as an additional institutional channel for sales, in addition to regular sales into households.
In recent years, the shift towards remote and hybrid learning in U.S. school districts has led to an increasing need for device oversight by parents at home, where cross-platform solutions enable parents to reconcile device use for education and entertainment within one monitoring solution.
Parental Control Software Market Segment Analysis
-
By Device Type, the Mobile (Smartphones & Tablets) segment dominated the Parental Control Software Market with approximately 55.4% share in 2025, while the Smart TV & Gaming Consoles segment is the fastest growing with a CAGR of approximately 16.8%.
-
By Operating System, the Android segment dominated the Parental Control Software Market with approximately 33.0% share in 2025, while the iOS segment is the fastest growing with a CAGR of approximately 14.2%.
-
By Application, the Residential segment dominated the Parental Control Software Market with approximately 71.6% share in 2025, while the Educational Institutions segment is the fastest growing with a CAGR of approximately 15.4%.
By Device Type, Mobile (Smartphones & Tablets) Dominates the Parental Control Software Market While Smart TV & Gaming Consoles Register the Fastest Growth
Mobile (Smartphones & Tablets) was the dominant segment in the Parental Control Software Market for 2025 as a result of the increasing adoption rate of smartphones by children and teenagers beginning from a much earlier age, with children and teenagers using these devices for both accessing the internet and socializing, thus making mobile monitoring the core use case for the purchase of most parental control software.
The Smart TV & Gaming Consoles segment is expected to have the highest growth rate in the Parental Control Software Market as a result of children spending more time on screens that go beyond the traditional mobile devices into connected media and gaming devices in the smart home.
By Operating System, Android Dominates the Parental Control Software Market While iOS Registers the Fastest Growth
Android dominated the Parental Control Software Market in 2025 due to the fact that broad Android device adoption and strong mobile ecosystem penetration, particularly among budget and mid-range smartphones frequently purchased for younger children, give this operating system the largest addressable installed base for parental control software deployment globally.
iOS is the fastest-growing segment in the Parental Control Software Market due to the fact that growing iPhone penetration among teenagers and rising parental willingness to pay premium subscription pricing for iOS-focused monitoring tools continue to expand this segment, supported by Apple's own expanding native Screen Time and Family Sharing ecosystem that increasingly integrates with third-party monitoring software.
By Application, Residential Dominates the Parental Control Software Market While Educational Institutions Register the Fastest Growth
Residential dominated the Parental Control Software Market in 2025 due to the fact that individual family device management remains the primary and most established use case for parental control software, driven by direct parental purchasing decisions rather than institutional procurement processes.
Educational Institutions is the fastest-growing segment in the Parental Control Software Market due to the fact that the rise of remote and hybrid learning models has significantly increased the number of school-issued devices requiring content filtering and usage monitoring, prompting schools and districts to adopt device management software at a pace outstripping residential market growth.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.0% |
|
Europe |
United Kingdom |
26.0% |
|
Asia Pacific |
India |
34.0% |
|
Middle East & Africa |
UAE |
27.0% |
|
Latin America |
Brazil |
36.0% |
North America Parental Control Software Market Insights
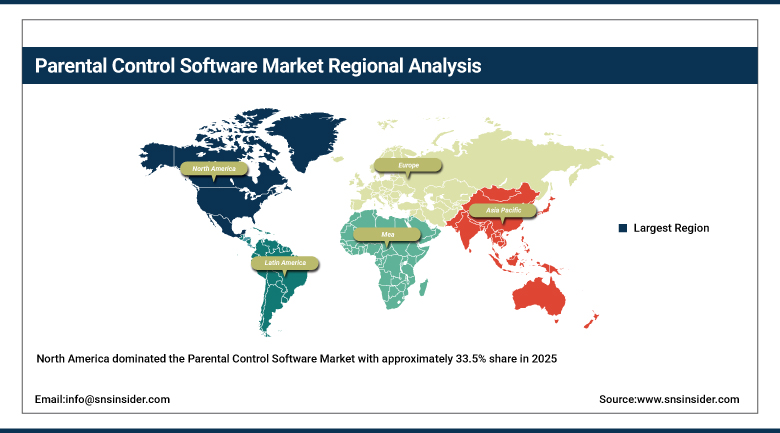
North America dominated the Parental Control Software Market with approximately 33.5% share in 2025, supported by high smartphone and connected device penetration among children combined with strong parental awareness of online safety risks and cyberbullying concerns. Canadian parental control software adoption continues to expand alongside similar U.S. trends, with growing school district interest in device management software supporting hybrid and remote learning programs across the country.
Mexican parental control software demand continues to grow alongside broader North American smartphone penetration trends, though the market remains smaller in scale relative to the deeply established U.S. residential and institutional demand base.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Parental Control Software Market Insights
Europe's market is supported by strong regulatory attention to child online safety, including the UK's Online Safety Act and EU-level digital services regulation, which continue to raise parental and institutional awareness of the need for active content monitoring and device management tools.
German and French parents continue to show strong interest in privacy-conscious monitoring solutions that comply with strict EU data protection requirements, favoring providers able to clearly demonstrate GDPR-compliant data handling practices for children's online activity data.
Asia Pacific Parental Control Software Market Insights
The Asia Pacific region has been identified as the most rapidly growing region for the Parental Control Software Market due to factors such as rising smartphone adoption among children in India and China and parental concerns regarding the dangers on the internet. The adoption of parental control software continues to increase in India due to rising smartphone penetration among school-going children in urban as well as rural settings, while parental control software adoption in China is influenced by the purchasing behavior of the parent as well as national laws regarding internet use among youth.
Parental control software adoption continues to rise in South Korea and Japan due to high penetration of smartphones among children as well as cultural preference for organized screen time management.
Middle East & Africa and Latin America Parental Control Software Market Insights
The Middle East & Africa region is growing steadily as Gulf state parents increasingly adopt parental control software amid rising smartphone and tablet ownership among children, supported by growing regional awareness campaigns around online child safety. South African and Nigerian parental control software adoption remains at an earlier stage relative to Gulf state markets, though rising smartphone penetration among urban school-age children is gradually expanding the addressable market across the continent.
Latin America is growing steadily as Brazilian and Mexican smartphone penetration among children continues to expand, driving growing parental interest in both free and premium subscription-based monitoring solutions across the region's largest economies. Argentine and Colombian parents continue to show growing interest in free and entry-level paid monitoring tools, reflecting broader regional price sensitivity relative to more premium-oriented North American and European market segments.
Market Dynamics
Growth Drivers: Rising smartphone penetration among children and growing online safety awareness
The ubiquitous adoption of smartphones and other devices among young people and children, starting from ever-younger ages, will further fuel the parental control software market as screen usage time increases in virtually all demographics and markets. Increasing parental awareness of threats such as inappropriate content and bullying on the internet will continue to fuel both acquisitions and upgrades among existing customers looking for more advanced monitoring capabilities. The growing prevalence of remote and hybrid learning is fueling the need for additional device oversight, leading to growth among residential and educational institutions segments that goes beyond the number of devices used for recreation.
Rising social media and messaging app usage among children continues to expand demand for monitoring tools capable of extending beyond basic web filtering into more sophisticated communication and social platform oversight. Growing school district and government attention to online child safety, including expanding regulatory requirements for content filtering on school-issued devices, continues to reinforce institutional demand for parental control and device management software beyond purely voluntary parental purchasing decisions.
Restraints: Teen circumvention tactics and limited parental digital literacy constraining effectiveness
The increasing consciousness of teens regarding the techniques of disabling or bypassing parental control software features, including the use of a Virtual Private Network (VPN) and proxies, continues to affect the efficiency of such tools, making it an arms race that necessitates software upgrades. The poor level of digital literacy of the majority of parents in many places remains to be a barrier to effective use of parental control software since a significant number of parents lack adequate knowledge of installation, configuration, and management of advanced monitoring software.
The recurring costs involved in using premium parental control software that offers advanced features make their use difficult especially for price-sensitive individuals and large families who would need to pay for the licensing of more than one device. Privacy concerns among some parents and child advocacy groups regarding the extent of monitoring and data collection practiced by certain parental control applications continue to create reputational and regulatory scrutiny risk for software providers, particularly in jurisdictions with strict children's data privacy regulations.
Opportunities: AI-based content detection and tiered pricing models widening addressable demand
Growing integration of AI-based content filtering presents a significant opportunity for software providers to more effectively detect evolving, harder-to-classify forms of inappropriate content that traditional keyword and category-based filtering increasingly struggles to identify. Development of more flexible, tiered subscription pricing models presents an opportunity for providers to expand adoption among middle and lower-income households currently underserved by premium-only pricing structures, broadening the addressable market beyond price-insensitive early adopters.
Expanding smart TV and gaming console monitoring capability presents an opportunity for providers to capture a growing share of children's diversifying screen time, extending beyond the traditionally mobile-and-computer-focused core parental control software market. Growing demand for parental control features embedded directly within broader family safety and location-sharing applications presents an opportunity for providers to expand beyond standalone monitoring software into more comprehensive family safety platform positioning. Growing demand among employers and commercial customers for device management software extending beyond family use into corporate-owned device oversight for minors in specific commercial contexts, such as youth sports and camp programs, presents a smaller but emerging niche opportunity for providers.
Recent Developments
-
In 2024, Qustodio expanded its cross-platform monitoring capability with enhanced social media and messaging app oversight features targeting parents of teenage children.
-
In 2024, Norton (Gen Digital) integrated expanded parental control features within its broader family safety software suite, targeting cross-selling opportunities among existing cybersecurity subscription customers.
-
In 2023, Google expanded its Family Link parental control application with additional screen time management and content filtering features for Android device users.
-
In 2024, Apple expanded native Screen Time and Family Sharing capability within iOS, increasing integration options for third-party parental control software providers building on top of the platform's native controls.
-
In 2023, Kaspersky Safe Kids expanded its device monitoring capability to include smart TV and gaming console platforms, targeting families seeking unified control across increasingly diverse household device ecosystems.
Parental Control Software Market key players are:
-
Qustodio
-
Bark Technologies
-
Gen Digital (Norton)
-
Kaspersky Lab
-
Google LLC (Family Link)
-
Apple Inc. (Screen Time)
-
Microsoft Corporation (Family Safety)
-
Net Nanny (Aura)
-
Circle Media Inc.
-
mSpy
-
FamiSafe (Wondershare)
-
OurPact
-
Screen Time Labs
-
McAfee Corp.
-
ESET spol. s r.o.
-
Boomerang Parental Control
-
Canopy
-
Bosco (Life360)
-
Life360 Inc.
-
Mobicip
Parental Control Software Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.55 Billion |
| Market Size by 2035 | USD 4.93 Billion |
| CAGR | CAGR of 12.3% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Device Type (Mobile (Smartphones & Tablets), Computer & Laptop, Smart TV & Gaming Consoles) • By Operating System (Android, iOS, Windows, Others) • By Application (Residential, Educational Institutions, Commercial) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Qustodio, Bark Technologies, Gen Digital (Norton), Kaspersky Lab, Google LLC (Family Link), Apple Inc. (Screen Time), Microsoft Corporation (Family Safety), Net Nanny (Aura), Circle Media Inc., mSpy, FamiSafe (Wondershare), OurPact, Screen Time Labs, McAfee Corp., ESET spol. s r.o., Boomerang Parental Control, Canopy, Bosco (Life360), Life360 Inc., Mobicip |
Frequently Asked Questions
Leading companies include Qustodio, Bark Technologies, Gen Digital (Norton), Kaspersky Lab, and Google LLC, among other dedicated family safety software specialists and broader cybersecurity vendors.
Opportunities include growing integration of AI-based content filtering for evolving harmful content, development of more flexible tiered subscription pricing models, and expanding smart TV and gaming console monitoring capability.
Growth is driven by near-ubiquitous smartphone adoption among children, growing parental awareness of online safety risks, expansion of remote and hybrid learning models, and rising social media and messaging app usage among children.
Mobile (Smartphones & Tablets) dominates by device type with approximately 55.4% share, Android dominates by operating system with roughly 33.0% share, and Residential dominates by application with about 71.6% share; Smart TV & Gaming Consoles, iOS, and Educational Institutions are the fastest-growing segments within their respective categories.
North America is the largest regional market with approximately 33.5% share, led by the United States, while Asia Pacific, led by India, is the fastest-growing region through 2035.
