
Risk-Based Monitoring Software Market Report Scope & Overview:
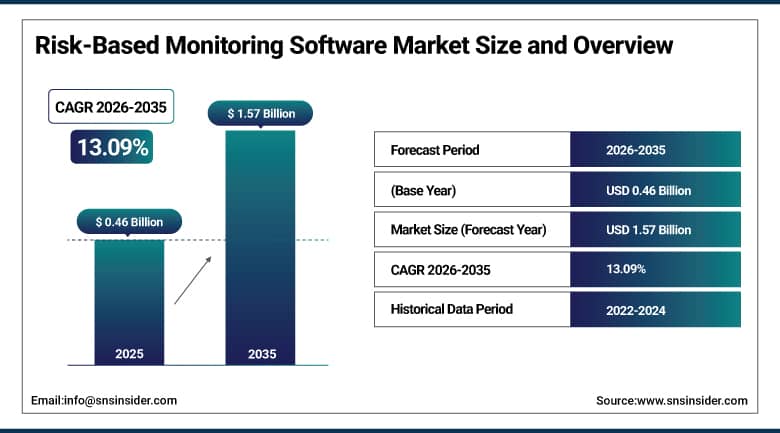
The Risk-Based Monitoring Software Market was valued at USD 0.46 Billion in 2025 and is expected to reach USD 1.57 Billion by 2035, growing at a CAGR of 13.09% from 2026-2035.
The Risk-Based Monitoring Software Market growth is driven by cost and inefficiency of conventional monitoring, risk-proportionate regulatory guidance, decentralized and hybrid trial designs, and growth in trial volume and outsourcing to contract research organizations. Risk-based monitoring software is becoming a core component of modern clinical trial oversight as sponsors, contract research organizations, academic research networks, and site management teams move from exhaustive source data verification toward targeted, data-driven quality management. The technology supports centralized monitoring, risk assessment, issue detection, protocol compliance tracking, and clinical data review across increasingly complex trial designs, including decentralized, hybrid, adaptive, and multi-country studies. The growing integration of artificial intelligence and machine learning algorithms represents transformative trends, as these technologies continue to enhance predictive risk identification and automate manual monitoring workflows.
In January 2025, CluePoints launched its Site Profile & Oversight Tool (SPOT) Version 1, a Best of Show finalist at the SCOPE 2025 clinical research conference, integrating data from clinical trial management systems, electronic data capture platforms, and centralized monitoring sources to quantify site risk levels and prioritize resource allocation. The tool circumvents rigid source data verification strategies, reduces unnecessary monitoring efforts, and estimates both a backlog and forecast of clinical research associate monitoring visit workload, reflecting the broader industry trend of established risk-based monitoring vendors continuing to develop increasingly sophisticated, multi-source data integration capability as sponsors seek to optimize monitoring resource allocation across increasingly complex clinical trial portfolios.
To Get More Information On Risk-Based Monitoring Software Market - Request Free Sample Report
Risk-Based Monitoring Software Market Trends
- Rising integration of artificial intelligence and machine learning algorithms enhancing predictive risk identification capability.
- Growing adoption of centralized statistical monitoring tools supporting operationalized risk-based quality management approaches.
- Expanding use of multi-source data integration combining CTMS, EDC, and centralized monitoring platforms into unified oversight tools.
- Increasing adoption of site-specific risk profiling tools optimizing clinical research associate monitoring visit allocation.
- Rising demand for risk-based monitoring capability supporting decentralized, hybrid, and adaptive clinical trial designs.
- Growing vendor competition around unified clinical data platforms combining data capture, cleaning, and risk-based oversight.
U.S. Risk-Based Monitoring Software Market Outlook
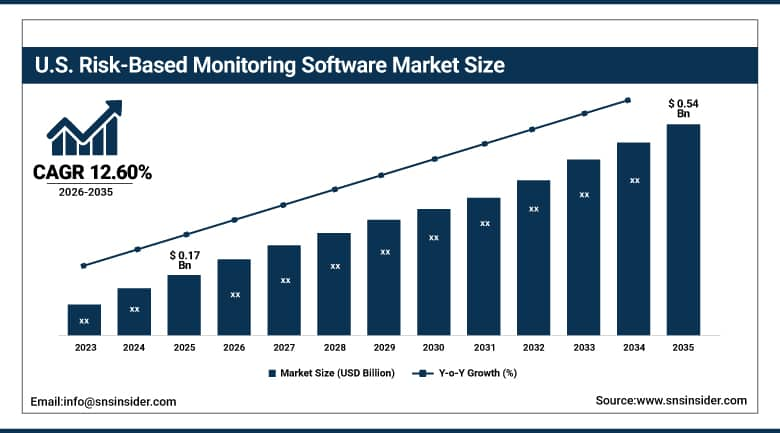
The U.S. Risk-Based Monitoring Software Market was valued at USD 0.17 Billion in 2025 and is expected to reach USD 0.54 Billion by 2035, growing at a CAGR of 12.60% from 2026-2035.
The U.S. Risk-Based Monitoring Software Market growth continues to be reinforced by the country's substantial concentration of pharmaceutical, biopharmaceutical, and contract research organization sponsors pursuing increasingly complex, multi-site clinical trial programs. Domestic clinical data leaders continue to prioritize technology initiatives combining risk-based checks with centralized monitoring capability, recognizing that eliminating manual, repetitive monitoring tasks across large trial portfolios can avoid tens of thousands of hours of clinical research associate work. Rising adoption of unified clinical data platforms, integrating electronic data capture, clinical trial management, and risk-based monitoring capability within single governed architectures, continues to reinforce domestic market demand. Growth is further supported by continued domestic vendor investment in AI-powered risk identification and multi-source data integration capability.
In April 2025, Veeva Systems announced Veeva SiteVault CTMS, a clinical trial management system specifically designed for research sites that integrates with SiteVault eISF and eConsent, offering bidirectional data flow between sponsors and sites to support risk-based oversight capability. The launch builds on Veeva Vault EDC's use in more than 1,000 clinical trials globally, including the migration of an entire core clinical trial portfolio for a top-20 biopharmaceutical company from a legacy electronic data capture provider, illustrating how established domestic clinical technology vendors continue to expand integrated, site-to-sponsor data flow capability supporting increasingly sophisticated risk-based monitoring approaches across the country's substantial clinical trial ecosystem.
Risk-Based Monitoring Software Market Segment Analysis
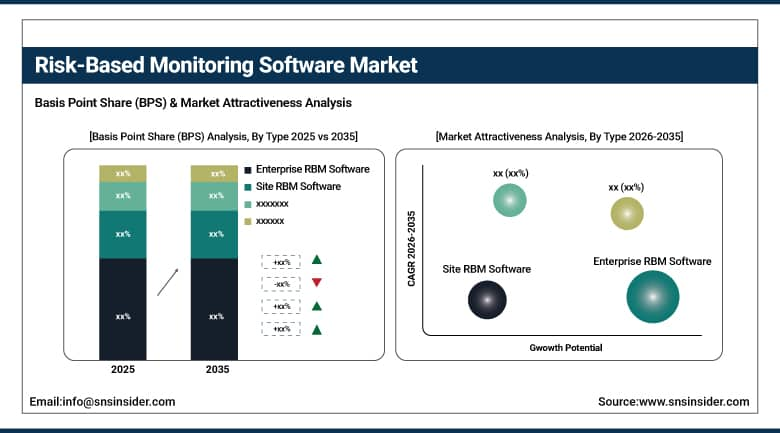
- By Type, the Enterprise RBM Software segment dominated the Risk-Based Monitoring Software Market with approximately 62.60% share in 2025, while the Site RBM Software segment is the fastest growing with a CAGR of approximately 14.20%.
- By Component, the Software segment dominated the Risk-Based Monitoring Software Market with approximately 64.60% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 14.60%.
- By Delivery Mode, the Cloud-Based segment dominated the Risk-Based Monitoring Software Market with approximately 55.60% share in 2025, and is also the fastest growing with a CAGR of approximately 14.80%.
- By End-User, the Pharmaceutical & Biopharmaceutical Companies segment dominated the Risk-Based Monitoring Software Market with approximately 46.60% share in 2025, while the Contract Research Organizations segment is the fastest growing with a CAGR of approximately 14.40%.
By Type, Enterprise RBM Software Dominates the Risk-Based Monitoring Software Market and Site RBM Software Grows Fastest
Enterprise RBM software dominates the market due to the fact that the procurement of RBM software on an enterprise-wide basis remains to be the most dominant model for procurement among pharmaceutical and biopharmaceutical companies, since it allows them to standardize the implementation of risk-based monitoring by deploying it within the entirety of their clinical trial portfolio. It is because of the benefits of enterprise-wide deployment that allow standardization and centralization of risk assessment and monitoring that this type of software is dominant in the industry.
Site RBM software is the fastest-growing type as clinical trial sites increasingly adopt dedicated risk-based monitoring and oversight tools capable of managing site-level risk profiles and monitoring visit prioritization independent of sponsor-provided enterprise systems. This growth is reinforced by rising site-level demand for tools capable of quantifying risk levels from centralized monitoring data and forecasting monitoring visit workload, positioning site RBM software as an increasingly important complement to enterprise-level systems as clinical trial sites pursue greater autonomy in managing their own oversight and compliance workflows.
By Component, Software Dominates the Risk-Based Monitoring Software Market and Services Grows Fastest
Software dominates the market as the core risk-based monitoring platform, encompassing centralized monitoring, risk assessment, issue detection, and protocol compliance tracking capability, represents the foundational technology that sponsors and contract research organizations license to support their clinical trial oversight programs. The breadth of functionality required across increasingly complex trial designs, including decentralized, hybrid, adaptive, and multi-country studies, continues to sustain software's position as the largest component category within the broader risk-based monitoring market.
Services are the fastest-growing component as sponsors and contract research organizations increasingly require specialized implementation, configuration, and consulting support to fully realize the value of increasingly sophisticated risk-based monitoring platforms. This growth is reinforced by the growing integration of artificial intelligence and machine learning algorithms into risk-based monitoring software, which continues to require specialized expertise to properly configure predictive risk models and integrate multiple data sources into unified oversight workflows.
By Delivery Mode, Cloud-Based Dominates the Risk-Based Monitoring Software Market and Also Grows Fastest
Cloud-based delivery dominates the market due to increased implementation of web-based and cloud-based risk-based monitoring solutions owing to their enhanced scalability, low maintenance costs, customizability, and easy integration with existing clinical trial technology ecosystems. Cloud-based delivery also helps improve productivity and enhance work efficiency, continuing to make it the preferred deployment approach for sponsors and contract research organizations managing increasingly distributed, multi-site clinical trial programs across global regions.
Cloud-based delivery is also the fastest-growing delivery mode as sponsors and contract research organizations increasingly prioritize deployment models offering rapid scalability and seamless integration with cloud-native clinical trial management, electronic data capture, and centralized monitoring platforms. This growth is reinforced by the broader clinical trial technology industry's continued shift toward cloud-native, integrated platform architectures, positioning cloud-based risk-based monitoring software to capture an increasing share of both new and replacement technology investment.
By End-User, Pharmaceutical & Biopharmaceutical Companies Dominates the Risk-Based Monitoring Software Market and Contract Research Organizations Grows Fastest
Pharmaceutical and biopharmaceutical companies dominate end-user demand as these organizations represent the primary sponsors of clinical trial programs and bear ultimate responsibility for trial oversight, data integrity, and regulatory compliance across their drug and biologic development portfolios. The scale of pharmaceutical and biopharmaceutical company clinical trial investment, spanning early-phase through pivotal registration trials, continues to sustain this end-user category's position as the largest source of risk-based monitoring software demand.
Contract research organizations are the fastest-growing end-user category as growth in trial volume and outsourcing to contract research organizations continues to expand demand for risk-based monitoring capability among these increasingly central clinical trial execution partners. This growth is reinforced by sponsors' continued preference for outsourcing complex, multi-site trial management to specialized contract research organizations, which in turn require sophisticated risk-based monitoring software to efficiently manage oversight responsibilities across an expanding portfolio of client trials.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.80% |
|
Europe |
Germany |
29.60% |
|
Asia Pacific |
China |
39.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Risk-Based Monitoring Software Market Insights
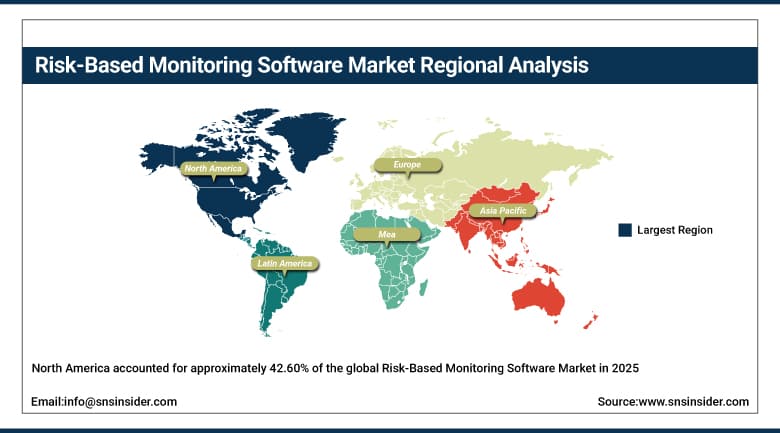
North America accounted for approximately 42.60% of the global Risk-Based Monitoring Software Market in 2025, making it the largest regional market, supported by the region's substantial concentration of pharmaceutical, biopharmaceutical, and contract research organization sponsors. The United States anchors regional demand, home to the majority of leading global pharmaceutical companies and clinical technology vendors continuing to invest heavily in AI-driven risk-based monitoring capability.
Canada is contributing incremental regional demand as its clinical research sector continues to expand. Continued domestic investment in unified clinical data platforms and multi-source data integration capability is expected to sustain North America's leading position through the forecast period, even as growth in percentage terms moderates relative to faster-expanding emerging markets pursuing rapid clinical trial infrastructure development.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Risk-Based Monitoring Software Market Insights
Asia Pacific is the fastest-growing regional market, expanding at a CAGR of approximately 14.60% from 2026 to 2035, making it a key focus area for market players looking to expand their presence given the region's rapidly growing clinical trial volume. China's expanding domestic pharmaceutical industry and growing clinical trial infrastructure continue to drive substantial regional demand for risk-based monitoring software adoption.
India is making a substantial contribution in terms of additional growth with the continued growth in its CRO segment, thanks to increasing activity of sponsor outsourcing from other countries. Japan and South Korea are making further contributions in terms of additional scale, owing to their well-established pharmaceutical sectors that are taking up risk-based monitoring capabilities.
Europe Risk-Based Monitoring Software Market Insights
Europe represents a significant share of the global Risk-Based Monitoring Software Market, anchored by Germany's large pharmaceutical industry and the region's established clinical research infrastructure. European Medicines Agency risk-proportionate regulatory guidance continues to reinforce regional adoption of risk-based monitoring approaches, as sponsors increasingly align trial oversight methodology with evolving regional regulatory expectations.
The United Kingdom, France, and Switzerland are contributing steady demand growth as regional pharmaceutical and contract research organization sponsors continue to extend risk-based monitoring software adoption across their clinical trial portfolios. Regional vendors continue to invest in decentralized and hybrid trial design compatibility to serve the region's growing adoption of these increasingly common trial methodologies.
MEA & Latin America Risk-Based Monitoring Software Market Insights
The Middle East & Africa market remains comparatively small but is expanding as growing clinical trial activity across the United Arab Emirates and Saudi Arabia sustains gradual interest in risk-based monitoring software adoption. Regional pharmaceutical and healthcare investment continues to support gradual clinical trial infrastructure development across the broader region.
Latin America's market is led by Brazil, where a growing clinical trial sector continues to drive gradual risk-based monitoring software market growth. Mexico is contributing growth as regional contract research organization activity continues to expand. Across the region, adoption remains concentrated among larger pharmaceutical sponsors and contract research organizations with established international trial relationships.
Market Dynamics
Growth Drivers: Conventional Monitoring Cost Inefficiency and Regulatory Support
The cost and inefficiency of conventional monitoring represents the primary driver of Risk-Based Monitoring Software Market growth, as exhaustive, 100% source data verification approaches continue to impose substantial cost and resource burden relative to the quality assurance value they deliver. Regulatory guidance that is proportionate to the risk involved further contributes to this trend because there has been an increasing tendency within regulatory authorities to favor quality management through a targeted, data-driven approach instead of manual verification, and this gives a definite regulatory endorsement to the use of risk-based monitoring by the sponsors.
A third growth driver for the market would be decentralized and hybrid clinical trials, which are made necessary due to the complexity of modern day clinical trial approaches, which need centralized monitoring capabilities to manage their oversight from different geographic locations using different techniques for collecting the data. The increased number of trials and the outsourcing of trials to contract research organizations further fuels this trend.
Restraints: Implementation Complexity and Data Integration Challenges
Implementation complexity represents a meaningful restraint on market growth, as deploying comprehensive risk-based monitoring software across an organization's clinical trial portfolio requires significant change management, staff training, and process redesign relative to established conventional monitoring practices. This transition complexity, including resistance to change from cleaning everything toward focusing on what data actually needs attention, continues to slow adoption pace among sponsors accustomed to traditional monitoring approaches.
Data integration issues also constitute a constraint as risk-based monitoring needs the ability to integrate data from various sources such as electronic data capture systems, clinical trial management systems, and external data feeds, which can prove to be rather difficult due to the wide variety of legacy systems that continue to exist within the realm of clinical trials technology. This need for interoperability remains an issue that continues to necessitate investments from vendors.
Opportunities: AI-Driven Risk Identification and Unified Platform Integration
Continued integration of artificial intelligence and machine learning algorithms represents a substantial opportunity, as vendors that can develop increasingly sophisticated predictive risk identification capability are positioned to differentiate beyond basic centralized monitoring functionality toward genuinely proactive quality management. Vendors demonstrating superior AI-driven risk detection accuracy are increasingly favored by sponsors seeking to shift from reactive to predictive clinical trial oversight approaches.
The continued development of unified clinical data platforms offers a further avenue for growth, as vendors increasingly combine data capture, cleaning, and risk-based monitoring capability within single, governed architectures that reduce reconciliation burden and accelerate decision-making across the trial lifecycle. Vendors that can deliver seamless, end-to-end clinical data and monitoring platform integration are well positioned to capture demand from sponsors seeking to consolidate their clinical trial technology vendor relationships.
Recent Developments:
- 2026: Anju continues advancing its eClinical suite with capabilities supporting risk-based monitoring, informed decision-making, and accelerated trial lifecycle management, alongside newer AI-enabled solutions.
- 2026: ArisGlobal launched XDI, its Data Intelligence Cortex, connecting fragmented life-sciences data and generating explainable intelligence designed to help organizations anticipate risks and opportunities.
- 2026: Medidata expanded AI capabilities across its platform, reporting AI-supported studies and introducing Medidata AI Study Build to accelerate clinical-study design and execution.
Risk-Based Monitoring Software Market Key Players are:
- Anju Software, Inc.
- ArisGlobal
- Clario
- CluePoints Ltd.
- Dassault Systèmes SE (Medidata Solutions)
- DATATRAK International, Inc.
- DSG, Inc.
- Florence Healthcare
- ICON plc
- International Business Machines Corporation
- IQVIA Holdings Inc.
- Labcorp Holdings Inc.
- MasterControl, Inc.
- Medable, Inc.
- OpenClinica LLC
- Oracle Corporation
- Parexel International Corporation
- Saama Technologies, Inc.
- SAS Institute Inc.
- Veeva Systems Inc.
Risk-Based Monitoring Software Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.46 Billion |
| Market Size by 2035 | USD 1.57 Billion |
| CAGR | CAGR of 13.09% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Enterprise RBM Software, Site RBM Software) • By Component (Software, Services) • By Delivery Mode (Cloud-Based, Web-Based, On-Premise) • By End-User (Pharmaceutical & Biopharmaceutical Companies, Contract Research Organizations, Medical Device Companies, Academic Institutions) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Anju Software, Inc., ArisGlobal, Clario, CluePoints Ltd., Dassault Systèmes SE (Medidata Solutions), DATATRAK International, Inc., DSG, Inc., Florence Healthcare, ICON plc, International Business Machines Corporation, IQVIA Holdings Inc., Labcorp Holdings Inc., MasterControl, Inc., Medable, Inc., OpenClinica LLC, Oracle Corporation, Parexel International Corporation, Saama Technologies, Inc., SAS Institute Inc., Veeva Systems Inc. |
Frequently Asked Questions
Key players include Dassault Systèmes SE (Medidata Solutions), Oracle Corporation, Veeva Systems Inc., Parexel International Corporation, ICON plc, IQVIA Holdings Inc., and CluePoints Ltd., among other clinical technology providers.
Continued integration of artificial intelligence and machine learning algorithms and continued development of unified clinical data platforms represent the primary opportunities.
Growth is primarily driven by the cost and inefficiency of conventional monitoring combined with risk-proportionate regulatory guidance and decentralized and hybrid trial designs.
By Type, Enterprise RBM Software dominated the market with approximately 62.60% share in 2025, reflecting comprehensive, sponsor-level deployment across clinical trial portfolios.
North America dominated the market with approximately 42.60% share in 2025.
