
Robotic Camera Systems Market Report Scope & Overview:
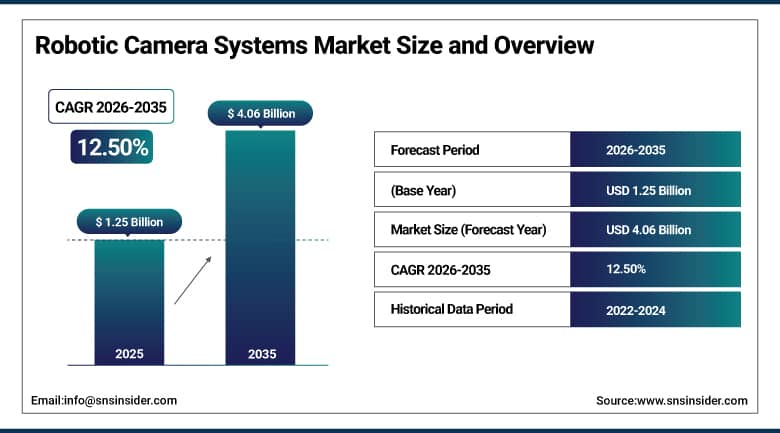
The Robotic Camera Systems Market was valued at USD 1.25 Billion in 2025 and is expected to reach USD 4.06 Billion by 2035, growing at a CAGR of 12.50% from 2026-2035.
The Robotic Camera Systems Market covers remotely controlled and automated cameras that pan, tilt, zoom, slide, rotate or travel on tracks, rails and mobile bases, together with the control software, tracking and automation tools that run them. Broadcasters, sports producers, film and virtual production studios, houses of worship, universities and corporate meeting rooms use them to reduce crew size and repeat precise moves, while security, industrial and defense users deploy them for monitoring and inspection. Demand is rising because artificial intelligence now handles framing, tracking and shot selection, IP workflows such as NDI and SRT simplify installation, and virtual production calls for accurate camera data. Competition combines camera makers, motion control specialists and software firms.
⮞Motion control specialist MRMC is changing hands as it turns 60. In April 2026, Nikon agreed to divest Mark Roberts Motion Control after about ten years of ownership, transferring the company to a vehicle owned by UK-based Blandford Capital, with current management expected to continue. At NAB Show 2026 in Las Vegas, April 19-22, MRMC marked its 60th anniversary by showing the RPS-C2 and RPS-LT roaming pedestal systems with FreeD tracking, the Kronos curved rail system, LiveTrack AI subject tracking in its Flair software, and the Cinebot Max, Mini and Nano robotic arms.
To Get More Information On Robotic Camera Systems Market - Request Free Sample Report
Robotic Camera Systems Market Trends:
-
AI-based auto-framing and subject tracking replacing manual operation
-
Adoption of IP protocols such as NDI HX, SRT and RTMP in PTZ cameras
-
FreeD and camera-tracking data for virtual production and augmented reality
-
Collision avoidance and automation software for multi-robot studios
-
Shift of PTZ and robotic systems into meeting rooms, education and houses of worship
-
Partnerships between camera makers and production platform vendors
U.S. Robotic Camera Systems Market Outlook:
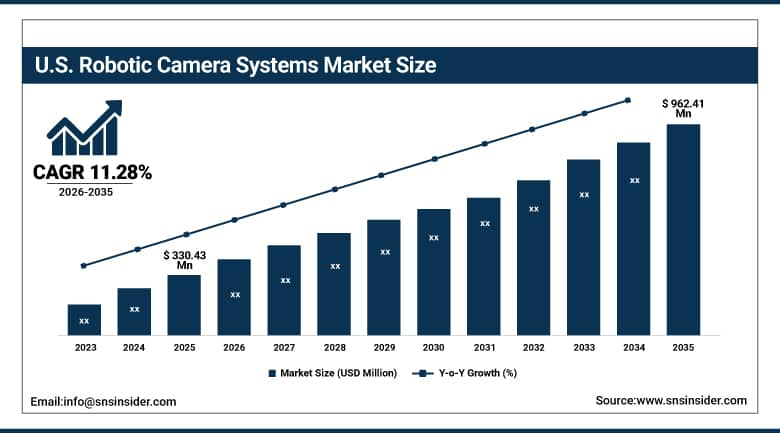
The U.S. Robotic Camera Systems Market was valued at USD 330.43 Million in 2025 and is expected to reach USD 962.41 Million by 2035, growing at a CAGR of 11.28% from 2026-2035.
The U.S. Robotic Camera Systems Market is the largest national market in North America, driven by the scale of broadcast, sports, streaming, house-of-worship, education and corporate video production, as well as large security and industrial deployments. Network broadcasters and regional sports channels use robotic cameras to cut crew costs, while universities, churches and enterprises install PTZ cameras for hybrid events and meetings. The Las Vegas-based NAB Show serves as the annual launch venue for new products, and Hollywood and virtual production stages in Los Angeles, Atlanta and New York use motion control for repeatable shots. Buyers favor IP-based, software-controlled systems that integrate with existing production switchers and cloud workflows.
⮞PTZ cameras are getting smarter for American productions. At the 2026 NAB Show in Las Vegas, April 19-22, Panasonic previewed the AW-UE5 compact 4K PTZ camera, a successor to the AW-UE4 with 4K/60p output and NDI HX support, scheduled for release in the third quarter of 2026. The camera adds Group Framing and Preset Framing, and Panasonic showed Advanced Auto Framing software that uses AI to detect people and control PTZ cameras automatically, as well as the Image Adjust Pro plug-in, which manages up to 20 cameras with one license.
Robotic Camera Systems Market Segment Analysis:
-
By Camera Type, the Mobile Cameras segment dominated the Robotic Camera Systems Market with approximately 41.80% share in 2025, while the PTZ Cameras segment is the fastest growing with a CAGR of approximately 14.20%.
-
By Technology, the Traditional Remote Control segment dominated the Robotic Camera Systems Market with approximately 59.30% share in 2025, while the Machine Learning and AI Integration segment is the fastest growing with a CAGR of approximately 16.80%.
-
By Component, the Hardware segment dominated the Robotic Camera Systems Market with approximately 71.40% share in 2025, while the Software segment is the fastest growing with a CAGR of approximately 15.90%.
-
By Application, the Surveillance segment dominated the Robotic Camera Systems Market with approximately 37.80% share in 2025, while the Broadcasting and Media Production segment is the fastest growing with a CAGR of approximately 13.60%.
-
By End-User, the Government and Security segment dominated the Robotic Camera Systems Market with approximately 35.60% share in 2025, while the Education and Corporate segment is the fastest growing with a CAGR of approximately 15.40%.
By Camera Type, Mobile Cameras Dominates the Robotic Camera Systems Market and PTZ Cameras Grows Fastest
Mobile cameras lead because robot-mounted and vehicle-based units move through large spaces and capture scenes that fixed units cannot cover. Security patrols, industrial inspection, sports production and film sets use wheeled, tracked and aerial platforms, which carry higher unit prices than fixed cameras. Operators value flexible coverage, repeatable paths and reduced risk to personnel in hazardous areas. Ongoing improvements in navigation and batteries extend their reach and keep this category at the top of the market.
PTZ cameras are growing fastest because they deliver broadcast-grade 4K images at much lower cost than studio cameras and need no operator. Canon's CR-N700 and CR-N500, Panasonic's AW-UE5 and PTZOptics' Rise 4K, announced in August 2026 with shipments from the fourth quarter, show the range of new models with 1-inch sensors, genlock, NDI and FreeD. Education, corporate, worship and live-event buyers are replacing conventional cameras, and AI tracking adds value.
By Technology, Traditional Remote Control Dominates the Robotic Camera Systems Market and Machine Learning and AI Integration Grows Fastest
Traditional remote control leads because most installed robotic cameras are operated through joysticks, presets and software panels that crews already understand. Broadcasters and studios have invested in controllers and workflows, and the reliability of manual operation is vital for live programming. Upgrading existing fleets is gradual, so remote-controlled systems continue to account for the majority of revenue even as new products add automation features.
Machine learning and AI integration is growing fastest as cameras learn to detect people, follow speakers, frame groups and select shots without a human operator. Panasonic's Advanced Auto Framing, MRMC's LiveTrack AI and PTZOptics' AI auto-tracking show vendors converting computer vision into standard features. These tools let small teams produce multi-camera content and allow meeting rooms to track speakers automatically. As models run on camera or edge hardware, automation expands to lower-priced products.
By Component, Hardware Dominates the Robotic Camera Systems Market and Software Grows Fastest
Hardware leads because cameras, heads, robotic arms, tracks, pedestals and controllers represent the bulk of purchase cost. Premium optics, 1-inch and larger sensors, precise motors and stabilized mounts command high prices, and professional customers replace or add units on regular cycles. Rental houses also buy equipment for film and live events. Because every installation begins with physical devices, hardware retains the majority of spending.
Software is growing fastest as vendors monetize automation, tracking and fleet management through subscriptions and licenses. MRMC's Flair control software, Ross Video's SmartShell and OverDrive, and PTZOptics' Horizon web interface add presets, collision avoidance, auto-framing and remote monitoring. Updates such as SmartShell 8.2 in September 2026 improved safety for multi-robot studios. Recurring revenue from software is attractive to manufacturers and allows them to differentiate beyond hardware specifications.
By Application, Surveillance Dominates the Robotic Camera Systems Market and Broadcasting and Media Production Grows Fastest
Surveillance leads because public safety, border, critical infrastructure and commercial security programs deploy large numbers of pan-tilt-zoom and mobile cameras. Governments and businesses continue to expand coverage and upgrade to higher resolution and analytics, and long operating hours drive replacement and service revenue. Vendors such as Axis, Hikvision, Bosch and Teledyne FLIR supply integrated systems with detection and tracking, which gives this application the largest base.
Broadcasting and media production is growing fastest as networks, streamers and sports producers cut costs by replacing manned studio cameras with robotic systems and remote production. Virtual production and augmented reality graphics demand exact camera data, which suits robotic heads and arms. Cinebot and Ross Robotics platforms handle repeatable moves, and Canon's partnership with Ross Video in April 2026 shows camera makers integrating PTZ models into production platforms. Live sports and news continue to add installations.
By End-User, Government and Security Dominates the Robotic Camera Systems Market and Education and Corporate Grows Fastest
Government and security users lead because agencies and infrastructure operators purchase large quantities of robotic cameras for surveillance, border control, traffic management and emergency response. Procurement is funded through public budgets and tends to be multi-year, with requirements for ruggedization, encryption and integration with command centers. Defense customers also use robotic cameras on vehicles and fixed sites, adding high-value contracts to the segment.
Education and corporate users are growing fastest as universities, schools, enterprises and houses of worship install PTZ cameras for lecture capture, hybrid meetings, town halls and streaming. Auto-framing and voice tracking features, such as ceiling microphones that cue a PTZ camera to the active speaker, remove the need for a camera operator. Lower prices, NDI and USB connectivity and cloud platforms make installation straightforward, so these buyers add rooms steadily, particularly in North America and Asia Pacific.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
76.40 |
|
Asia Pacific |
China |
39.80 |
|
Europe |
Germany |
30.60 |
|
Middle East & Africa |
United Arab Emirates |
32.60 |
|
Latin America |
Brazil |
42.80 |
North America Robotic Camera Systems Market Insights
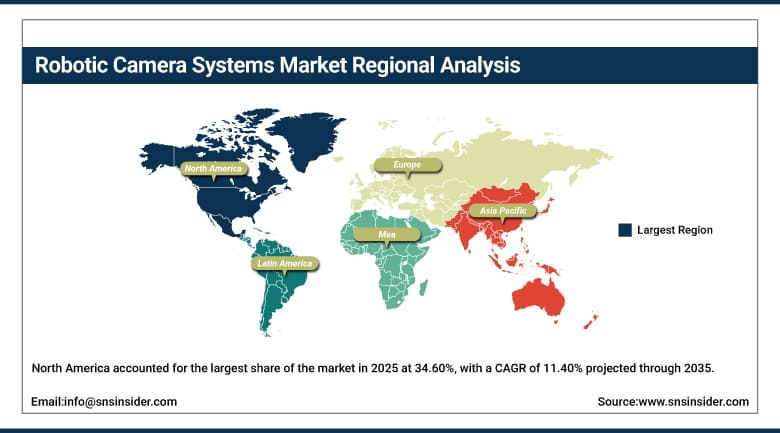
North America accounted for the largest share of the market in 2025 at 34.60%, with a CAGR of 11.40% projected through 2035. The United States holds most regional demand through broadcast and sports production, enterprise and education video, houses of worship, security and industrial inspection, while Canada contributes through Ross Video, a major robotics and production vendor. NAB Show in Las Vegas is the key launch venue for new products.
Panasonic, Canon, Sony, PTZOptics, Blackmagic Design and Telemetrics all target the region, and Canon and Ross Video announced a PTZ partnership at NAB 2026. Growth is steady because the base is large and many studios have already installed robotic systems, but AI automation, virtual production and hybrid work keep upgrading activity strong.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Robotic Camera Systems Market Insights
Asia Pacific held 25.80% of the market in 2025 and is the fastest-growing region, advancing at a CAGR of 14.50% during 2026-2035. China leads regional demand through Hikvision, Dahua and DJI and through large surveillance and live-streaming industries, while Japan, South Korea, India and Australia add broadcast, education and corporate demand. Japanese manufacturers such as Sony, Panasonic and Canon are major suppliers.
Chinese vendors are gaining share with lower-cost PTZ and tracking cameras, and smart city, education and e-commerce live-streaming programs create volume. The region is also expected to account for a growing share of unit shipments as new studios and meeting rooms are equipped. Government spending on public safety and digital infrastructure further lifts demand.
Europe Robotic Camera Systems Market Insights
Europe held 26.40% of the market in 2025 and is growing at a CAGR of 11.60% through 2035. Germany, the United Kingdom, France and the Nordic countries lead through public broadcasters, sports rights holders, film and virtual production studios, and industrial users. IBC in Amsterdam is the main European launch venue, and in September 2026 Ross Video released SmartShell 8.2 with improved collision avoidance, while PTZOptics introduced its Rise 4K camera.
The United Kingdom is home to MRMC and Vinten, two long-established motion control and camera support brands, and MRMC's April 2026 sale by Nikon to Blandford Capital keeps ownership of a leading specialist in Britain. Public broadcasters are modernizing facilities with IP workflows and automation, supporting steady, moderate growth.
MEA & Latin America Robotic Camera Systems Market Insights
The Middle East and Africa held 7.50% of the market and is growing at a CAGR of 13.00%. The United Arab Emirates and Saudi Arabia lead through investment in broadcast centers, sports events, smart cities and security systems, while South Africa and Egypt add media and education demand. Large events and government programs create project-based orders for robotic systems.
Latin America held 5.70% of the market and is growing at a CAGR of 12.80%. Brazil leads, followed by Mexico, Argentina and Colombia, supported by broadcasters, sports leagues, churches and growing education and corporate video. Price sensitivity favors lower-cost PTZ models from Asian and North American vendors, and currency swings can delay purchases, but streaming and public safety projects keep growth healthy.
Market Dynamics:
Growth Drivers: AI Automation, Lower Production Costs and Virtual Production
Artificial intelligence automation is the main driver. Auto-framing, speaker tracking and subject-following features remove the need for operators, so a single technician can run a multi-camera show. Vendors including Panasonic, MRMC and PTZOptics have added AI tools in their 2026 product lines, and customers in broadcast, education and corporate settings adopt them to cut costs while maintaining quality.
Lower production costs and virtual production add momentum. Remote and automated production reduces travel and staffing, and PTZ cameras with 1-inch sensors, genlock and NDI deliver near-broadcast quality at modest prices. Virtual production and augmented reality stages require accurate camera tracking, and FreeD data from robotic heads and arms feeds graphics engines, increasing demand for sophisticated robotic systems.
Restraints: High System Costs, Integration Complexity and Skills Gaps
High system costs restrain adoption of advanced robotic arms, rails and track systems, which can cost many times more than a conventional camera, and require installation, calibration and training. Smaller broadcasters and producers may rent rather than buy, which limits unit sales. Premium motion control gear is also tied to project-based demand that varies with the film and broadcast cycle.
Integration complexity and skills gaps add friction. Robotic cameras must work with switchers, graphics engines, tracking systems and network infrastructure, and not all vendors share open protocols. Studios need technicians who can program moves and manage multi-robot safety, while concerns about job displacement among camera operators can slow acceptance in unionized environments. Data privacy rules also limit use of tracking cameras in some settings.
Opportunities: Software Subscriptions, Meeting Rooms and Virtual Production Stages
Software subscriptions offer a significant opportunity as vendors add paid features for tracking, framing, fleet management and cloud control. Offerings like MRMC's Flair, Ross Video's OverDrive and PTZOptics' Horizon let manufacturers build recurring revenue and customer lock-in, and AI models can be updated over the air to keep installed cameras valuable.
Meeting rooms and virtual production stages provide further growth. Hybrid work, lecture capture and live-streaming create demand for millions of small rooms that benefit from PTZ cameras with voice tracking, while LED volume stages and augmented reality studios need precise robotic movement. Vendors that package cameras, control software and integrations with platforms such as Disguise can capture larger projects.
Recent Developments:
-
In April 2026, Nikon agreed to divest Mark Roberts Motion Control to a vehicle owned by Blandford Capital after roughly ten years, with management expected to continue. At NAB Show 2026, MRMC celebrated its 60th anniversary and showed the Cinebot range, Kronos curved rail and LiveTrack AI.
-
In September 2026, Ross Video released SmartShell 8.2 at IBC2026, improving safety for robotic cameras with better collision avoidance between robots, customizable studio maps and more operator controls.
-
In April 2026, Canon and Ross Video announced a partnership to deliver broadcast-grade PTZ solutions, enabling Canon's CR-N700 and CR-N500 4K PTZ cameras to work within Ross production and robotics workflows.
-
In August 2026, PTZOptics announced the Rise 4K PTZ camera, with a 1-inch 50MP sensor, 20x optical zoom, phase-detect autofocus, 12G-SDI output, FreeD and AI auto-tracking, with orders open and shipments starting in the fourth quarter of 2026.
Robotic Camera Systems Market Key Players:
-
Sony Group Corporation
-
Panasonic Holdings Corporation
-
Canon Inc.
-
Ross Video
-
Mark Roberts Motion Control (MRMC)
-
Vinten (Videndum)
-
PTZOptics
-
Telemetrics Inc.
-
Blackmagic Design
-
Marshall Electronics
-
BirdDog
-
NewTek (Vizrt)
-
Shotoku Broadcast Systems
-
Mo-Sys Engineering
-
SISU Cinema Robotics
-
Blackcam
-
Hangzhou Hikvision Digital Technology
-
Axis Communications AB
-
Bosch Security Systems
-
Teledyne FLIR
Robotic Camera Systems Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.25 Billion |
| Market Size by 2035 | USD 4.06 Billion |
| CAGR | CAGR of 12.50% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Camera Type (Mobile Cameras, PTZ Cameras, Track and Rail Systems, Others) • By Technology (Traditional Remote Control, Machine Learning and AI Integration, Others) • By Component (Hardware, Software, Services) • By Application (Surveillance, Broadcasting and Media Production, Industrial Inspection, Education and Corporate Communications, Others) • By End-User (Government and Security, Media and Entertainment, Industrial and Manufacturing, Education and Corporate, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Sony Group Corporation, Panasonic Holdings Corporation, Canon Inc., Ross Video, Mark Roberts Motion Control (MRMC), Vinten (Videndum), PTZOptics, Telemetrics Inc., Blackmagic Design, Marshall Electronics, BirdDog, NewTek (Vizrt), Shotoku Broadcast Systems, Mo-Sys Engineering, SISU Cinema Robotics, Blackcam, Hangzhou Hikvision Digital Technology, Axis Communications AB, Bosch Security Systems, Teledyne FLIR |

Frequently Asked Questions
Key players include Sony, Panasonic, Canon, Ross Video, Mark Roberts Motion Control, Vinten, PTZOptics, Telemetrics, Blackmagic Design, Marshall Electronics, BirdDog, Shotoku, Mo-Sys, SISU Cinema Robotics, Hikvision, Axis Communications, Bosch Security Systems and Teledyne FLIR.
Key opportunities include subscription software for tracking and fleet management, PTZ cameras with voice tracking for meeting rooms and classrooms, and robotic systems for virtual production and augmented reality stages.
The major growth factor is artificial intelligence automation, which handles framing and tracking and lets small crews produce multi-camera content at lower cost.
By Camera Type, the Mobile Cameras segment dominated the market with approximately 41.80% share in 2025, owing to flexible coverage for security, industrial and production uses.
North America dominated the market with a share of 34.60% in 2025, supported by large broadcast, sports, enterprise and security demand in the United States.
