
Small Molecule API Market Report Scope & Overview:
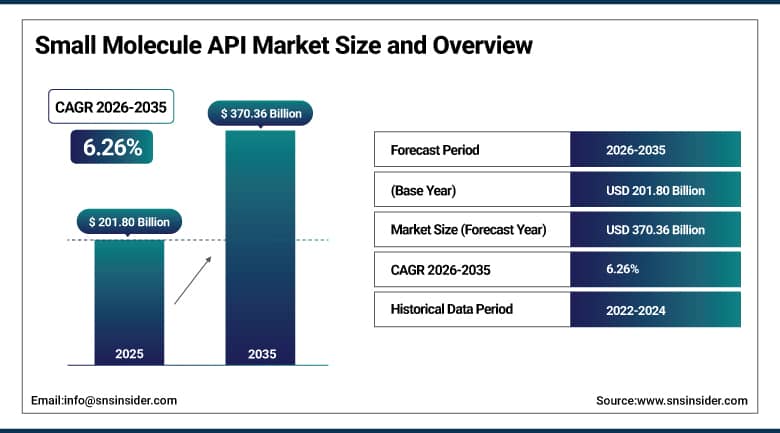
The Small Molecule API Market was valued at USD 201.80 Billion in 2025 and is projected to reach USD 370.36 Billion by 2035, registering a CAGR of 6.26% from 2026 to 2035.
The Small Molecule API Market continues to expand as pharmaceutical manufacturers lean on well-established synthetic chemistry platforms to keep chronic-disease treatment affordable while biologics absorb a growing share of R&D spend. Oral bioavailability, manufacturing simplicity relative to large-molecule biologics, and decades of regulatory familiarity keep small-molecule APIs the backbone of generics, specialty and branded portfolios alike. Rising cancer, cardiovascular and CNS disease burden across aging populations is sustaining volume demand across both developed and emerging healthcare systems.
Government incentive programs in India, China and parts of Europe are pulling API capacity back onshore after years of concentrated outsourcing, reshaping global supply-chain geography. Contract development and manufacturing organizations are absorbing an increasing share of production as originator companies prioritize asset-light models, and continuous-manufacturing and advanced-synthesis investment is gradually reshaping how capacity gets added across the industry.
⮞Cambrex confirmed in March 2026 that it was nearing completion of a multi-year, roughly $100 million small-molecule API capacity expansion spanning its U.S. and European manufacturing sites, a project the company has framed as central to meeting rising CDMO demand from originator and generic customers alike.
To Get More Information On Small Molecule API Market - Request Free Sample Report
Small Molecule API Market Trends
-
CDMOs continue absorbing a rising share of small-molecule API output as originator companies prioritize asset-light manufacturing models.
-
Government incentive programs across India, China and parts of Europe continue pulling API production capacity back onshore.
-
Continuous-manufacturing and advanced-synthesis investment continues lowering per-unit production costs at scale.
-
Rising oncology, cardiovascular and CNS treatment volumes continue sustaining demand for established synthetic chemistry platforms.
-
Digital process-monitoring and AI-enabled quality-control tools continue shortening batch-release cycles across manufacturing sites.
-
Specialty and niche generic API suppliers continue consolidating capacity to compete against larger integrated manufacturers.
US Small Molecule API Market Size Outlook
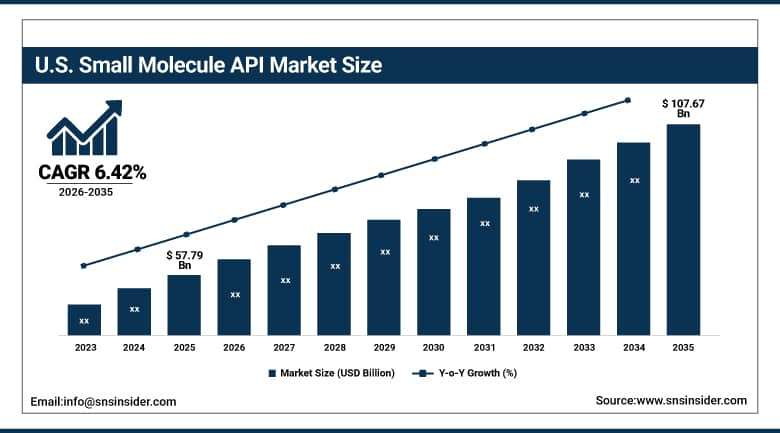
The US Small Molecule API Market was valued at approximately USD 57.79 billion in 2025 and is projected to reach approximately USD 107.67 billion by 2035, registering a CAGR of approximately 6.42% from 2026 to 2035.
Demand across the United States continued to be shaped by sustained oncology and cardiovascular treatment volumes, a large base of generic and specialty manufacturers and growing onshoring interest by originator companies seeking to reduce dependence on offshore API supply following pandemic-era disruptions, but the industry was also faced with new challenges. Rising CDMO capacity investment, fueled by Cambrex’s ongoing U.S. expansion program, further strengthened the country’s position as the largest national market tracked in this report. Branded pharmaceutical companies, too, stepped up collaboration with domestic contract manufacturers, layering on more layers of sustained demand. Across generic and specialty small-molecule portfolios, health systems and payers are putting more focus on supply-chain resilience in addition to cost containment.
⮞WuXi STA named the location for a new small-molecule manufacturing site in the United States in 2026, part of a broader push by Asian-headquartered CDMOs to build dedicated U.S. capacity closer to originator and biotech customers.
Small Molecule API Market Segment Analysis
-
By Type, the Synthetic segment dominated the Small Molecule API Market in 2025 with 86.47% share; the Biotech segment is the fastest growing segment with a CAGR of approximately 7.82%.
-
By Manufacturing Type, the In-house segment dominated the Small Molecule API Market in 2025 with 58.93% share; the Outsourced segment is the fastest growing segment with a CAGR of approximately 8.41%.
-
By Application, the Oncology segment dominated the Small Molecule API Market in 2025 with 28.76% share; the Cardiovascular Diseases segment is the fastest growing segment with a CAGR of approximately 9.17%.
-
By End-User, the Pharmaceutical Companies segment dominated the Small Molecule API Market in 2025 with 68.52% share; the Biotechnology Companies segment is the fastest growing segment with a CAGR of approximately 9.63%.
By Type, Synthetic Dominates the Small Molecule API Market and Biotech Grows Fastest
Synthetic small-molecule APIs dominated the market in 2025, reflecting decades of established chemistry, well-understood regulatory pathways, and manufacturing infrastructure already built out at scale across generic and branded suppliers alike. Worldwide, synthetic APIs remain the default choice for producing high-volume generic and specialty drugs, as validation and scaling of purely chemical synthesis routes are materially cheaper than those of biologically derived processes. A broad knowledge of known synthesis chemistries also reduces the regulatory review timelines, as agencies may utilize decades of precedent when evaluating manufacturing-process changes and impurity profiles for well-characterized small molecules.
The Biotech-derived small-molecule segment is forecast to grow fastest as fermentation and semi-synthetic routes gain traction for complex molecules that are difficult or costly to produce through pure chemical synthesis. Growing biotech-pharma partnerships around novel small molecule modalities such as targeted protein degraders and precision oncology drugs are increasing demand for manufacturing pathways that combine biological and chemical processing steps. Expanding fermentation capacity among specialty CDMOs is also lowering the cost barrier for smaller biotech sponsors seeking hybrid production pathways for complex, hard-to-synthesize candidates. Continued investment in analytical characterization tools is facilitating the ability of regulators to review these more complex manufacturing pathways.
⮞Lonza advanced plans in 2025 to expand its small-molecule API manufacturing capacity in China, citing growing originator and biotech demand for hybrid synthetic and fermentation-based production routes across its network.
By Manufacturing Type, In-house Dominates the Small Molecule API Market and Outsourced Grows Fastest
In-house manufacturing retained the largest share as large originator and generic pharmaceutical companies continue operating integrated API facilities built to secure supply continuity and protect proprietary process know-how for high-volume products. Vertically integrated manufacturers also cite quality-control consistency and reduced technology-transfer risk as reasons for retaining in-house capacity for core revenue-generating molecules. Long-term capital commitments already sunk into existing plants further discourage originators from shifting established, high-volume molecules to external partners mid-lifecycle. Workforce expertise accumulated over years of operating a given process line also represents a switching cost many manufacturers are reluctant to forfeit.
Outsourced manufacturing is forecast to grow fastest as originator companies increasingly shift non-core and specialty API production to CDMOs to reduce fixed capital exposure and access specialized synthesis expertise. The trend is being supported by growing use of contract manufacturers by biotech companies for early and commercial scale production, especially among smaller companies that do not have in-house chemistry infrastructure. Also, expanding CDMO capacity across multiple geographies provides originator companies with more choices for dual-sourcing critical molecules and reducing concentration risk, a priority that has significantly increased since pandemic-era supply disruptions exposed vulnerabilities associated with single-site operations.
⮞WuXi AppTec reported first-quarter 2026 revenue growth of roughly 21%, attributing the gain partly to accelerating global small-molecule capacity expansion as originator customers continued shifting production toward contract manufacturing partners.
By Application, Oncology Dominates the Small Molecule API Market and Cardiovascular Diseases Grows Fastest
Oncology applications dominated the market as rising global cancer incidence and an expanding pipeline of targeted small-molecule therapies continue driving sustained API demand across both branded and generic portfolios. Patent expirations on major oncology small molecules are also widening the generic manufacturing base, reinforcing this application as the largest single revenue contributor industry-wide. Growing adoption of kinase inhibitors and other targeted oral oncology therapies is further diversifying the API manufacturing requirements tied to this application, requiring more specialized synthesis and containment capabilities across the supplier base.
Cardiovascular disease applications are forecast to grow fastest as aging populations across North America, Europe and Asia Pacific sustain rising treatment volumes for hypertension, lipid-disorder and anticoagulant therapies. Growing generic penetration of several widely prescribed cardiovascular small molecules is reinforcing above-average volume growth for this application through the forecast period. Rising diagnosis rates for metabolic syndrome and related comorbidities are additionally widening the patient pool eligible for sustained cardiovascular small-molecule therapy across both developed and emerging markets. Expanding combination-therapy regimens are further increasing the per-patient API volume required for cardiovascular treatment.
⮞Boehringer Ingelheim broke ground in 2026 on a roughly €285 million API production and innovation facility in Ingelheim, Germany, attended by German Chancellor Friedrich Merz's cabinet-level representatives, underscoring continued originator investment in cardiovascular and metabolic small-molecule manufacturing capacity.
By End-User, Pharmaceutical Companies Dominate the Small Molecule API Market and Biotechnology Companies Grow Fastest
Pharmaceutical companies accounted for the largest end-user share, reflecting their position as both the largest consumers and producers of small-molecule APIs across branded and generic product lines worldwide. Established regulatory relationships and large-scale procurement contracts with API suppliers continue reinforcing this end-user segment's dominant revenue contribution. Long-standing supplier-qualification processes also make pharmaceutical companies reluctant to switch API sources once a product is commercially approved, further entrenching existing procurement relationships across multi-year supply agreements that span several manufacturing sites and multiple geographies around the world. Several large pharmaceutical companies have further consolidated their supplier panels around strategically important manufacturing partners.
Biotechnology companies are forecast to grow fastest as smaller, pipeline-stage firms increasingly rely on external API supply and CDMO partnerships rather than building in-house manufacturing infrastructure. Rising biotech investment in small-molecule precision medicine programs is reinforcing demand for flexible, smaller-batch API manufacturing capacity suited to earlier-stage clinical and commercial volumes. Growing venture and public-market funding access for clinical-stage biotech firms is further expanding this end-user segment's purchasing power and willingness to pay premiums for faster-turnaround manufacturing slots ahead of key clinical milestones and regulatory filing deadlines.
⮞India's cumulative investment under its Production Linked Incentive scheme for bulk drugs reached roughly Rs 5,210 crore through June 2026, according to government disclosures, reinforcing domestic capacity available to both pharmaceutical and biotechnology customers sourcing small-molecule APIs.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
73.82% |
|
Europe |
Germany |
26.01% |
|
Asia Pacific |
China |
41.35% |
|
Middle East and Africa |
Saudi Arabia |
33.60% |
|
Latin America |
Brazil |
38.90% |
North America Small Molecule API Market Insights
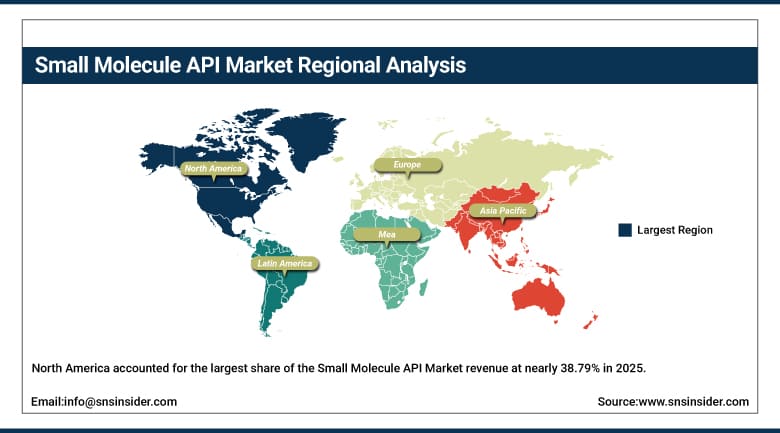
North America accounted for the largest share of the Small Molecule API Market revenue at nearly 38.79% in 2025, due to a large base of originator and generic manufacturers, steady oncology and cardiovascular treatment volumes, and increasing onshoring investment following pandemic-era supply-chain disruptions. The area’s deep regulatory expertise and established CDMO base further bolster its position as the top concentration in the national market tracked in this report. Procurement groups at large health systems have begun to prefer suppliers that can document onshore manufacturing provenance, a preference bolstered by recent federal reviews of supply-chain resilience.
The United States accounted for the substantial majority of regional revenue, anchored by large originator pharmaceutical companies and an expanding domestic CDMO base, while Canada contributed a smaller but steady share through specialty generic manufacturing. Continued federal and private investment in domestic API capacity is expected to reinforce the region's leadership position through the remainder of the forecast period, with several new greenfield announcements already in early planning stages across multiple states and provinces.
⮞Pfizer continued investing in its global manufacturing network to support its small-molecule oncology and cardiovascular portfolio through 2025-2026, reinforcing North America's position as the leading production base tracked in this report.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Small Molecule API Market Insights
Asia Pacific is growing at the fastest rate with a CAGR of around 7.60% between 2026 and 2035. The growth is driven by China’s expanding API export capacity, government-backed incentives for bulk-drug manufacturing in India, and a large base of cost-competitive contract manufacturers serving domestic and export-oriented generic demand across the region. Both countries also have been experiencing growth in domestic healthcare expenditure, which is helping to boost local consumption and export volumes. Insurance coverage is expanding among urban and rural populations, and diagnostic access is improving in emerging secondary cities.
China held the largest share of regional revenue, supported by vertically integrated chemical-synthesis supply chains and continued government funding for domestic API export capacity, while India contributed substantial additional demand through its generics manufacturing base and Production Linked Incentive scheme for bulk drugs. Japan and South Korea added further demand through established pharmaceutical manufacturing and quality-standards infrastructure that continues attracting export-oriented originator contracts from Western customers seeking reliable Asian supply partners beyond the two largest national markets.
⮞Sun Pharmaceutical Industries continued expanding its specialty and generics manufacturing capacity across India through 2025-2026, reinforcing Asia Pacific's position as the fastest-growing region tracked in this report.
Europe Small Molecule API Market Insights
Europe held a meaningful share of global revenue, supported by a long-standing pharmaceutical manufacturing base and continued originator investment in advanced synthesis and continuous-manufacturing capacity across Germany, Switzerland and the United Kingdom. Regional regulatory harmonization under the European Medicines Agency continues to support cross-border API supply within the bloc, lowering the administrative burden of serving multiple member states from a single manufacturing site. Deep chemical-engineering talent pools across several member states further reinforce the continent's manufacturing competitiveness relative to lower-cost offshore alternatives, particularly for complex, high-value specialty molecules.
Germany continued to lead demand at roughly 26.01% of European revenue, supported by its large originator pharmaceutical base and established chemical-manufacturing ecosystem, while Switzerland and the United Kingdom contributed additional demand through specialized CDMO and contract-manufacturing capacity. Continued European investment in onshoring programs should keep regional demand climbing through the forecast period, reinforced by growing EU critical-medicines policy support and coordinated national capacity-planning initiatives across the bloc's largest pharmaceutical-manufacturing member states and their respective supplier ecosystems.
⮞Lonza agreed to acquire a small-molecule drug-production facility from Novartis in Switzerland, a deal disclosed in 2025-2026 that reinforces continued consolidation of European API and drug-product manufacturing capacity among leading CDMOs.
MEA and Latin America Small Molecule API Market Insights
The Middle East and Africa and Latin America both showed steady growth, driven by national healthcare-access expansion programs, growing generic drug manufacturing investment, and rising government interest in reducing reliance on imported active pharmaceutical ingredients across both regions. Public healthcare funding increases are creating new demand channels for affordable generic small-molecule therapies in both areas, with several governments setting formal local-content targets for essential medicines over the next decade as part of broader industrial-policy agendas aimed at reducing import dependence.
Saudi Arabia led Middle East and Africa demand, supported by national healthcare-localization initiatives tied to broader economic diversification goals, while South Africa contributed through an established generic manufacturing base. In Latin America, Brazil accounted for the largest share of regional revenue, with growing domestic generic-manufacturing investment continuing to anchor regional demand for small-molecule APIs across both sub-regions, alongside rising contributions from Mexico and Argentina's expanding generic-pharmaceutical sectors and growing regional trade agreements that are easing cross-border API movement across these developing markets.
⮞Dr. Reddy's Laboratories continued expanding its generic small-molecule API export footprint across the Middle East and Latin America through 2025-2026, part of a broader push by Indian manufacturers to diversify beyond traditional North American and European customer bases.
Market Dynamics
Growth Drivers: Government Onshoring Incentives and Rising Chronic-Disease Treatment Volumes
The industry is driven by government incentive programs such as India's Production Linked Incentive scheme and Bulk Drug Park initiative, growing oncology, cardiovascular and CNS treatment volumes across aging populations, and rising originator interest in diversifying API supply chains after pandemic-era disruptions exposed single-source manufacturing risk. As health systems prioritize both cost containment and supply resilience, demand for both generic and specialty small-molecule API manufacturing capacity continues rising.
Growing CDMO capacity investment is reinforcing this driver by giving originator and biotech companies flexible access to specialized synthesis expertise without requiring in-house capital investment. Continued government funding for domestic manufacturing capacity, particularly across India and China, is further widening the addressable manufacturer base able to compete for export-oriented generic API demand.
⮞Merck & Co. continued expanding its specialty and oncology small-molecule manufacturing capacity through 2025-2026, reinforcing broader industry confidence in capacity investment even amid rising onshoring-driven cost pressure.
Restraints: High Capital Costs and Environmental Compliance Burden
High capital and operating costs continue posing a restraint on faster market-wide expansion, as GMP-compliant manufacturing plants can require tens of millions of dollars in upfront investment before any production revenue is realized. Rising raw-material, energy and skilled-labor costs further compress margins for manufacturers competing on price in commoditized generic API segments.
Stringent and increasingly complex environmental and regulatory compliance requirements, particularly around solvent waste and effluent treatment, also complicate capacity expansion decisions for manufacturers across multiple jurisdictions. Because new facility qualification and regulatory approval cycles can take several years, some manufacturers continue favoring capacity debottlenecking at existing sites over greenfield investment.
Opportunities: Emerging-Market Capacity Growth and Specialty Chemical Diversification
Growing API manufacturing investment across India, China, Brazil and Southeast Asia represents a significant opportunity, as government incentive programs and rising domestic healthcare demand create new capacity-addition channels for both local and multinational manufacturers. Suppliers positioned early in these emerging manufacturing clusters stand to capture meaningful share as global sourcing diversification continues.
Expansion into specialty chemical, agrochemical and cosmetic-ingredient applications offers a second opportunity for manufacturers able to leverage existing synthesis infrastructure beyond core pharmaceutical demand. European pharmaceutical manufacturing clusters in Germany and Spain are also creating opportunities for CDMOs able to offer integrated development-through-commercial-scale services to originator customers.
⮞India kept its Production Linked Incentive application window for new bulk-drug and API manufacturing projects open through December 2025, an opportunity multiple domestic manufacturers moved to capture ahead of the deadline.
Recent Developments:
-
2026: Evonik announced a USD 100 million investment to modernize its Tippecanoe manufacturing facility in Indiana, expanding its small-molecule API and advanced intermediate manufacturing capabilities through upgraded equipment, automation, and production infrastructure.
-
2026: Wilmington PharmaTech announced a USD 50 million expansion of its Delaware manufacturing campus to more than double its small-molecule API reactor capacity, adding two 10,000-liter reactor suites to strengthen domestic commercial-scale API production.
-
2026: BeOne Medicines announced a USD 300 million expansion of its Hopewell, New Jersey manufacturing facility, adding small-molecule manufacturing capacity to support its oncology medicines and clinical development pipeline.
-
2025: Lupin Manufacturing Solutions commissioned a dedicated oncology manufacturing block at its Vizag facility in India, featuring 20 reactors and advanced containment systems to expand high-potency small-molecule API development and commercial manufacturing capabilities.
-
2025: Axplora announced a EUR 6.5 million investment in its Vizag manufacturing facility in India to expand small-molecule API production capacity, strengthen supply-chain resilience, and support growing international demand for pharmaceutical ingredients.
Small Molecule API Companies are:
-
Pfizer Inc.
-
Merck & Co., Inc.
-
AbbVie Inc.
-
Bristol-Myers Squibb Company
-
Albemarle Corporation
-
Boehringer Ingelheim International GmbH
-
Cipla Inc.
-
Teva Pharmaceutical Industries Ltd.
-
Viatris Inc.
-
Dr. Reddy's Laboratories Ltd.
-
Aurobindo Pharma Limited
-
Sun Pharmaceutical Industries Ltd.
-
Lonza Group AG
-
Cambrex Corporation
-
GSK plc
-
Novartis AG
-
Gilead Sciences, Inc.
-
F. Hoffmann-La Roche Ltd
-
Sanofi S.A.
-
Novo Nordisk A/S
Small Molecule API Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 201.80 Billion |
| Market Size by 2035 | USD 370.36 Billion |
| CAGR | CAGR of 6.26% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Synthetic, Biotech) • By Manufacturing Type (In-house, Outsourced) • By Application (Oncology, Cardiovascular Diseases, Diabetes, Central Nervous System (CNS), Others) • By End-User (Pharmaceutical Companies, Biotechnology Companies, CDMOs, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Pfizer Inc., Merck & Co., Inc., AbbVie Inc., Bristol-Myers Squibb Company, Albemarle Corporation, Boehringer Ingelheim International GmbH, Cipla Inc., Teva Pharmaceutical Industries Ltd., Viatris Inc., Dr. Reddy's Laboratories Ltd., Aurobindo Pharma Limited, Sun Pharmaceutical Industries Ltd., Lonza Group AG, Cambrex Corporation, GSK plc, Novartis AG, Gilead Sciences, Inc., F. Hoffmann-La Roche Ltd, Sanofi S.A., Novo Nordisk A/S |

Frequently Asked Questions
The Small Molecule API Market was valued at USD 201.80 billion in 2025.
The market is expected to reach USD 370.36 billion by 2035, reflecting strong long-term growth.
The market is projected to grow at a CAGR of 6.26% over the forecast period from 2026 to 2035.
Key growth drivers include rising demand for generic medicines, chronic disease treatments, cost-effective therapeutics, and increased pharmaceutical manufacturing activities.
Small molecule APIs are widely used because they are chemically stable, easy to manufacture at scale, and highly effective in treating multiple diseases.
