
Prenatal Care Market Report Scope & Overview:
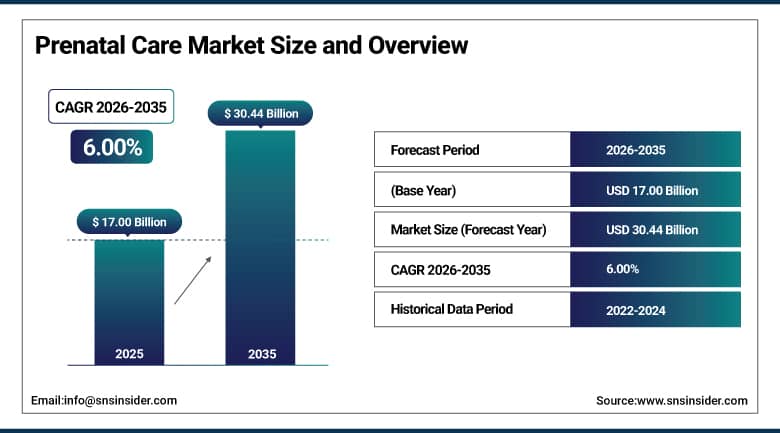
The Prenatal Care Market was valued at USD 17.00 Billion in 2025 and is expected to reach USD 30.44 Billion by 2035, growing at a CAGR of 6.00% from 2026-2035.
The Prenatal Care Market covers the products used to monitor and support the health of mothers and unborn children from conception to delivery. It spans diagnostic and monitoring equipment such as ultrasound systems, fetal dopplers and fetal monitors, along with nutritional supplements, maternity skincare and comfort and support products. Rising maternal age, greater awareness of early screening and the spread of at-home monitoring are lifting demand, while digital health tools and artificial intelligence are changing how routine prenatal checks are delivered through 2035. Suppliers range from global imaging and monitoring manufacturers to consumer health groups, direct-to-consumer vitamin brands and specialist skincare labels, and many of them are expanding into connected services.
⮞The World Health Organization reported in its Global Health Observatory data that 35.5% of pregnant women aged 15 to 49 years were anemic in 2023.
To Get More Information On Prenatal Care Market - Request Free Sample Report
Prenatal Care Market Trends
-
Handheld and point-of-care ultrasound devices with artificial intelligence guidance are allowing trained nurses and midwives to perform obstetric scans outside radiology suites.
-
Wearable and home-based fetal monitoring kits that transmit heart rate and contraction data to clinicians are expanding remote care for high-risk pregnancies.
-
Trimester-specific prenatal supplements with methylated folate, choline and algae-based DHA are replacing generic multivitamins among health-conscious mothers.
-
Direct-to-consumer subscriptions and online pharmacies are becoming a preferred way to buy prenatal vitamins, skincare and support garments.
-
Clean-label and third-party tested formulations, including heavy-metal screening, are shaping purchase decisions for maternity skincare and supplements.
U.S. Prenatal Care Market Outlook
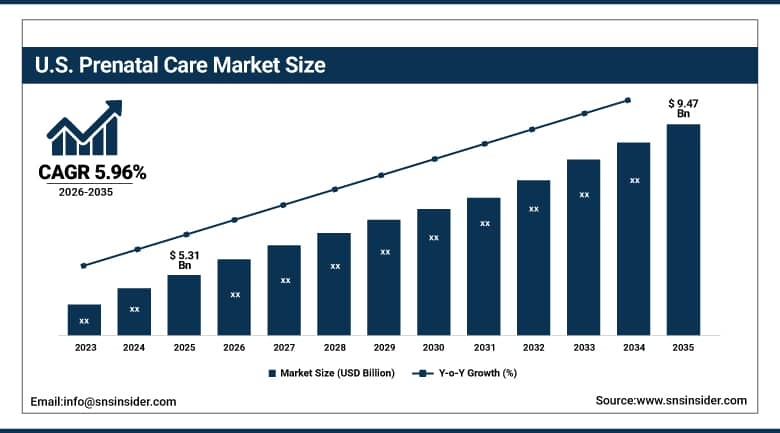
The U.S. Prenatal Care Market was valued at USD 5.31 Billion in 2025 and is expected to reach USD 9.47 Billion by 2035, growing at a CAGR of 5.96% from 2026-2035.
U.S. Prenatal Care Market is the largest national market in North America owing to sophisticated obstetric imaging technologies, high expenditures on maternal care and strong vitamin supplement consumption culture. Obstetric facilities purchase high-resolution ultrasounds and fetal monitoring systems, while consumers buy prenatal vitamins, skincare and support wear from pharmacies, major retailers and online vendors. Telemedicine services, remote patient monitoring services targeting rural population and increasing age of mothers contribute to the growth of the target audience up to 2035. Prenatal programs are being covered by employers and insurance companies, as well as clinics that use software allowing unifying scans, tests and nutritional plans into one record.
⮞The journal JAMA Network Open reported in October 2023 that about 1 in 3 U.S. women used prenatal telehealth during the first year of the COVID-19 pandemic.
Prenatal Care Market Segment Analysis
-
By Product Category, the Prenatal Diagnostic and Monitoring Equipment segment dominated the Prenatal Care Market with approximately 61.37% share in 2025, while the Prenatal Nutritional Supplements segment is the fastest growing with a CAGR of approximately 9.12%.
-
By Equipment, the Ultrasound Imaging Systems segment dominated the Prenatal Care Market with approximately 53.48% share of the equipment category in 2025, while the Electronic Fetal Monitoring Systems segment is the fastest growing with a CAGR of approximately 7.46%.
-
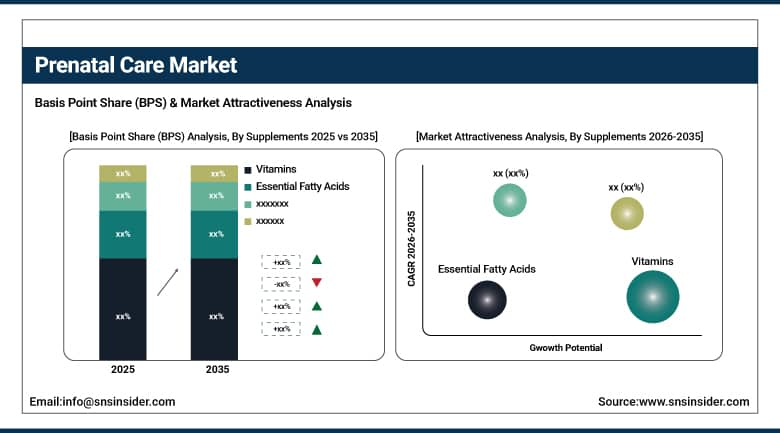
By Supplements, the Vitamins segment dominated the Prenatal Care Market with approximately 38.62% share of the supplements category in 2025, while the Essential Fatty Acids segment is the fastest growing with a CAGR of approximately 14.27%.
-
By Distribution Channel, the Retail Pharmacies and Drug Stores segment dominated the Prenatal Care Market with approximately 42.76% share in 2025, while the Online Pharmacies and E-commerce segment is the fastest growing with a CAGR of approximately 11.38%.
-
By End User, the Hospitals segment dominated the Prenatal Care Market with approximately 56.14% share in 2025, while the Homecare Settings segment is the fastest growing with a CAGR of approximately 9.41%.
By Supplements, Vitamins Dominate the Prenatal Care Market and Essential Fatty Acids Grow Fastest
Vitamins hold approximately 38.62% of the supplements category in 2025. Folic acid, vitamin D, vitamin B12 and choline are routinely recommended by obstetricians to support neural development and reduce birth defect risk, so single and combined vitamin products form the base of most prenatal regimens. Wide availability, affordable pricing and strong clinical guidance keep this segment ahead. Retailers stock a wide range of prenatal tablets, capsules and gummies, and obstetricians often name specific formulations during first visits. Pharmacy staff often recommend a single daily product, which simplifies compliance.
Essential fatty acids are the fastest growing supplement segment, with a CAGR of approximately 14.27% during 2026-2035. DHA and EPA are linked to fetal brain and eye development, and algae-based and sustainably sourced oils appeal to vegetarian consumers. Minerals such as iron, calcium and iodine and complete multivitamin and multimineral formulations remain widely used, with gummies and softgels gaining share over tablets. Clean-label and heavy-metal tested products carry premium prices, and clinical studies on cognitive outcomes strengthen the marketing of omega-3 products.
⮞India’s Ministry of Health and Family Welfare reported through its National Family Health Survey for 2019-21 that mothers consuming iron folic acid for at least 100 days rose from 30.3% to 44.1% between survey rounds.
By Product Category, Prenatal Diagnostic and Monitoring Equipment Dominates the Prenatal Care Market and Prenatal Nutritional Supplements Grows Fastest
Prenatal diagnostic and monitoring equipment holds approximately 61.37% of the Prenatal Care Market in 2025. High unit prices for obstetric ultrasound, fetal monitors and related imaging systems give the category the largest revenue base, and every pregnancy involves multiple scans and monitoring sessions. Hospitals and clinics rely on these systems to track fetal growth, detect anomalies and manage high-risk cases. Replacement cycles of seven to ten years and steady upgrades to higher-resolution probes keep orders flowing even when birth volumes are flat.
Prenatal nutritional supplements is one of the fastest-growing product categories, registering a CAGR of about 9.12% during 2026-2035. Modern women start taking supplements even before conceiving, and prenatal vitamins are available on a trimester basis, making claims that are clinically substantiated. Skincare for maternity and comfort and support products, such as belly bands, pregnancy pillows, and compression gear, continue to generate consistent demand from retailers, although at a slower pace compared to supplements. Special belly oils, creams for stretch marks, and pregnancy pillows generate strong sales through online retail channels and boast of dermatological testing and safe ingredients.
⮞The Organisation for Economic Co-operation and Development reported in its Society at a Glance series that the average age of women at first birth rose from 26.0 years in 1995 to 28.9 years in 2016.
By Equipment, Ultrasound Imaging Systems Dominate the Prenatal Care Market and Electronic Fetal Monitoring Systems Grow Fastest
Ultrasound imaging systems account for approximately 53.48% of the equipment category in 2025. Ultrasound is the standard tool for dating pregnancies, measuring growth, screening for anomalies and guiding procedures, and it is used at least two or three times in a typical pregnancy. Three-dimensional and four-dimensional imaging, automated measurements and cloud reporting are widening adoption among hospitals and imaging centers. Manufacturers are adding artificial intelligence that recognizes standard fetal views and flags measurement errors, which shortens exam times and reduces operator dependence.
Fetal electronic monitoring equipment constitutes the fastest growing equipment category with a CAGR of around 7.46% between 2026 and 2035. Wearable sensors, wireless belts, and cloud analytics help healthcare professionals to monitor the fetal heart rate and contraction patterns remotely. Fetal dopplers continue to be popular as they are used for routine screenings and home monitoring while fetal MRIs are useful in case of complex cases. Manufacturers perceive wearable sensors to be an opportunity to access patients living at a distance from speciality care centers, and there are also many regulatory approvals available.
⮞The journal JAMA Health Forum reported in December 2021 that detailed ultrasound use rose 34.4% in relative terms at the age-35 threshold for advanced maternal age.
By Distribution Channel, Retail Pharmacies and Drug Stores Dominate the Prenatal Care Market and Online Pharmacies and E-commerce Grow Fastest
Retail pharmacies and drug stores account for approximately 42.76% of the Prenatal Care Market in 2025. Expectant mothers value the advice of pharmacists, the ability to compare brands and immediate access to vitamins, skincare and support products. Large drugstore chains carry broad prenatal assortments and run loyalty programs aimed at new parents, which keeps this channel at the center of consumer purchases. Promotional pricing and bundle offers on vitamins, skincare and support garments further encourage in-store purchases at these outlets.
Online pharmacies and e-commerce are the fastest growing channel, with a CAGR of approximately 11.38% during 2026-2035. Subscription plans, doorstep delivery and detailed ingredient information suit busy mothers, and brands use social media and influencers to reach them. Hospital pharmacies supply equipment consumables and prescribed supplements, while supermarkets and hypermarkets sell value-priced vitamins and comfort items. Digital pharmacies in India, China and Brazil are extending reach into smaller cities, where physical stores stock a narrower range of prenatal brands. Marketplace platforms also give smaller brands a low-cost route to shoppers.
⮞UNICEF reported in The State of the World’s Children 2024 that 87% of pregnant women worldwide received at least one antenatal care visit with skilled health personnel.
By End User, Hospitals Dominate the Prenatal Care Market and Homecare Settings Grow Fastest
Hospitals account for approximately 56.14% of the Prenatal Care Market in 2025. They operate the most advanced ultrasound rooms, fetal monitoring units and maternal-fetal medicine departments, and they handle most deliveries and high-risk pregnancies. Purchasing power and the need for reliable, validated equipment make hospitals the main buyers of premium systems and accessories. Group purchasing contracts and long-term service agreements give established suppliers a durable position in these accounts. Inpatient demand is further anchored by neonatal intensive care links and emergency obstetric services.
Homecare settings are the fastest growing end user, with a CAGR of approximately 9.41% during 2026-2035. Connected dopplers, wearable monitors and home-use ultrasound let women track their pregnancy outside the clinic, which suits rural patients and those with mobility or transport barriers. Maternity clinics and diagnostic and imaging centers provide routine scans and tests at lower cost and shorter waiting times than large hospitals. Telehealth platforms that bundle remote monitoring kits with virtual visits are encouraging health systems to promote homecare programs to expectant mothers.
⮞The International Diabetes Federation reported in December 2017 that hyperglycemia in pregnancy affected 16.8% of live births worldwide.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
83.47% |
|
Europe |
Germany |
24.36% |
|
Asia Pacific |
China |
36.82% |
|
Latin America |
Brazil |
38.64% |
|
Middle East & Africa |
Saudi Arabia |
22.91% |
North America Prenatal Care Market Insights
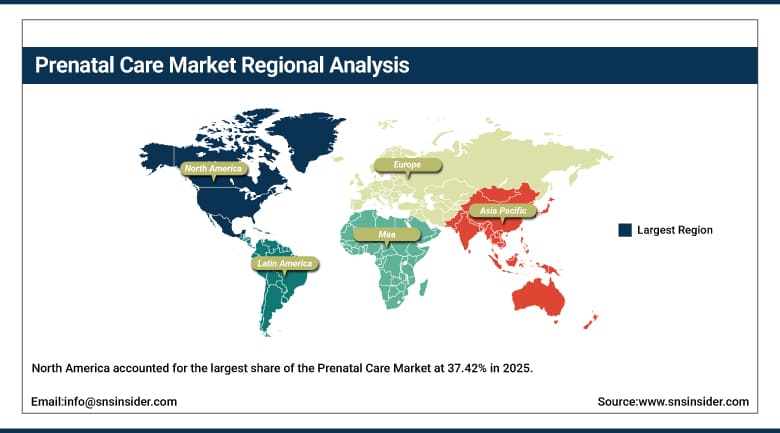
North America accounted for the largest share of the Prenatal Care Market at 37.42% in 2025. The region combines high health spending, early adoption of advanced obstetric imaging and strong awareness of prenatal nutrition. Insurance coverage for prenatal visits and broad access to specialist care support steady equipment replacement and supplement use, and local consumer brands are expanding quickly through online channels. Strong clinical research activity also helps new devices and formulations reach patients sooner. Consumer awareness of prenatal supplements is among the highest in the world.
The United States contributes about 83.47% of regional demand, with Canada accounting for the balance. Canada is seen as the fastest growing country in the region, supported by public programs for maternal care and wider use of midwifery services. Remote fetal monitoring is gaining traction in both countries because of large rural areas with limited obstetric specialists. Private maternity suites and concierge obstetric practices add demand for premium imaging and comfort products. Maternal health programs for underserved communities also fund the purchase of portable devices.
⮞The U.S. Centers for Disease Control and Prevention reported on 9 April 2026 that provisional U.S. births in 2025 totaled 3,606,400, with the cesarean delivery rate at 32.5%, the highest since 2013.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Prenatal Care Market Insights
Europe held approximately 27.18% of the Prenatal Care Market in 2025, with Germany, the United Kingdom, France, Italy and Spain leading demand. Universal healthcare systems provide routine ultrasound screening and antenatal care, creating a stable base for equipment and consumables. The region is also home to several leading imaging manufacturers and pharmaceutical consumer health groups. Strict medical device and food supplement regulations ensure product quality, although they lengthen approval timelines. Public reimbursement for routine scans and tests keeps participation high across income groups.
Germany is the largest market, with about 24.36% of regional demand, because of its strong hospital sector and high spending on screening and supplements. The United Kingdom and France add demand through national maternity programs and a mature pharmacy network. Falling birth rates temper volumes, yet rising maternal age and higher-risk pregnancies increase the value of each pregnancy. Online sales of vitamins and skincare are growing in the Nordic countries and the Netherlands, where digital adoption is high. Midwife-led care models in several countries favor portable and easy-to-use monitoring devices.
⮞Eurostat reported on 6 March 2026 that the European Union recorded 3.55 million live births in 2024, a decline of 3.3% from the previous year, with a total fertility rate of 1.34.
Asia Pacific Prenatal Care Market Insights
Asia Pacific accounted for approximately 22.37% of the Prenatal Care Market in 2025 and is the fastest growing region, with a CAGR of 7.83% during 2026-2035. Large populations, rising incomes, expanding hospital networks and growing awareness of prenatal screening are driving demand. Governments are investing in maternal health programs, and local manufacturers are offering affordable ultrasound and fetal monitoring devices. Rapid urbanization and the spread of private maternity hospitals add to the customer base. Government campaigns on maternal and child health are raising antenatal visit rates in many countries.
China is the largest country market, with 36.82% of regional demand, supported by a strong medical device industry and a shift toward quality-focused prenatal care. India is the fastest growing country, helped by rising institutional deliveries and wider antenatal coverage. Japan and South Korea contribute advanced imaging and premium supplements, while Southeast Asian countries are building maternity capacity. Cross-border e-commerce brings international supplement and skincare brands to middle-class consumers across the region. Local firms offer competitively priced supplements that challenge global brands.
⮞China’s National Bureau of Statistics reported on 28 February 2026 that the country recorded 7.92 million births in 2025, with a crude birth rate of 5.63 per 1,000 people.
MEA & Latin America Prenatal Care Market Insights
The Middle East and Africa and Latin America together account for approximately 13.03% of the Prenatal Care Market in 2025, with Latin America at 7.84% and the Middle East and Africa at 5.19%. In the Gulf, Saudi Arabia and the United Arab Emirates are building modern maternity hospitals and improving screening coverage, while South Africa and Kenya expand access through public clinics and mobile ultrasound programs. Public-private partnerships are funding new maternity wings, and international donors support the supply of basic monitoring tools.
Latin America is driven by Brazil and Mexico. Brazil is blessed with an extensive public healthcare sector and a well-developed private maternity business, while Mexico enjoys the growth of the private insurance sector and pharmacy chains. The Argentinean and Colombian markets contribute small amounts. Cost consciousness prefers inexpensive portable devices and vitamins sold locally, while the role of distribution channels in serving smaller cities is crucial. Growth in urban disposable income promotes the purchase of premium skincare and imported vitamins.
⮞Brazil’s Ministry of Health birth records, analyzed by the Federal University of Pelotas and reported in April 2026, showed prenatal coverage of 99.4% at the first consultation but only 78.1% at the seventh.
Market Dynamics
Growth Drivers: Rising Maternal Age and Awareness of Early Screening Drive Growth in the Prenatal Care Market
Rising maternal age is a strong force behind the Prenatal Care Market. Women who have children later face higher chances of gestational diabetes, hypertension and chromosomal conditions, which leads to more scans, tests and monitoring sessions per pregnancy. Obstetricians recommend closer surveillance for these patients, and each added visit raises demand for equipment, consumables and supportive products. Employer benefits that cover fertility and maternity services further raise participation in early prenatal care. Women with such risks often receive supplementation and monitoring from early in pregnancy.
Greater awareness of early screening and nutrition is the second driver. Public health campaigns, social media and employer wellness programs encourage women to start supplements before conception and to attend antenatal visits early. Falling costs of portable ultrasound and connected monitors extend access to clinics and homes, while insurers and governments in many countries increasingly cover routine prenatal services. Clinical guidelines that recommend folic acid, vitamin D and DHA in pregnancy keep supplement adoption high. Wider coverage of prenatal care by insurers makes premium products easier to afford.
⮞The Office for National Statistics reported that the standardized mean age of mothers in England and Wales reached 31.0 years in 2024, with a total fertility rate of 1.41.
Restraints: Falling Birth Rates and High Equipment Costs Restrain Growth in the Prenatal Care Market
Falling birth rates restrain the Prenatal Care Market. Fewer pregnancies in Japan, China, Korea and much of Europe reduce the number of potential buyers of supplements, skincare and support products. Manufacturers respond by pushing premium offerings, yet volume growth is limited in mature markets, and competition for each expectant mother has become fierce. Declining marriage rates and rising costs of raising children in cities reinforce this trend. Government pronatal incentives have so far had limited effect on these trends. Smaller households also spend less on discretionary maternity items.
High equipment costs add further friction. Advanced obstetric ultrasound and fetal MRI systems require large capital outlays, training and maintenance, which small clinics and public hospitals in developing regions find difficult to afford. Regulatory approval for new monitors and home-use devices can take long, and concerns about unsupervised use of consumer ultrasound remain among clinicians. Reimbursement gaps for home monitoring in some countries slow adoption of new devices. Smaller clinics often delay purchases or buy refurbished systems. Import tariffs on medical devices raise prices in some markets.
⮞Japan’s Ministry of Health, Labour and Welfare reported on 26 February 2026 that preliminary births in 2025 fell 2.1% to 705,809, the tenth consecutive record low.
Opportunities: Remote Monitoring and Personalized Nutrition Create Opportunities in the Prenatal Care Market
Remote monitoring offers a major opportunity. Wearable fetal and maternal sensors, connected blood pressure cuffs and telehealth platforms allow clinicians to follow pregnancies at a distance, which reduces travel and hospital visits. Maternity care deserts, rural regions and low-income countries stand to benefit, and health systems and payers are beginning to fund such programs. Startups and established manufacturers are developing algorithms that predict preeclampsia and preterm birth risk. Subscription-based monitoring services also create recurring revenue for device makers. Voice assistants and chat tools add guidance between visits.
The second opportunity lies in personalized nutrition. With genetic tests, blood tests, symptom-tracking applications, and AI technologies, brands can develop personalized formulae for supplements, which will be able to support premium prices and loyalty programs. There are many emerging markets, where the penetration rate of antenatal care and supplements is growing. This provides brands with a long-term opportunity for expansion beyond the traditional geographic markets. Collaboration of pharmacies, telehealth organizations, and brands will enable brands to offer comprehensive packages of care to pregnant women.
⮞Statistics South Africa reported that 932,138 births were registered in 2023, with the median age of mothers at 28.3 years, the highest since 2004.
Recent Developments:
-
2025: Pulsenmore received U.S. FDA de novo clearance for Pulsenmore ES, a home-use prenatal ultrasound system that lets pregnant women scan themselves and send images to remote physicians for review.
-
2026: Ritual launched its Essential Prenatal Multivitamin as a Costco exclusive two-pack across about 200 West Coast warehouses, supported by findings from a randomized trial of 62 women.
-
2026: EDAN Instruments received CE marking for the Nano OB Assist, an AI-enabled handheld ultrasound with blind-sweep scanning that reports gestational age and fetal presentation, and launched it in Nairobi for prenatal screening in Africa.
-
2026: HealthyBaby relaunched Our Prenatal with trimester-specific formulas, split morning and night dosing, inositol, natural folate and heavy-metal testing.
Prenatal Care Market Key Players are:
-
Ge Healthcare Technologies Inc.
-
Koninklijke Philips N.V.
-
Siemens Healthineers Ag
-
Samsung Medison Co., Ltd.
-
Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
-
Fujifilm Holdings Corporation
-
Canon Medical Systems Corporation
-
Drägerwerk Ag & Co. Kgaa
-
Edan Instruments, Inc.
-
Huntleigh Healthcare Limited (Arjo)
-
Bayer Ag
-
Pharmavite Llc (Nature Made)
-
Nestlé S.A.
-
Church & Dwight Co., Inc.
-
Procter & Gamble Company
-
Thorne Healthtech, Inc.
-
Ritual, Inc.
-
Laboratoires Expanscience (Mustela)
-
E.T. Browne Drug Co., Inc. (Palmer's)
-
Medela Ag
Prenatal Care Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 17.00 Billion |
| Market Size by 2035 | USD 30.44 Billion |
| CAGR | CAGR of 6.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Category (Prenatal Diagnostic and Monitoring Equipment, Prenatal Nutritional Supplements, Maternity Skincare Products, Pregnancy Comfort and Support Products, and Others) • By Equipment (Ultrasound Imaging Systems, Fetal Doppler Devices, Electronic Fetal Monitoring Systems, Fetal MRI Systems, and Others) • By Supplements (Vitamins, Minerals, Essential Fatty Acids, Prenatal Multivitamin and Multimineral Formulations, and Others) • By Distribution Channel (Hospital Pharmacies, Retail Pharmacies and Drug Stores, Online Pharmacies and E-commerce, Supermarkets and Hypermarkets, and Others) • By End User (Hospitals, Maternity Clinics, Diagnostic and Imaging Centers, Homecare Settings, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Ge Healthcare Technologies Inc., Koninklijke Philips N.V., Siemens Healthineers Ag, Samsung Medison Co., Ltd., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Fujifilm Holdings Corporation, Canon Medical Systems Corporation, Drägerwerk Ag & Co. Kgaa, Edan Instruments, Inc., Huntleigh Healthcare Limited (Arjo), Bayer Ag, Pharmavite Llc (Nature Made), Nestlé S.A., Church & Dwight Co., Inc., Procter & Gamble Company, Thorne Healthtech, Inc., Ritual, Inc., Laboratoires Expanscience (Mustela), E.T. Browne Drug Co., Inc. (Palmer's), Medela Ag |

Frequently Asked Questions
The key players in the Prenatal Care Market include GE HealthCare Technologies Inc., Koninklijke Philips N.V., Siemens Healthineers AG, Samsung Medison Co., Ltd., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., among others.
Key opportunities include remote and wearable monitoring for rural and high-risk patients, and personalized nutrition supported by testing, apps and subscription models.
The major growth factor is rising maternal age, which increases the number of scans, tests and monitoring sessions per pregnancy, along with greater awareness of early screening and prenatal nutrition.
The Prenatal Diagnostic and Monitoring Equipment segment dominated the Prenatal Care Market with approximately 61.37% share in 2025, because high-value ultrasound and fetal monitoring systems are used throughout every pregnancy.
North America dominated the Prenatal Care Market with a 37.42% share in 2025, supported by advanced obstetric imaging, high health spending and strong awareness of prenatal nutrition.
