
Solar Control Window Film Market Report Scope & Overview:
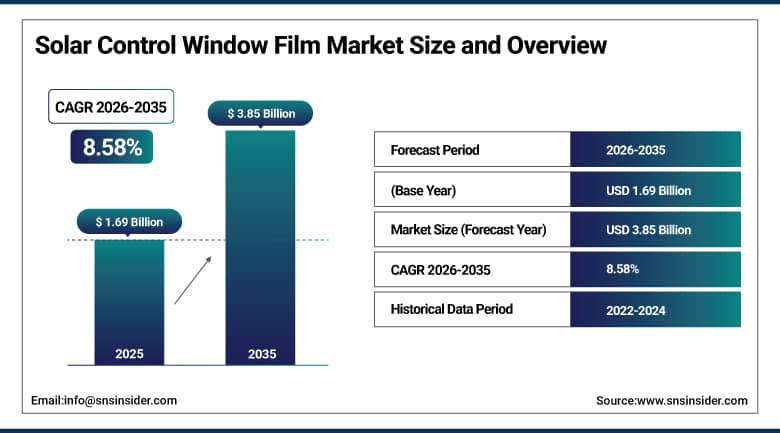
The Solar Control Window Film Market was valued at USD 1.69 Billion in 2025 and is anticipated to climb to USD 1.84 Billion in 2026 and USD 3.85 Billion by 2035, registering a CAGR of 8.58% over 2026–2035. Solar control window films are thin polyester layers, coated with metals, ceramics or dyes, that are bonded to glass to reject heat, block ultraviolet light and cut glare. They lower cooling loads in buildings and keep vehicle cabins comfortable, and they protect furniture and interiors from fading without the cost of replacing the glass.
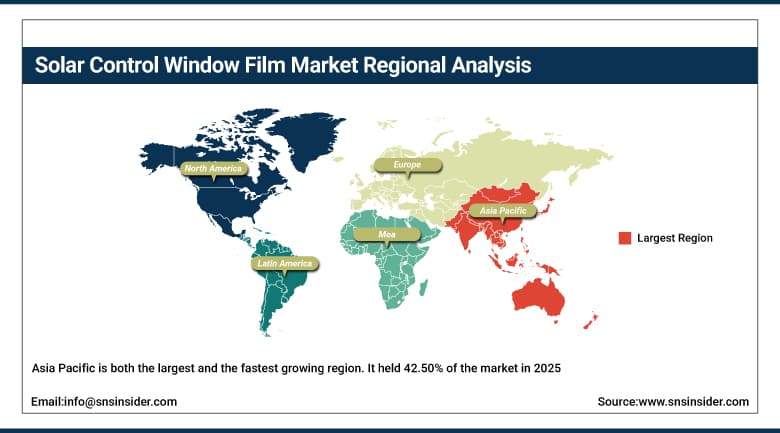
Asia Pacific accounted for the largest share of the market, at 42.50% in 2025, as China, India, Japan and Southeast Asia combine hot climates, rapid building activity and large vehicle fleets. North America is the second largest region, followed by Europe, Latin America and Middle East and Africa. Asia Pacific is also the fastest growing region, supported by urban construction, energy efficiency rules and rising vehicle ownership. Producers sell through installers, glass dealers, automotive tint shops and distributors, and warranty terms, dealer training and film durability under strong sun often decide which brand a customer chooses.
To Get More Information On Solar Control Window Film Market - Request Free Sample Report
Key Report Takeaways
-
By film type, vacuum coated films held a 37.90% share in 2025, while nano-ceramic films are the fastest growing.
-
By absorber type, ceramic films held a 42.30% share in 2025, while metallic films are the fastest growing.
-
By application, construction held a 52.40% share in 2025, while automotive is the fastest growing.
-
By region, Asia Pacific held a 42.50% share in 2025 and is also the fastest growing.
Market Trends and Insights
Building owners are treating window film as a quick retrofit for energy savings. Applying film to existing glass costs far less than replacing windows, and it can pay back through lower cooling bills in a few years. Green building programs and local energy codes increasingly credit solar control film, and facility managers bundle it with security and safety layers.
Ceramic and nano-ceramic technology is replacing dyed and metallic films in vehicles. These films reject infrared heat without blocking radio, phone or navigation signals, and they keep a neutral look that meets legal limits on light transmission. Electric vehicle makers value them because lower cabin heat reduces air conditioning load and protects driving range. Dealers report stronger upsell.
Installers are moving toward premium film brands backed by warranties and certified dealer networks. Pre cut kits, digital pattern software and paint protection film cross selling raise shop revenue, and manufacturers are adding capacity and training programs to support dealers in hot regions. Online ordering and shop financing programs also make premium film easier to buy for small installers.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Energy efficiency rules and retrofit demand in buildings |
+3.12% |
North America, Europe and Asia Pacific |
Long term (4 years or more) |
|
Rising vehicle ownership and demand for cabin comfort |
+2.41% |
Asia Pacific, North America and Middle East and Africa |
Medium term (2 to 4 years) |
|
Hot climate and heat wave exposure |
+1.62% |
Middle East and Africa, Asia Pacific and Latin America |
Long term (4 years or more) |
|
Advances in ceramic and nano-ceramic film technology |
+1.28% |
Global |
Medium term (2 to 4 years) |
|
Growth in commercial real estate and premium glazing |
+0.89% |
Asia Pacific, Middle East and Africa and Europe |
Short term (2 years or less) |
Energy Efficiency Rules and Retrofit Demand in Buildings
Glass walls are common in offices, hospitals, schools and apartments, and they let in large amounts of solar heat that air conditioners must remove. Window film can cut that heat gain at a fraction of the cost of new glazing, so owners of older buildings use it to meet efficiency targets. Building codes, green certification programs and utility rebates in several regions support adoption, and rising electricity prices shorten payback. Property managers also use film to improve tenant comfort, which helps retain occupancy.
Rising Vehicle Ownership and Demand for Cabin Comfort
Car and truck buyers want cooler cabins, ultraviolet protection and privacy, and window tint is one of the most popular aftermarket additions. Growing middle classes in India, China, Southeast Asia and the Middle East are buying more vehicles, and many fit film at purchase. Electric vehicles raise interest further, since heat reduction helps preserve battery range. Fleet owners add tint to buses, vans and trucks for driver comfort, and ride hailing operators use it to improve passenger experience. Dealers bundle film with new car sales, and online reviews of tint brands guide buyers toward certified installers who offer warranties.
Hot Climate and Heat Wave Exposure
Longer and hotter summers are pushing households and businesses to look for heat control. Regions with strong sun, such as the Gulf, South Asia, Australia, the American Southwest and southern Europe, record the highest film use per building and per vehicle. Heat wave warnings and rising cooling costs make film an easy and visible response for property owners. Cities issue cooling advisories that favor passive measures such as film, shades and reflective roofs, and public buildings in hot regions now add film to refurbishment lists. Insurers and landlords also see film as a way to limit glass breakage from thermal stress.
Advances in Ceramic and Nano-Ceramic Film Technology
New coatings and sputtering methods give films that reject more infrared energy while staying optically clear, with low haze and no signal interference. Manufacturers are adding layers that improve scratch resistance, durability and color stability. These gains justify higher prices and help film compete against tinted glass and low emissivity coatings in renovation projects. Spectrally selective layers let designers keep large windows without a strong tint, and architects specify them in glass heavy facades. Better adhesives and edge sealing extend warranties, so building owners accept film as a long term investment rather than a short fix.
Growth in Commercial Real Estate and Premium Glazing
New office towers, hotels, airports and retail centers use large glass facades, and owners apply film to control glare and tenant comfort. Premium projects also add safety and security film, which creates cross selling opportunities for dealers and installers. Tenants in premium offices expect daylight and views without glare, and hospitality brands specify film to protect guest comfort and privacy. Developers in Asia and the Gulf pair film with smart glass and shading systems, and airports add film to terminals with long glass walls to reduce heat on passengers and equipment, which raises both project volumes and the spend per square meter on each site over time.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Legal limits on light transmission and tint rules |
-0.34% |
Global |
Medium term (2 to 4 years) |
|
Competition from factory tinted and low emissivity glass |
-0.21% |
North America, Europe and Asia Pacific |
Long term (4 years or more) |
|
Installation quality, warranty and counterfeit film issues |
-0.12% |
Asia Pacific, Latin America and Middle East and Africa |
Medium term (2 to 4 years) |
|
Raw material and polyester film price volatility |
-0.07% |
Global |
Short term (2 years or less) |
Legal Limits on Light Transmission and Tint Rules
Many countries and states set minimum visible light transmission for windshields and front side windows, and enforcement varies widely. Drivers who receive citations may avoid film, and installers must check local rules for each job. Differences in rules across borders complicate product ranges for manufacturers and raise inventory costs. Some regions ban dark tint on front windows altogether, and inspection failures can lead to fines and film removal, which discourages first time buyers. Police checks, annual vehicle tests and insurance disputes add uncertainty for owners.
Competition from Factory Tinted and Low Emissivity Glass
New buildings increasingly use glass with solar control coatings from the factory, and car makers supply privacy glass with built in heat rejection. These options remove the need for aftermarket film in new projects. Window film then relies on the large stock of existing glazing, where owners must be convinced that film is a safe and durable solution. Auto makers now offer infrared reflective windshields and laminated glass as options, and many premium models include them, so owners of new cars see less need for added film.
Installation Quality, Warranty and Counterfeit Film Issues
Poor installation can cause bubbles, peeling and distortion, and some films fail early in strong sun. Low priced imitation films without proper testing harm the reputation of the category. Skilled installers are scarce in some regions, so manufacturers must invest in training, dealer certification and anti counterfeit marking. Customers rarely see the difference between certified and unbranded film at the time of sale, so price shopping can push buyers toward lower quality products. A few early failures spread quickly through reviews and social media and discourage others from trying film.
Raw Material and Polyester Film Price Volatility
Window film depends on polyester base film, adhesives, dyes and sputtered metals, whose prices change with oil, energy and metal markets. Producers cannot always pass higher costs to dealers quickly, and shipping disruptions add further uncertainty. Smaller converters hold limited stock and buy at spot prices, which strains cash flow when costs jump. Producers hedge some inputs, but long approval cycles for new film grades make quick supplier changes hard, and energy intensive coating lines face higher power bills in several regions.
Solar Control Window Film Segment Analysis
By Film Type, Vacuum Coated Films Dominate Solar Control Window Film Market; Nano-Ceramic Films to Register Fastest Growth.
Vacuum coated films lead the film type axis, holding a 37.90% share in 2025. Thin layers of metal or oxide are sputtered onto polyester in a vacuum chamber, which gives strong heat rejection, good durability and a wide range of looks. They are widely used on commercial facades and vehicles, and many dealers prefer them for dependable performance at a moderate price. Pricing is competitive, and supply is wide. Installers handle them easily and stock is plentiful across regions.
Nano-ceramic films are expected to register the fastest growth, at a CAGR of 10.05% during 2026–2035. Ceramic nanoparticles reject infrared heat while keeping high visible light, so the film stays clear and does not block signals. Premium vehicle buyers and design focused building owners favor these products. Their appearance is natural, so they suit luxury cars, hotels and corporate towers. Producers keep adding layers that improve scratch resistance and color stability, and strong warranties support premium pricing. Warranties are long.
By Absorber Type, Ceramic Films Dominate Solar Control Window Film Market; Metallic Films to Register Fastest Growth.
Ceramic films lead the absorber type axis, holding a 42.30% share in 2025. They use ceramic particles that absorb and block infrared and ultraviolet energy, offering strong heat control, long life and no interference with electronics. Their stable color and resistance to fading make them the usual choice for premium vehicle and building projects. Dealers stock them widely, and fast installation helps shops serve more customers each day. Installers like the predictable look and the broad range of shades available.
Metallic films are projected to register the fastest growth, at a CAGR of 8.88% over 2026–2035. Thin metal layers reflect a large share of solar energy and give high privacy and a distinct appearance. Cost advantages and strong adoption in commercial buildings in hot climates support steady expansion. Buyers in hot countries like the strong privacy and glare reduction. Newer metallic layers resist corrosion and keep radio signals clear, which removes a major earlier drawback and widens use.
By Application, Construction Dominates Solar Control Window Film Market; Automotive to Register Fastest Growth.
Construction leads the application axis, holding a 52.40% share in 2025. Offices, retail centers, hospitals, schools and homes apply film to cut cooling loads, reduce glare and protect interiors, and retrofit projects form most of the demand. Commercial buildings account for the larger part of this segment because of their large glass areas. Retrofit demand rises with energy codes. Property owners also seek safety benefits from film, and installers combine solar control layers with shatter resistance. Demand stays firm.
Automotive is expected to register the fastest growth, at a CAGR of 9.49% during 2026–2035. Rising vehicle sales, growing interest in cabin comfort and the popularity of ceramic tint in electric vehicles lift demand. Fleet operators for buses, trains and delivery vehicles also use film to reduce air conditioning load. Shop revenue from cabin film also grows through paint protection and detailing packages sold alongside. Premium film packages are sold with paint protection, and shops report strong repeat business.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
46.60% |
|
North America |
United States |
84.20% |
|
Europe |
Germany |
24.80% |
|
Middle East and Africa |
Saudi Arabia |
27.60% |
|
Latin America |
Brazil |
46.90% |
Asia Pacific Solar Control Window Film Market
Asia Pacific is both the largest and the fastest growing region. It held 42.50% of the market in 2025 and is expected to register a CAGR of 9.16% during 2026–2035. China leads with the largest vehicle market and heavy building activity, while India is a major production base and a fast growing consumer, supported by hot summers and expanding cities. Large property developers specify film in new towers, and national green building labels in India and China encourage low cost heat control for existing offices and schools.
Japan and South Korea supply premium products and advanced coatings, and Southeast Asian countries are adding offices, malls and vehicle sales. Australia has a strong tint culture and high film use. Local producers are scaling up, and international brands operate regional plants and dealer networks. Taiwan, Thailand and Indonesia sustain high demand for vehicle tint, and Pakistan and Bangladesh add growth in hot cities. Branded dealers expand quickly in secondary cities, and online platforms help shops source film. Counterfeit concerns persist, so certified products gain.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Solar Control Window Film Market
North America held 26.80% of the market in 2025. The United States market was valued at USD 381.36 Million in 2025 and is projected to register a CAGR of 7.08% during 2026–2035. A large installed base of glass buildings, hot southern states and strong aftermarket vehicle tint support demand. Corporate campuses, hospitals and universities use film to meet sustainability goals, and homeowners in Texas, Florida and California add film to cut cooling bills during long summers. Rebates add further support.
Canada contributes through energy retrofit programs and vehicle tint, and utilities in several states offer incentives for solar control film. Mature dealer networks and branded warranties help adoption, while state tint laws shape product mix. Large brands maintain strong distribution through glass dealers and automotive tint chains, and paint protection film cross selling lifts shop revenue. Wildfire and storm regions also add demand for safety layers combined with heat control, and residential retrofit grows as electricity prices rise. Standards are high.
Europe Solar Control Window Film Market
Europe accounted for 20.40% of the market in 2025. Germany, France, the United Kingdom, Italy and Spain have large stocks of older buildings with single or double glazing, and energy renovation programs encourage low cost upgrades such as film. Southern Europe has the strongest use because of hot summers. Public buildings in Spain, Italy and Greece lead adoption, and German and Nordic offices use film to limit glare on screens and to reduce cooling loads in new heat wave periods.
Rules on building energy performance and rising heat wave risk raise interest in passive cooling. Vehicle tint is regulated more tightly than in other regions, so architectural film makes up a larger share of sales. Several leading producers and converters are based in the region. Preference for architectural film helps manufacturers sell higher value neutral and low reflectivity grades, and installers with strong training win municipal contracts. Eastern European countries are upgrading office stock, and energy audit programs increasingly include film as an eligible measure.
Middle East and Africa Solar Control Window Film Market
Middle East and Africa accounted for 4.60% of the market in 2025. Gulf countries have intense sun, large glass towers and high cooling costs, and Saudi Arabia and the United Arab Emirates lead regional demand. Vehicle tint is very popular, and installers serve a large fleet of cars and sport utility vehicles. Hotels, malls, airports and government buildings apply film during construction and refurbishment, and homeowners in villas add privacy film to reduce heat and cooling bills. Demand stays strong.
In Africa, South Africa, Egypt and Nigeria are growing urban centers with more offices and malls, and rising vehicle imports lift tint use. Counterfeit products and uneven installer skills are challenges, but heat and electricity costs support long term growth. Qatar, Kuwait and Oman add steady project demand, while Turkey and Israel have local production and export. Gulf governments promote energy efficiency, and premium film brands operate large dealer networks and warehouses across the region to serve both vehicles and buildings.
Latin America Solar Control Window Film Market
Latin America held 5.70% of the market in 2025. Brazil leads the region with a large vehicle fleet, hot coastal cities and active commercial building, and film is widely used on cars and office glass. Mexico adds demand from northern manufacturing cities and tourist resorts. Chile and Peru add demand from mining camps and offices, and security film and heat control are often sold together in cities where break in protection matters. Retail chains and shopping centers across Sao Paulo and Rio de Janeiro keep adding film.
Argentina, Colombia and Chile are growing through urban construction and car sales, and security film adds extra demand where safety is a concern. Currency swings and import costs affect pricing, yet hot climates and growing middle classes support steady long term growth. Local assembly and distribution networks are growing, yet imports dominate premium film. Rising electricity tariffs and heat waves in Argentina and Brazil lead owners to explore heat reduction, and car tint culture is strong in Colombia and Peru, which supports steady aftermarket sales across the region.
Competitive Landscape
The Solar Control Window Film Market is moderately consolidated, with a few global firms that hold a large share of branded sales and many regional converters and tint shops that compete on price. Large firms combine film manufacturing, research, dealer networks and warranty programs, while smaller producers focus on local brands and simple products.
Competition depends on heat rejection performance, durability, optical clarity, price, dealer support and brand trust. Companies are adding coating capacity, launching new ceramic and paint protection lines and training installers. Over the forecast period, technology, dealer reach and warranty support are expected to separate leading suppliers from the rest.
Solar Control Window Film Industry Leaders
1. Eastman Chemical Company
2. Garware Hi-Tech Films
3. Lintec Corporation
4. 3M Company
5. XPEL
Companies Covered in this Report
-
3M
-
Avery Dennison
-
Eastman Chemical Company
-
Garware Hi-Tech Films
-
Johnson Window Films
-
Lintec Corporation
-
Madico
-
Saint-Gobain
-
V-Kool
-
XPEL
Recent Industry Developments
-
September 2025: Garware Hi-Tech Films began commercial production of a new paint protection film line at its Waluj facility in India.
-
November 2025: XPEL announced plans to invest between USD 75 million and USD 150 million in manufacturing and supply chain capacity over two years.
-
April 2026: Eastman debuted as an independent exhibitor at Auto China 2026 in Beijing, presenting infrared reflecting films for panoramic sunroofs and door glass heat insulation.
-
September 2026: 3M introduced 3M Cooling Film for vehicle roofs, designed to reflect more than 85.00% of incoming solar radiation for fleet, rail and commercial vehicles.
Scope and Research Methodology
This study sizes the Solar Control Window Film Market for 2025 and forecasts it to 2035. The scope covers polyester based films applied to glass to reject solar heat, ultraviolet and glare, including vacuum coated, dyed, high performance and nano-ceramic films for buildings and vehicles, measured as manufacturer sales value in USD Billion. Safety and security films, decorative films, paint protection films and factory applied glass coatings are excluded. Values are reported on a calendar year basis, and trade is allocated to the country of production. The historical period covers 2021 to 2024 and the forecast period covers 2026 to 2035.
Research began with a review of glass area in buildings, vehicle registrations, tint regulations, energy codes, polyester film prices, company filings and trade data. Demand was built from the bottom up using film area, film share of retrofit and aftermarket installations and price per square meter by type, and it was cross-checked from the top down using the sales of leading producers. Segment and regional shares were set from climate, building stock and vehicle mix in each geography. Product prices were reviewed by film type and construction to convert area into revenue, and constant exchange rates were used to remove currency effects. Assumptions were documented for each major country. Channel checks were repeated.
Findings were validated through discussions with film producers, distributors, installers and building owners, and the forecast was tested under scenarios for energy prices, vehicle sales, regulation and construction activity. Growth rates reflect expected adoption and price trends. Values are expressed in USD, rounded to two decimals, and the analysis is refreshed when major market or policy changes occur. Estimates for each region were checked against national glass, vehicle and trade statistics where available, and adjustments were made for imported and exported rolls. Results are reviewed periodically. Assumptions are documented.
Solar Control Window Film Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.69 Billion |
| Market Size by 2035 | USD 3.85 Billion |
| CAGR | CAGR of 8.58% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Film Type (Vacuum Coated, Dyed, High Performance, Nano-Ceramic, and Others) • By Absorber Type (Ceramic, Metallic, and Organic) • By Application (Construction, Automotive, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | 3M, Avery Dennison, Eastman Chemical Company, Garware Hi-Tech Films, Johnson Window Films, Lintec Corporation, Madico, Saint-Gobain, V-Kool, XPEL |

Frequently Asked Questions
The Solar Control Window Film Market was valued at USD 1.69 Billion in 2025 and is expected to reach USD 1.84 Billion in 2026 and USD 3.85 Billion by 2035.
The market is projected to grow at a CAGR of 8.58% during 2026–2035.
Asia Pacific holds the largest share, at 42.50% in 2025, led by China.
Vacuum coated films, ceramic films and construction lead, while nano-ceramic films, metallic films and automotive grow fastest.
Asia Pacific is also the fastest growing region, with a projected CAGR of 9.16% during 2026–2035.
