
Aluminium Market Report Scope & Overview:
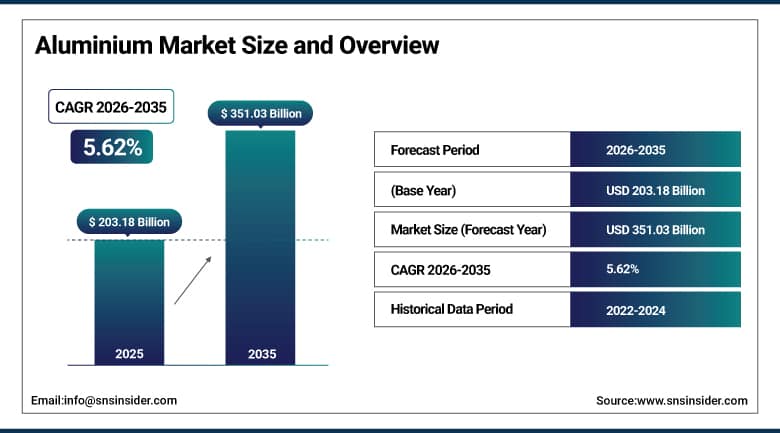
The Aluminium Market was valued at USD 203.18 Billion in 2025 and is expected to reach USD 214.60 Billion in 2026, before rising to USD 351.03 Billion by 2035. This represents a CAGR of 5.62% over 2026–2035. Aluminium is light, strong, corrosion resistant, highly conductive and fully recyclable, which makes it a core material for vehicles, buildings, beverage cans, power lines and electronics. Growth is supported by vehicle lightweighting, urban construction, grid expansion and a steady rise in the use of recycled metal. Recycled metal also reduces energy needs and emissions.
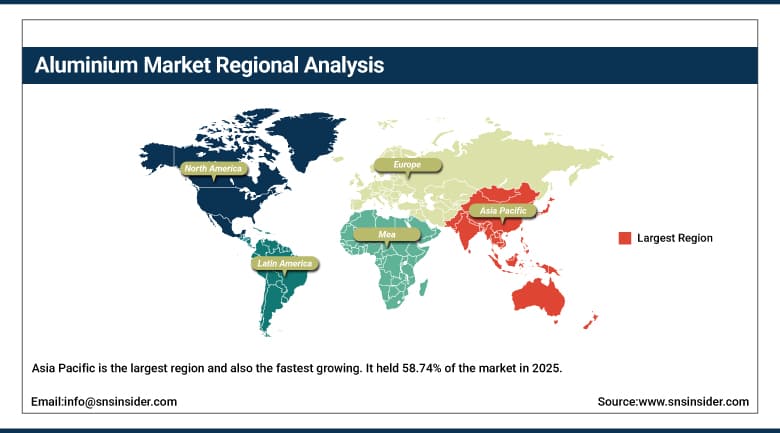
Asia Pacific accounted for the largest share of the market, at 58.74% in 2025, because China, India and Southeast Asia combine most of the world smelting capacity with large manufacturing and construction sectors. North America is the second largest region, supported by automotive, aerospace and packaging demand, followed by Europe, where recycling and low-carbon production are strategic priorities. Middle East and Africa has a growing smelter base, while Latin America is anchored by Brazil. Demand in all regions is supported by vehicle, housing and power projects planned well into the next decade.
To Get More Information On Aluminium Market - Request Free Sample Report
Key Report Takeaways
-
By form, extrusions held a 32.18% share in 2025, while castings are the fastest growing.
-
By end use, transportation held a 29.84% share in 2025, while electrical and electronics are the fastest growing.
-
By alloy series, the 1xxx series held a 20.37% share in 2025, while the 7xxx series is the fastest growing.
-
By region, Asia Pacific held a 58.74% share in 2025 and is also the fastest growing.
Market Trends and Insights
Producers are investing in low-carbon aluminium, using smelters powered by hydro, solar or wind electricity and, in some cases, inert anode technology that avoids direct process emissions. Buyers in the automotive, packaging and consumer goods sectors increasingly pay a premium for certified lower-carbon metal, and long-term supply agreements with traceable emission data are becoming common.
Recycling is taking a larger part of supply. Scrap collection, sorting technology and new rolling and remelting plants allow recycled metal to serve beverage can, automotive sheet and building uses at lower energy cost. Companies are also building capacity close to customers in North America and Europe to shorten supply chains and manage trade risk.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Vehicle lightweighting and electric vehicle production |
+2.14% |
Global, led by Asia Pacific, Europe and North America |
Medium term (2 to 4 years) |
|
Building construction and infrastructure growth |
+1.86% |
Asia Pacific, Middle East and Africa and Latin America |
Long term (4 years or more) |
|
Shift to recyclable aluminium packaging |
+1.37% |
Global |
Short term (2 years or less) |
|
Electrification, solar and grid build-out |
+1.02% |
Asia Pacific, Europe and North America |
Medium term (2 to 4 years) |
|
Growth of recycling and low-carbon aluminium |
+0.73% |
Europe and North America |
Long term (4 years or more) |
Vehicle Lightweighting and Electric Vehicle Production
Automakers use aluminium in body panels, closures, chassis parts, battery enclosures and thermal systems to reduce weight and extend driving range. Every kilogram removed from an electric vehicle lowers battery needs, which makes the metal attractive despite its higher price than steel. Large cast components produced in single pieces are simplifying assembly and expanding the metal content per car. Aerospace, rail and commercial vehicle builders also specify aluminium alloys for fuel efficiency and payload gains, which supports demand from several transport sectors at once.
Building Construction and Infrastructure Growth
Urban population growth and housing programs in Asia, the Middle East and Africa require large volumes of windows, doors, curtain walls, roofing, cladding and structural profiles. Aluminium resists corrosion, needs little maintenance and can be shaped into complex extrusions, which lowers lifetime cost for building owners. Energy codes that demand thermally broken frames and efficient facades also favor engineered aluminium systems. Public spending on bridges, airports and metro systems adds further consumption over the next decade. Retrofit and renovation programs add recurring orders. Rapid urbanization in emerging economies also supports demand.
Shift to Recyclable Aluminium Packaging
Beverage companies, food brands and retailers are replacing plastic with aluminium cans, bottles, trays and foil because the metal is recycled at high rates and keeps its value after use. Beer, soft drink and sparkling water producers are expanding can lines, and brand owners use aluminium to meet recycled content goals. Pharmaceutical blister foil and flexible packaging add steady demand. Deposit return systems in more countries raise collection rates and strengthen the supply of scrap for new packaging. Aluminium cans also benefit from lightweight shipping and strong brand appeal on shelves, which supports premium positioning.
Electrification, Solar and Grid Build-Out
Aluminium conductors carry a large share of overhead transmission and distribution power because they cost less and weigh less than copper for the same current. Solar module frames, mounting structures and trackers use extruded aluminium in large volumes, while wind and battery storage projects need housings and heat exchangers. Governments in many regions are funding grid upgrades and renewable capacity, and these programs create multi-year orders for cables, profiles and sheet. Utilities also value its lower weight during installation, which speeds line construction in remote areas and reduces tower costs.
Growth of Recycling and Low-Carbon Aluminium
Recycling needs only a small fraction of the energy used to make primary metal, so it lowers cost and emissions at the same time. Manufacturers of cans, cars and building products are signing supply contracts for recycled and low-carbon metal to meet climate targets. Investments in remelting, scrap sorting and dedicated recycling-and-rolling plants increase availability of qualified feedstock. Premium pricing for certified low-carbon products rewards producers that cut emissions early. Policy support such as extended producer responsibility and recycled content targets strengthens the business case for remelting plants.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High energy cost and carbon-intensive primary production |
-0.62% |
Europe, Asia Pacific and North America |
Long term (4 years or more) |
|
Trade barriers and tariffs |
-0.47% |
North America and Europe |
Short term (2 years or less) |
|
Volatile bauxite and alumina supply and prices |
-0.25% |
Global |
Medium term (2 to 4 years) |
|
Carbon border costs and capacity restrictions |
-0.16% |
Europe and Asia Pacific |
Medium term (2 to 4 years) |
High Energy Cost and Carbon-Intensive Primary Production
Smelting consumes very large amounts of electricity, and power can account for a major share of production cost. Smelters in regions with high or unstable electricity prices have curtailed output or shut down, while those relying on coal-based power face growing pressure from customers and investors. Cutting emissions requires heavy capital spending on new technology and clean power contracts, which smaller producers find difficult to finance. These costs reduce margins and slow the addition of new primary capacity. Power contracts are therefore a key focus for producers.
Trade Barriers and Tariffs
Import duties and quotas change trade flows and raise costs for downstream users. In July 2026, the United States issued a proclamation that keeps the 50.00% duty on primary aluminium but halves it for companies with approved plans to build or expand smelters in the country. Such measures leave buyers uncertain about sourcing and pricing, encourage stockpiling and diversion of shipments, and can reduce demand in sectors that depend on imported semi-finished products. Companies respond by relocating finishing steps or building local plants, but those moves take years to complete.
Volatile Bauxite and Alumina Supply and Prices
Aluminium production depends on bauxite mining and alumina refining, activities that are concentrated in a few countries. Weather, export rules, gas supply problems and mine licensing can interrupt shipments and send alumina prices sharply higher. Producers without integrated raw material supply face margin pressure when prices rise quickly and must hold larger inventories. Integration through acquisition is one response, but it takes time and capital. Long-term contracts help, though smaller processors have limited access to them. Price swings then pass into downstream selling prices.
Carbon Border Costs and Capacity Restrictions
The European Union began the definitive period of its carbon border adjustment mechanism in January 2026, which means importers of aluminium products must account for embedded emissions. Exporters from regions with carbon-intensive power may lose price competitiveness, and compliance requires detailed emissions reporting. Capacity limits in major producing countries also cap primary output, which restricts supply growth even where demand is strong. Aluminium makers are preparing by tracking emissions across plants and by sourcing cleaner power, yet the added reporting work raises administrative cost for exporters.
Aluminium Segment Analysis
By Form, Extrusions Dominate Aluminium Market; Castings to Register Fastest Growth.
Extrusions dominate the form axis, holding a 32.18% share in 2025. The process pushes heated metal through a die to create profiles with complex cross-sections, so one part can replace several joined pieces. Building frames, solar structures, vehicle components, rail cars and heat sinks all depend on these profiles. Extruders can customize shapes at low tooling cost, and finishing options such as anodizing and powder coating widen their appeal across industries. Standard die designs keep unit costs low.
Castings are expected to register the fastest growth, at a CAGR of 6.72% during 2026–2035. Electric vehicle makers are moving toward large structural castings that combine dozens of stamped parts, and battery housings, motor casings and thermal components are also cast. Improvements in vacuum casting and heat-treatable alloys raise strength and ductility. Fewer joints reduce assembly time and weight, which supports adoption. Castings also allow thin walls and complex cooling channels, which suits motors, inverters and compact housings.
By End Use, Transportation Dominates Aluminium Market; Electrical and Electronics to Register Fastest Growth.
Transportation dominates the end use axis, accounting for a 29.84% share in 2025. Cars, trucks, buses, trains, aircraft and ships use aluminium to cut weight, which saves fuel or extends electric driving range. Regulations on fleet emissions and efficiency keep manufacturers focused on lighter materials. The metal is also easy to form and recycle, so it fits high-volume production, and rising vehicle output in Asia adds to consumption every year. Standardized parts also simplify supply for builders and assemblers.
Electrical and electronics are projected to register the fastest growth, at a CAGR of 6.84% over 2026–2035. Power cables, busbars, transformers, solar equipment, charging stations and data center cooling systems all use aluminium for conductivity at low weight and cost. Grid expansion and the shift to renewable energy create large, steady orders. Consumer devices also use aluminium casings and heat spreaders for durability and thermal control. Manufacturers of consumer devices value the finish and thermal control that the metal provides.
By Alloy Series, 1xxx Series Dominates Aluminium Market; 7xxx Series to Register Fastest Growth.
The 1xxx series leads the alloy axis, with a 20.37% share in 2025. These grades contain at least 99.00% aluminium, giving excellent corrosion resistance, high thermal and electrical conductivity and easy forming. They are widely used for electrical conductors, chemical equipment, foil and reflectors. Because they are the base grades from which many other alloys are made, they benefit from broad demand across industries and from stable specifications. Wide availability keeps prices competitive. Specifications are also well established.
The 7xxx series is set to register the fastest growth, at a CAGR of 6.66% during 2026–2035. These zinc-based alloys offer the highest strength among common grades, which suits aircraft structures, high-performance vehicle parts, sporting goods and defense equipment. Rising aircraft production and demand for lighter automotive safety components are lifting orders. Improvements in joining and corrosion protection widen the range of uses. Machining and welding methods for these grades are also improving each year in several countries.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
62.14% |
|
North America |
United States |
81.48% |
|
Europe |
Germany |
24.63% |
|
Middle East and Africa |
United Arab Emirates |
33.41% |
|
Latin America |
Brazil |
51.39% |
Asia Pacific Aluminium Market
Asia Pacific is the largest region and also the fastest growing. It held 58.74% of the market in 2025 and is projected to expand at a CAGR of 5.93% over 2026–2035. China produces and consumes more aluminium than any other country, with large smelting, rolling and extrusion industries serving construction, vehicles, solar equipment and electronics. A capacity ceiling of 45 million tonnes, set by the Chinese government in 2017, shapes supply decisions. Strong export links to Europe and North America sustain output at large mills.
India is expanding smelting, rolling and extrusion capacity to serve infrastructure, power transmission and automotive needs, while Indonesia, Vietnam and Malaysia are attracting new smelter and processing projects. Japan and South Korea focus on high-grade sheet and automotive products. Rising incomes, urban housing and clean energy installations keep regional consumption on a firm upward path. Chinese producers are also moving smelting capacity toward provinces with abundant hydropower and renewable electricity, lowering the carbon content of metal. Recycling capacity is expanding in coastal regions as scrap supply grows.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Aluminium Market
North America accounted for 16.21% of the market in 2025. The United States market was valued at USD 26.84 Billion in 2025 and is expected to register a CAGR of 5.97% during 2026–2035. Demand is led by pickup trucks and sport utility vehicles, aerospace, beverage cans, building products and power infrastructure, and the region relies on both recycled metal and imports from Canada. Defense procurement and electrified trucks add further volume. Canada also supplies large volumes of primary metal to the region.
Canada is a major low-carbon producer using hydroelectric power, and regional assembly plants rely on extrusions and automotive components. New recycling and rolling plants, together with plans to restart or expand smelters, are being developed to reduce import dependence. Trade policy remains the largest source of uncertainty for buyers and producers across the region. Pickup trucks and sport utility vehicles remain the largest vehicle use. Federal clean energy and infrastructure programs support demand for transmission cables, solar structures, while the beverage industry continues to invest in can lines.
Europe Aluminium Market
Europe held 13.86% of the market in 2025. The region has a strong base of rolling mills, extruders and automotive and aerospace customers, and it leads in recycling and low-carbon product standards. Germany is the largest national market, driven by premium vehicles, machinery, construction and a dense supply chain of component makers. Automotive plants in Spain and Czechia add steady demand for sheet and castings. Strong standards for product safety and recyclability also encourage manufacturers to document material origin carefully.
Norway and Iceland provide smelting capacity based on renewable electricity, while Italy, France, Spain and Poland serve building and packaging markets. High electricity prices have reduced primary output in several countries, so imports and recycled metal make up a larger share of supply. Regulations on emissions and circularity continue to shape investment and product design. Energy efficiency standards for buildings and the revised packaging rules encourage recyclable aluminium solutions across the European Union and the United Kingdom, helping to sustain consumption despite weak construction in some markets.
Middle East and Africa Aluminium Market
Middle East and Africa accounted for 7.04% of the market in 2025. The Gulf states host large smelters built on low-cost natural gas power, with the United Arab Emirates leading the region through integrated production and downstream extrusion and rolling. Saudi Arabia, Bahrain and Oman add capacity, and the metal is exported to Asia, Europe and North America. Smelters in the Gulf benefit from long contracts for gas power, which gives a stable cost base. Export contracts to Asia support utilization.
Local construction and infrastructure programs in the Gulf are raising local use, and South Africa and Egypt support regional demand through building and manufacturing. Mozambique and Guinea are important for smelting and bauxite supply. Investment in downstream processing is rising as governments seek to capture more value from the metal produced in the region. Several Gulf producers have also announced plans to raise recycled content and develop low-carbon product lines for export customers. Together with growing local consumption, these initiatives strengthen the regional outlook.
Latin America Aluminium Market
Latin America held 4.15% of the market in 2025. Brazil leads the region with bauxite mining, alumina refining, smelting and a large beverage can industry that uses high shares of recycled metal. The country also has a well-established scrap collection system, which supports strong recycling rates and a competitive position in packaging. Local producers supply extrusions and sheet to regional construction and packaging customers. Mining operations in the north supply bauxite to refineries, which keeps raw material costs fairly predictable.
Argentina, Mexico, Chile and Colombia consume the metal in construction, automotive parts and electrical products. Currency swings, energy costs and logistics constraints affect investment decisions, but growth in vehicle assembly, housing and power transmission is expected to raise demand gradually through 2035. Brazil also exports bauxite and alumina to other regions. Trade agreements within the region help move semi-finished products across borders and support smaller processors. Mexico also benefits from nearshoring, which attracts automotive and appliance suppliers that use aluminium parts.
Competitive Landscape
The Aluminium Market is moderately fragmented. Integrated producers that control bauxite, alumina and smelting hold large positions in primary metal, while rolling and extrusion are served by a broad group of regional processors and specialty manufacturers. Competition centers on cost of power, access to raw materials, product quality, carbon footprint and proximity to customers.
Companies are announcing smelter expansions, recycling and rolling plants, acquisitions of upstream assets and partnerships for low-carbon products. Producers with renewable power and strong scrap networks are gaining pricing advantages, and regional processors compete through customized alloys and fast delivery. Consolidation along the value chain is expected to continue over the forecast period.
Aluminium Industry Leaders
1. Hindalco Industries Limited
2. Alcoa Corporation
3. Norsk Hydro ASA
4. Emirates Global Aluminium
5. Novelis Inc.
Companies Covered in this Report
-
Alcoa Corporation
-
Century Aluminum Company
-
Emirates Global Aluminium
-
Hindalco Industries Limited
-
Manaksia Aluminium Limited
-
National Aluminium Company Limited
-
Norsk Hydro ASA
-
Novelis Inc.
Recent Industry Developments
-
April 2025: Novelis confirmed that its recycling and rolling complex in Bay Minette, Alabama, is scheduled for commissioning in the second half of 2026.
-
May 2025: Emirates Global Aluminium confirmed plans for a primary aluminium smelter in Oklahoma with an annual capacity of 600,000 tons.
-
February 2026: National Aluminium Company launched its IA91 grade aluminium alloy ingot.
-
February 2026: Manaksia Aluminium announced aluminium sheets for high-security registration plates.
-
June 2026: Alcoa agreed to acquire South32 bauxite, alumina and aluminium assets in Australia, South Africa and Brazil.
-
August 2026: Hindalco secured ASI certification for its Baphlimali bauxite mine, the first in India to receive it.
-
October 2026: Norsk Hydro started construction of a new extrusion press line in Cressona, Pennsylvania.
Scope and Research Methodology
This study sizes the Aluminium Market for 2025 and forecasts it to 2035. The scope covers primary and secondary aluminium in the form of ingots, billets, extrusions, flat rolled products, castings and other semi-finished products, measured as sales value in USD at the producer or processor level. Bauxite, alumina and finished consumer goods are excluded, and the metal is counted once at the point where it enters a final-use sector. Values are reported on a calendar year basis, and trade is allocated to the country of final use. The historical period covers 2021 to 2024 and the forecast period covers 2026 to 2035.
Research began with a review of production and trade statistics, customs records, industry association reports, company filings, capacity trackers and technical standards. Demand was built from the bottom up using output of vehicles, buildings, packaging, power equipment and machinery, and it was cross-checked from the top down using smelter and mill production, scrap use and trade balances. Segment and regional shares were assigned from end-use consumption patterns, alloy usage and processing capacity in each geography. Metal prices were examined by region and product form to convert tonnage into value.
Findings were tested through discussions with smelter operators, rolling and extrusion managers, traders and procurement heads in end-use industries, and the forecast was stress-tested under scenarios for energy prices, trade policy, recycling rates and vehicle production. Growth rates reflect planned capacity, regulatory timelines and substitution trends. Values are expressed in USD, rounded to two decimals, and the analysis is updated when major policy or supply changes occur. Regional models consider income levels, construction cycles, vehicle production plans and access to scrap supply. Assumptions are reviewed regularly as conditions change. Estimates for each region were checked against national production and trade statistics where available, and adjustments were made for recycled supply.
Aluminium Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 203.18 Billion |
| Market Size by 2035 | USD 351.03 Billion |
| CAGR | CAGR of 5.62% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Form (Extrusions, Flat Rolled Products, Castings, and Others) • By End Use (Transportation, Building and Construction, Packaging, Electrical and Electronics, and Others) • By Alloy Series (1xxx, 3xxx, 5xxx, 6xxx, 7xxx, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Alcoa Corporation, Century Aluminum Company, Emirates Global Aluminium, Hindalco Industries Limited, Manaksia Aluminium Limited, National Aluminium Company Limited, Norsk Hydro ASA, Novelis Inc. |

Frequently Asked Questions
The market was valued at USD 203.18 Billion in 2025 and is expected to reach USD 214.60 Billion in 2026 and USD 351.03 Billion by 2035.
The market is projected to grow at a CAGR of 5.62% during 2026–2035.
Asia Pacific holds the largest share, at 58.74% in 2025, led by China.
Extrusions, transportation and the 1xxx series lead, while castings, electrical and electronics, and the 7xxx series grow fastest.
Vehicle lightweighting, construction and infrastructure, recyclable packaging, electrification and grid expansion, and growth in recycling and low-carbon metal.
