
Space Launch Services Market Report Scope & Overview:
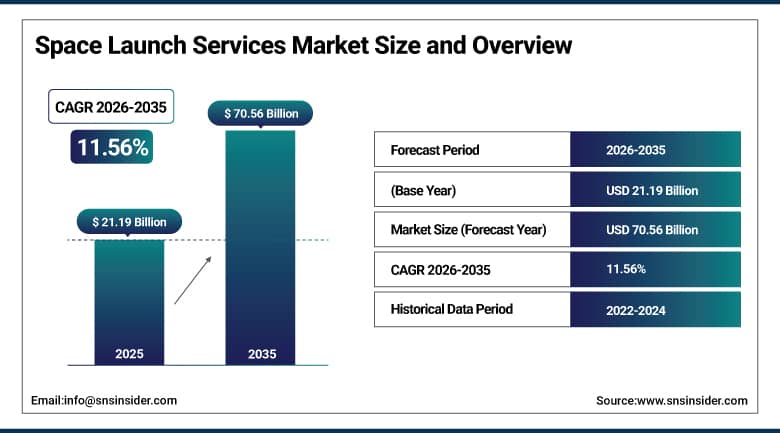
The Space Launch Services Market was valued at USD 21.19 Billion in 2025 and is expected to reach USD 70.56 Billion by 2035, growing at a CAGR of 11.56% from 2026 to 2035.
Space launch services market has been exhibiting tremendous growth due to the increased use of satellite constellations for providing broadband communication, Earth observation and navigation. Space launch services refer to the commercial launch of transportation systems using rockets for launching satellites, cargo, manned spacecrafts and scientific payloads to Earth’s orbit and beyond. Additionally, market expansion is being driven by the participation of private launch service providers in the business sector, which has contributed towards innovation in space launch technology, reduced launch costs, increased government spending on national security programs and civilian space explorations, and commercialization of reusable heavy-lift launch vehicle capabilities.
The Union of Concerned Scientists reported over 7,000 active satellites in orbit by mid-2023, a figure expected to surpass 15,000 by 2030, with companies such as ExoAnalytic Solutions and LeoLabs capitalizing on this trend by offering real-time tracking and space situational awareness services supporting the growing volume of orbital assets.
To Get More Information On Space Launch Services Market - Request Free Sample Report
Space Launch Services Market Trends
- Rising multi-orbit constellation programs from defense and Earth-observation agencies are accelerating demand for mission-flexible launch services, pushing companies to develop rapid-response boosters and reusable propulsion modules.
- Growing commercialization of reusable heavy-lift launch vehicle capabilities is driving a decisive industry shift as companies compete to scale reusable rocket technology and reduce per-launch costs.
- Increasing adoption of digital twins for mission planning is improving launch reliability and reducing pre-launch integration timelines across both government and commercial payload customers.
- Expanding post-launch services, including on-orbit servicing, debris removal, and space situational awareness tracking, are broadening the addressable scope of the launch services value chain.
- Strategic partnerships among launch providers, satellite manufacturers, and government space agencies are supporting development of increasingly high-cadence, cost-efficient orbital access solutions.
The U.S. Space Launch Services Market Outlook
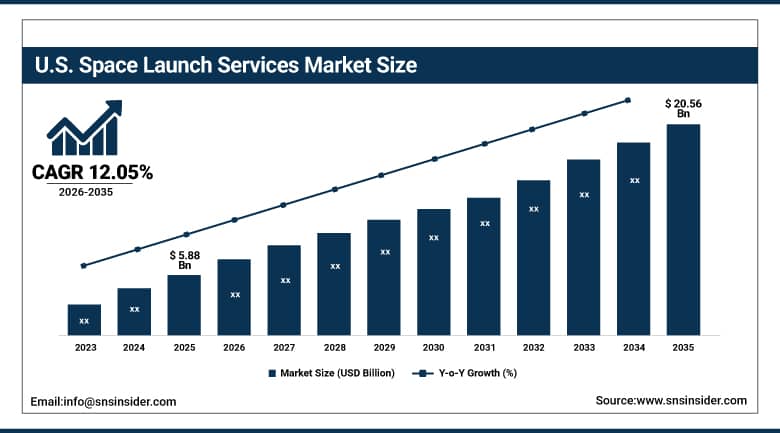
The U.S. space launch services market was valued at USD 5.88 Billion in 2025 and is projected to reach USD 20.56 Billion by 2035, growing at a CAGR of 12.05% during 2026–2035.
The country's leading commercial launch providers continue to expand orbital launch capacity, driven by SpaceX's market leadership in reusable launch vehicles and strong government-backed programs including the National Security Space Launch initiative. Growing private launch service provider entry into the industry, including companies developing small- and medium-class launch vehicles, combined with sustained NASA and U.S. Space Force investment, continues to reinforce sustained domestic demand for advanced orbital launch capability across the country's government and rapidly expanding commercial space sector.
The U.S. space launch services market size is estimated at USD 5.88 billion in 2025 and predicted to be worth around USD 20.56 billion by 2035, with rising market rivalry among new private launch service providers, including companies such as Rocket Lab and Firefly Aerospace, expected to lower launch costs and expand access to space for a broader variety of customers.
Space Launch Services Market Segment Analysis
- By Payload, satellite dominated the market with a 46.80% share in 2025, while human spacecraft is the fastest-growing payload segment with a CAGR of 13.40% from 2026–2035.
- By Orbit, low earth orbit (LEO) dominated the market with a 63.00% share in 2025, while geostationary orbit (GEO) is the fastest-growing orbit segment with a CAGR of 12.60% from 2026–2035.
- By Service Type, pre-launch services dominated the market with a 58.00% share in 2025, while post-launch services is the fastest-growing service type segment with a CAGR of 12.30% from 2026–2035.
- By End User, government & military dominated the market with a 52.00% share in 2025, while commercial is the fastest-growing end user segment with a CAGR of 13.80% from 2026–2035.
By Payload, satellite dominated the space launch services market, while human spacecraft is the fastest-growing segment.
The satellite segment dominated the space launch services market with a revenue share of 46.80% in 2025. Satellite payloads remain the dominant category owing to increasing investments in communication, Earth observation, and navigation constellations across both government and commercial sectors, driven by rising need for broadband connectivity in underserved regions alongside growing defense requirements for persistent surveillance and secure communications.
The human spacecraft segment is anticipated to register the fastest CAGR of 13.40% during the forecast period 2026-2035. Growing commercial crew transportation activity supporting the International Space Station and emerging space tourism ventures, combined with expanding national civil space exploration programs targeting lunar and deep-space missions, is driving strong growth in crewed launch service demand.
By Orbit, low earth orbit (LEO) dominated the space launch services market, while geostationary orbit (GEO) is the fastest-growing segment.
The low earth orbit (LEO) was the most influential orbit segment with 63.00% share of revenue generated from the space launch service industry in 2025. LEO is the leading orbit due to the high demand of satellite constellations, earth observation, and rapid deployment system suited for communication and defense purposes. This highlights the change in structure of the space launch service industry towards large constellation of broadband and imaging satellites.
The geostationary orbit (GEO) segment is expected to witness a CAGR of 12.60% during the forecast period 2026-2035. Growing demand for GEO-based communications and missile-warning satellite programs among government and defense customers is driving renewed launch service demand for heavier, higher-orbit payloads requiring specialized launch vehicle configurations and extended mission planning capability.
By Service Type, pre-launch services dominated the space launch services market, while post-launch services is the fastest-growing segment.
Pre-launch Services was the largest player in the space launch services market and accounted for a revenue share of 58.00% in 2025. Pre-launch Services continues to be the leading category and provides end-to-end mission planning and integration of payloads and compliance with regulations that are necessary for launching payloads into orbit.
The post-launch services segment is swiftly growing with a CAGR of 12.30% throughout the forecast period 2026-2035. Companies like Northrop Grumman and Astroscale are exploring the field of on-orbit servicing and space debris removal technologies, thus making their list of services after launch more extensive in light of the increasing number of satellites that have been launched into orbit.
By End User, government & military dominated the space launch services market, while commercial is the fastest-growing segment.
The government & military segment dominated the space launch services market with a revenue share of 52.00% in 2025. Government and military end users remain the dominant category, driven by sustained national security priorities, defense satellite programs, and civil space exploration initiatives requiring assured access to space across major spacefaring nations.
The commercial segment is expected to register the fastest CAGR of 13.80% during the forecast period 2026-2035. The entry of private launch service providers into the industry, leading to new space launch technologies and a fall in launch costs, is driving rapid commercial segment growth, as an expanding range of businesses increasingly access space for telecommunications, Earth observation, and emerging space tourism applications.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
France |
28.60% |
|
Asia Pacific |
China |
44.80% |
|
Middle East & Africa |
UAE |
26.80% |
|
Latin America |
Brazil |
38.60% |
North America Space Launch Services Market Insights
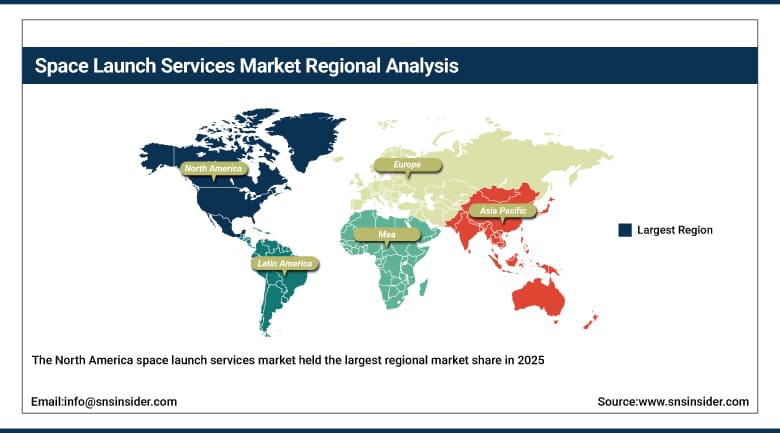
The North America space launch services market held the largest regional market share in 2025 owing to the presence of dominant commercial launch providers such as SpaceX and United Launch Alliance, combined with robust government investment through NASA and the U.S. Space Force supporting sustained national security and civil space priorities.
The US was the leading country within the North America’s market in 2025, fueled by SpaceX's market leadership in reusable launch vehicles and strong government-backed programs including the National Security Space Launch initiative. Canada is contributing to regional growth through its own expanding satellite manufacturing and space technology investment.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Space Launch Services Market Insights
Europe space launch services market constituted an important factor in 2025. The reason behind this is the significant investments made in terms of civil and commercial space programs, along with the availability of top European launch service providers in the region.
France is one of the major markets in Europe owing to Arianespace's headquarters presence and the country's central role in European Space Agency launch programs. Other countries such as Germany and Italy are also contributing to market growth through expanding satellite manufacturing capability and space technology research investment.
Asia Pacific Space Launch Services Market Insights
Asia Pacific market is expected to expand at the fastest CAGR between 2026 and 2035. The market growth is driven by expanding domestic launch vehicle development, growing satellite constellation deployment, and increasing government space program investment across the region's major and emerging spacefaring economies.
China is one of the main growth drivers in the Asia Pacific space launch services market, owing to its rapidly expanding domestic launch vehicle manufacturing capability through providers such as China Great Wall Industry Corporation. India and Japan are also contributing to regional growth through expanding national space agency programs and growing private launch service provider development, including companies such as Skyroot Aerospace and Agnikul Cosmos.
Middle East & Africa and Latin America Space Launch Services Market Insights
Middle East & Africa and Latin American regions are gradually expanding space launch services adoption as national space program investment grows across both regions, supported by increasing regional interest in satellite communications and Earth observation capability.
Brazil is set to be a prominent Latin American market fueled by its Alcântara Launch Center infrastructure and growing domestic space program investment. The Middle East & Africa region has UAE and Saudi Arabia investing in space exploration and satellite deployment programs as part of broader economic diversification strategies supporting regional technology development.
Market Dynamics
Growth Drivers: Rising satellite constellation deployment and reusable launch technology driving market growth
The increasing deployment of satellite constellations for broadband connectivity, Earth observation, and navigation services requiring reliable and cost-effective access to orbit is among the primary drivers of the Space Launch Services Market. Private launch service providers' entry into the industry has led to new space launch technologies and a fall in launch costs, ushering in a new stage in the market's development that continues expanding orbital access to a broader range of government and commercial customers.
Rising need for broadband connectivity in underserved regions, coupled with growing defense requirements for persistent surveillance and secure communications, continues to catalyze demand for satellite launch missions. Increasing government expenditure on space exploration, growing multi-orbit constellation programs from defense and Earth-observation agencies, and rising commercialization of reusable heavy-lift launch vehicle capabilities are further supporting demand across the forecast period.
Restraints: High mission costs and launch schedule uncertainty limiting market expansion
The large costs involved in launching vehicles into orbit space is one of the factors that restricts the development of this market, especially in cases of national security-related cargo, as such a factor restricts the launching frequency even as costs continue reducing through reusable vehicles.
Additionally, launch schedule uncertainty tied to technical readiness, weather conditions, and range availability at major spaceports can create significant delays for time-sensitive commercial and government missions. The technical complexity of developing and qualifying new reusable propulsion systems further requires substantial research and development investment that can constrain smaller launch providers competing against well-capitalized established players.
Opportunities: Expansion of post-launch servicing and emerging launch provider competition creating new growth avenues
The rapid emergence of post-launch services like on-orbit servicing and orbital debris clearing, increasing number of developments in small-to-medium launch vehicles by private firms, and increasing expenditure by governments on space exploration missions are some of the aspects that would provide a lot of potential to the space launch services market. Increased competition amongst new private launch service providers is projected to reduce launch costs and increase access to space for more diverse clientele.
There is a considerable growth opportunity in the continued development of digital twin mission planning and automated integration lines that improve launch cadence and reliability. The expansion of national space program investment and domestic launch vehicle development in emerging markets across Asia Pacific and the Middle East is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
- 2025: Blue Origin successfully conducted the first orbital launch of its New Glenn heavy-lift rocket, marking the company's entry into commercial and government orbital launch service competition.
- 2025: SpaceX continued its Starship orbital test flight program, advancing toward operational reusable heavy-lift capability intended to support both satellite constellation deployment and deep-space missions.
- 2026: Rocket Lab advanced development of its Neutron rocket, targeting the medium-lift launch market segment with a reusable first stage designed to compete for national security and commercial satellite constellation contracts.
- 2026: Arianespace continued ramping up commercial launch cadence for its Ariane 6 vehicle, expanding European sovereign and commercial launch capacity following the rocket's operational introduction.
Space Launch Services Market key players are:
- SpaceX
- Arianespace SA
- United Launch Alliance, LLC
- Northrop Grumman Corporation
- Rocket Lab USA, Inc.
- Blue Origin, LLC
- NewSpace India Limited (ISRO)
- China Great Wall Industry Corporation
- Relativity Space, Inc.
- Firefly Aerospace, Inc.
- Mitsubishi Heavy Industries, Ltd.
- Roscosmos State Corporation
- Sierra Space Corporation
- Astra Space, Inc.
- Orienspace Technology Co., Ltd.
- ispace, inc.
- Skyroot Aerospace Pvt. Ltd.
- Agnikul Cosmos Pvt. Ltd.
- Astroscale Holdings Inc.
- ExoAnalytic Solutions, Inc.
Space Launch Services Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 21.19 Billion |
| Market Size by 2035 | USD 70.56 Billion |
| CAGR | CAGR of 11.56% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Payload (Satellite, Human Spacecraft, Cargo, Testing Probes) • By Orbit (Low Earth Orbit (LEO), Geostationary Orbit (GEO), Others) • By Service Type (Pre-Launch Services, Post-Launch Services) • By End User (Government & Military, Commercial) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | SpaceX, Arianespace SA, United Launch Alliance, LLC, Northrop Grumman Corporation, Rocket Lab USA, Inc., Blue Origin, LLC, NewSpace India Limited (ISRO), China Great Wall Industry Corporation, Relativity Space, Inc., Firefly Aerospace, Inc., Mitsubishi Heavy Industries, Ltd., Roscosmos State Corporation, Sierra Space Corporation, Astra Space, Inc., Orienspace Technology Co., Ltd., ispace, inc., Skyroot Aerospace Pvt. Ltd., Agnikul Cosmos Pvt. Ltd., Astroscale Holdings Inc., ExoAnalytic Solutions, Inc. |
Frequently Asked Questions
The Space Launch Services Market is expected to grow at a CAGR of 11.56% from 2026 to 2035.
The Space Launch Services Market was valued at USD 21.19 Billion in 2025.
The market is driven by increasing deployment of satellite constellations for broadband connectivity, Earth observation, and navigation services requiring reliable, cost-effective orbital access.
The Satellite segment dominated the Space Launch Services Market in 2025, accounting for approximately 46.80% market share.
The North America region dominated the Space Launch Services Market in 2025.
