
High Altitude Pseudo Satellite Market Report Scope & Overview:
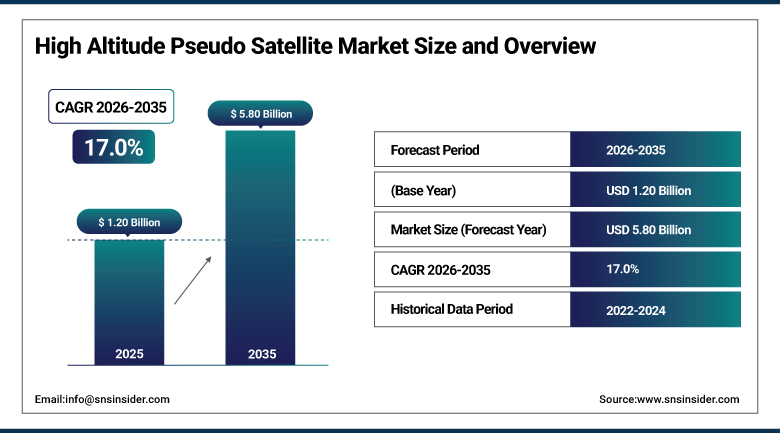
The High Altitude Pseudo Satellite Market was valued at USD 1.20 Billion in 2025 and is expected to reach USD 5.80 Billion by 2035, growing at a CAGR of 17.0% from 2026–2035.
High altitude pseudo satellites, HAPS, are solar-powered aircraft and airships that loiter in the stratosphere above 18 to 20 kilometers, well above commercial air traffic and weather, providing satellite-like communications, imaging, and sensing coverage at a fraction of the cost of launching an actual satellite. Unlike a satellite, a HAPS can be recovered, repaired, and repositioned, and unlike a conventional drone, it can stay aloft for weeks or months at a time. The technology has spent two decades mostly in flight-test programs, but 2025 brought several genuine endurance and commercial milestones.
An Airbus-operated Zephyr high-altitude platform station set a new endurance record in 2025, flying for 67 days, 6 hours, and 52 minutes from a purpose-built launch facility in Laikipia County, Kenya, crossing seven flight information regions along the way. The flight underscored just how far solar-electric HAPS technology has come since the aircraft's earliest test flights two decades ago, and positioned the company's Aalto HAPS subsidiary for a targeted commercial service launch as soon as 2026.
To Get more information High Altitude Pseudo Satellite Market - Request Free Sample Report
High Altitude Pseudo Satellite Market Trends
-
Direct-to-device connectivity is emerging as the technology's clearest near-term commercial application, letting a HAPS act as a cell tower in the sky that connects standard smartphones without any special ground equipment.
-
Fixed-wing solar-electric aircraft and lighter-than-air stratospheric airships are advancing along parallel tracks, each suited to different mission profiles, wide-area coverage for fixed-wing platforms versus persistent station-keeping for airships.
-
Telecom operators and satellite companies are increasingly investing directly in HAPS developers rather than treating the technology as a competitor, viewing it as a complementary layer that fills coverage gaps terrestrial towers and orbital satellites both struggle to reach cost-effectively.
-
Regulatory pathways for commercial HAPS operations remain a genuine bottleneck, with airworthiness certification handled largely on a case-by-case basis that creates multi-year backlogs for developers seeking routine commercial clearance.
-
Defense and government demand continues centering on persistent surveillance and border monitoring applications, where a HAPS offers real-time coverage at a fraction of the cost of maintaining an equivalent satellite constellation.
U.S. High Altitude Pseudo Satellite Market Outlook
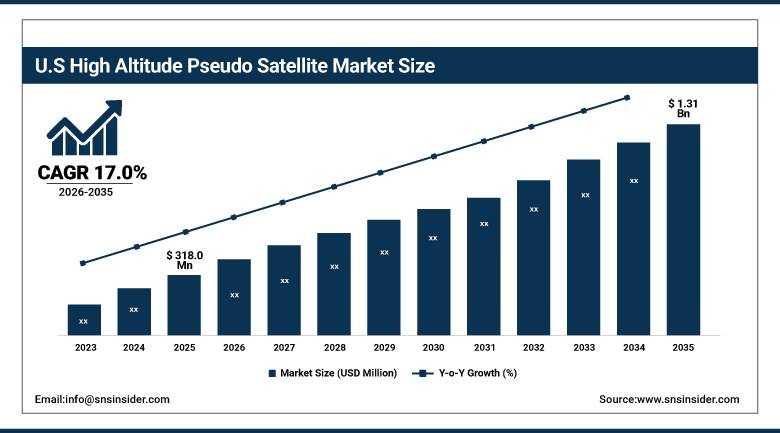
The U.S. High Altitude Pseudo Satellite Market was valued at approximately USD 318.0 Million in 2025 and is expected to reach approximately USD 1.31 Billion by 2035, growing at a CAGR of approximately 17.0%.
The United States hosts several of the most advanced HAPS developers in the world, spanning both fixed-wing and airship approaches, alongside deep defense-sector demand for persistent surveillance and border monitoring applications. Domestic test ranges in states like New Mexico and Arizona have become key proving grounds for endurance and payload testing ahead of eventual commercial and defense deployment. Growing telecom operator interest in direct-to-device connectivity is adding a substantial new commercial demand layer on top of the market's traditional defense and government base.
Sceye, a U.S. company based in New Mexico, completed a 12-day, 6,400-mile stratospheric flight of its helium-filled SE2 airship in 2025, traveling from New Mexico to the coast of Brazil while holding position and altitude for more than 88 hours over several target areas. The mission concluded the company's Endurance Program and cleared the way for pre-commercial test flights, positioning Sceye as one of the most advanced U.S.-based HAPS developers pursuing telecom and environmental-monitoring applications.
High Altitude Pseudo Satellite Market Segment Analysis
-
By Platform, the Unmanned Aerial Vehicles segment dominated the High Altitude Pseudo Satellite Market with approximately 59.9% share in 2025, while the Airships segment is the fastest growing with a CAGR of approximately 25.5%.
-
By Payload/Application, the Communication Systems segment dominated the High Altitude Pseudo Satellite Market with approximately 42.6% share in 2025, while the Weather & Environmental Sensors segment is the fastest growing with a CAGR of approximately 23.6%.
-
By Power Source, the Solar-Electric segment dominated the High Altitude Pseudo Satellite Market with approximately 67.1% share in 2025, while the Hydrogen Fuel Cell/Hybrid segment is the fastest growing with a CAGR of approximately 26.2%.
-
By End User, the Defense & Government segment dominated the High Altitude Pseudo Satellite Market with approximately 46.7% share in 2025, while the Commercial segment is the fastest growing with a CAGR of approximately 25.5%.
-
By Deployment, the Land-Based Operations segment dominated the High Altitude Pseudo Satellite Market with approximately 44.0% share in 2025, while the Disaster-Prone Areas segment is the fastest growing with a CAGR of approximately 24.6%.
By Platform, unmanned aerial vehicles dominate, airships grow fastest
Fixed-wing unmanned aerial vehicles held the largest share of the platform segment in 2025, driven by their proven solar-electric designs capable of carrying meaningful payloads across multi-month flights. Their ability to cover wide areas while maintaining altitude through day-night cycles has made this platform type the most mature and commercially advanced HAPS category.
Airships are growing fastest as their lighter-than-air, helium-filled design proves particularly well suited to persistent station-keeping over a fixed geographic area, a mission profile that matters enormously for telecom coverage and environmental monitoring applications. That station-keeping advantage over fixed-wing aircraft, which must continuously fly to stay aloft, is drawing growing developer and investor interest toward the airship approach.
By Payload/Application, communication systems dominates, weather & environmental sensors grows fastest
Communication systems accounted for the largest application share in 2025, reflecting the industry's primary near-term commercial focus on direct-to-device connectivity and telecom coverage extension. Telecom operators view HAPS-based communication payloads as a genuinely practical way to fill rural and remote coverage gaps that terrestrial towers can't reach cost-effectively.
Weather and environmental sensors are the fastest-growing application as climate monitoring, disaster response, and agricultural applications increasingly value the persistent, wide-area coverage a stratospheric platform can provide relative to either satellites or conventional aircraft. Growing global attention to climate resilience and disaster preparedness is expanding the addressable market for this application faster than the broader HAPS market overall.
By Power Source, solar-electric dominates, hydrogen fuel cell/hybrid grows fastest
Solar-electric power systems held the large majority of the power-source segment in 2025, remaining the most proven and widely deployed propulsion approach across nearly every commercially advanced HAPS program. Daytime solar charging paired with battery storage for overnight operation has powered every major endurance record the industry has set to date.
Hydrogen fuel cell and hybrid power systems are growing fastest as developers look for propulsion approaches that reduce dependency on battery weight and daylight availability, both meaningful constraints for solar-electric platforms operating at higher latitudes or during winter months. That extended operational flexibility makes hydrogen and hybrid systems particularly attractive for polar and high-latitude mission profiles that solar-electric platforms currently struggle to serve reliably.
By End User, defense & government dominates, commercial grows fastest
Defense and government applications accounted for the largest end-user share in 2025, reflecting decades of military and government interest in persistent surveillance, border monitoring, and intelligence-gathering capabilities that HAPS platforms can deliver more affordably than satellite alternatives. This demand base has funded much of the technology's early development and continues anchoring overall market revenue.
Commercial applications are the fastest-growing end-user category as telecom operators and satellite companies move from evaluating HAPS technology to actively investing in and partnering with developers. Direct-to-device connectivity in particular is opening a genuinely new commercial revenue stream that didn't meaningfully exist for the industry even a few years ago.
By Deployment, land-based operations dominates, disaster-prone areas grows fastest
Land-based operations held the largest share of the deployment segment in 2025, covering the majority of current test flights, commercial pilots, and defense applications that operate over continental land areas. Established launch infrastructure and airspace regulatory frameworks both remain more developed for land-based operations than for maritime or polar deployment.
Disaster-prone area deployment is growing fastest as governments and humanitarian organizations recognize HAPS platforms' ability to restore emergency communications and provide real-time situational awareness following natural disasters that damage terrestrial infrastructure. That emergency-response value proposition is drawing increasing government and NGO interest independent of the technology's broader commercial telecom applications.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
78.0% |
|
Europe |
United Kingdom |
26.0% |
|
Asia Pacific |
China |
39.0% |
|
Latin America |
Brazil |
36.0% |
|
Middle East & Africa |
UAE |
32.0% |
North America High Altitude Pseudo Satellite Market Insights
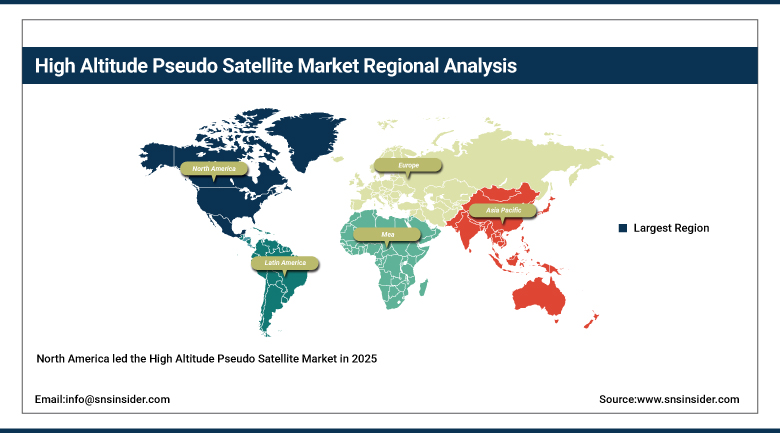
North America led the High Altitude Pseudo Satellite Market in 2025, anchored by the United States' concentration of well-funded HAPS developers and deep defense-sector demand for persistent surveillance and border monitoring applications. Domestic test ranges and a strong base of aerospace engineering talent both support the region's position at the forefront of HAPS commercialization.
Canada contributes a smaller but growing share through its own emerging aerospace research activity, while Mexico's market remains largely nascent, without significant domestic HAPS development programs of its own. Cross-border defense and telecom partnership activity, particularly between U.S. developers and North American government agencies, ties much of the region's demand together.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific High Altitude Pseudo Satellite Market Insights
Asia Pacific is expected to register the fastest regional growth through 2035, driven by China's rapid adoption of HAPS technology for communication, surveillance, and environmental monitoring applications backed by significant state investment. India's growing aerospace and defense sector is drawing early-stage interest as well, supported by government priorities around rural connectivity and border surveillance.
Japan's SoftBank-backed HAPSMobile program has positioned the country as an early commercial testing ground for stratospheric telecom connectivity, while South Korea's aerospace sector is showing growing interest in the technology. A Japanese consortium's substantial 2024 investment in Airbus's Aalto HAPS subsidiary, aimed at commercializing connectivity services across Asia, reflects the region's genuine commercial ambition around this technology.
Europe High Altitude Pseudo Satellite Market Insights
Europe represents a technically advanced High Altitude Pseudo Satellite market, anchored by the United Kingdom's role as home to Airbus's Zephyr program and its Farnborough-based payload development operations. Deep aerospace engineering expertise and established defense-sector relationships give the region a genuine technical leadership position even as commercial deployment continues advancing gradually.
France and Germany contribute meaningful research and defense-sector demand as well, with Airbus's broader European aerospace footprint supporting continued HAPS development across the region. EU-level interest in stratospheric platforms for both defense and civilian connectivity applications continues growing alongside national-level programs.
MEA & Latin America High Altitude Pseudo Satellite Market Insights
The Middle East and Africa host a smaller but strategically significant share of the High Altitude Pseudo Satellite market, with the UAE driving demand through smart-city and defense-related interest in stratospheric platform technology. Kenya has emerged as an unexpectedly important regional player, hosting Airbus's purpose-built Zephyr launch facility and establishing an early regulatory pathway for commercial HAPS operations.
Latin America remains an early-stage market, with Brazil drawing growing attention as a test and demonstration site for stratospheric flight programs, including transcontinental endurance missions launched from North American test facilities. Regional government interest in rural connectivity and disaster response applications is expected to support longer-term market development.
Market Dynamics
Growth Drivers: Rural connectivity demand and defense surveillance needs fueling adoption
Growing demand for rural and remote broadband connectivity is one of the clearest forces behind rising HAPS investment, as telecom operators look for cost-effective ways to extend coverage into areas where building terrestrial towers isn't economically viable. A single HAPS platform can cover an area equivalent to hundreds of ground towers, giving operators a genuinely compelling economic case for the technology.
Persistent defense and government demand for cost-effective surveillance and border monitoring adds a second major driver, as HAPS platforms offer real-time coverage at a fraction of the cost of maintaining an equivalent satellite constellation. Rising global geopolitical tension continues reinforcing government interest in this capability independent of the technology's civilian and commercial applications.
Restraints: Regulatory certification delays and technical durability limitations limiting broader adoption
Regulatory certification remains a genuine bottleneck for the industry, since airworthiness approval for stratospheric platforms is still handled largely on a case-by-case basis that creates multi-year backlogs and slows the transition from flight-test programs into routine commercial operation. That regulatory uncertainty makes it harder for developers to plan capital investment and secure long-term commercial contracts.
Technical durability limitations add a further restraint, since operating continuously in the harsh stratospheric environment, extreme temperature swings, UV exposure, and high winds, places enormous stress on lightweight aircraft structures designed to minimize weight above all else. That fundamental tension between durability and weight continues to cap how long even the most advanced platforms can reliably operate before requiring maintenance.
Opportunities: Direct-to-device connectivity and disaster response applications opening new growth avenues
Direct-to-device connectivity offers a genuinely significant near-term commercial opportunity, letting a HAPS platform function as a cell tower in the sky that connects standard smartphones without requiring any special ground equipment. Developers that successfully commercialize this capability are positioned to capture substantial telecom operator investment as coverage-gap economics continue favoring stratospheric solutions over additional ground infrastructure.
Disaster response and emergency communications applications represent a second significant opportunity, as governments and humanitarian organizations increasingly value HAPS platforms' ability to restore connectivity and provide situational awareness when terrestrial infrastructure fails. Developers that build dedicated disaster-response capability and government relationships are positioned to capture growing public-sector investment in resilient emergency communications infrastructure.
Recent Developments:
-
January 2025: Aalto's Zephyr completed a 13-day stratospheric flight testing direct-to-device 4G/5G connectivity technology developed at the company's Farnborough facility.
-
June 2024: A Japanese consortium led by NTT Docomo and Space Compass committed USD 100 million to Aalto HAPS to commercialize connectivity services across Asia, targeting a 2026 introduction.
-
Early 2025: Kea Aerospace's Atmos Mk1b reached an altitude of more than 17 kilometers and flew for 8 hours and 20 minutes during a test flight launched from South Island, New Zealand.
-
2025: BAE Systems continued flight testing of its Phasa-35 HAPS platform in New Mexico, building on the aircraft's 2020 maiden flight.
High Altitude Pseudo Satellite Market Key Players
-
Airbus SE (Aalto HAPS / Zephyr)
-
Sceye Inc.
-
BAE Systems plc
-
AeroVironment, Inc.
-
The Boeing Company
-
Northrop Grumman Corporation
-
Thales Group
-
Lockheed Martin Corporation
-
SoftBank Corp. (HAPSMobile)
-
Kea Aerospace Ltd.
-
RTX Corporation
-
World View Enterprises, Inc.
-
NTT DOCOMO, Inc. / Space Compass Corporation
-
China Aerospace Science and Technology Corporation (CASC)
-
Stratospheric Platforms Limited
-
Thales Alenia Space
-
QinetiQ Group plc
-
Dawn Aerospace
-
TCOM, L.P.
-
IHI Corporation
High Altitude Pseudo Satellite Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.20 Billion |
| Market Size by 2035 | USD 5.80 Billion |
| CAGR | CAGR of 17.0% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Platform (Unmanned Aerial Vehicles, Airships, Balloon Systems) • by Payload/Application (Communication Systems, Imaging Systems, Surveillance & Reconnaissance, Weather & Environmental Sensors, Navigation & Positioning Systems) • by Power Source (Solar-Electric, Hydrogen Fuel Cell, Hybrid, Lithium-Ion Battery) • by End User (Defense & Government, Commercial, Civilian Government) • by Deployment (Land-Based Operations, Maritime Operations, Polar Regions, Disaster-Prone Areas) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | Airbus SE (Aalto HAPS / Zephyr), Sceye Inc., BAE Systems plc, AeroVironment, Inc., The Boeing Company, Northrop Grumman Corporation, Thales Group, Lockheed Martin Corporation, SoftBank Corp. (HAPSMobile), Kea Aerospace Ltd., RTX Corporation, World View Enterprises, Inc., NTT DOCOMO, Inc. / Space Compass Corporation, China Aerospace Science and Technology Corporation (CASC), Stratospheric Platforms Limited, Thales Alenia Space, QinetiQ Group plc, Dawn Aerospace, TCOM, L.P., IHI Corporation |
Frequently Asked Questions
The High Altitude Pseudo Satellite Market is expected to grow at a CAGR of 17.0% from 2026 to 2035.
The High Altitude Pseudo Satellite Market was valued at USD 1.20 Billion in 2025.
Growing telecom operator demand for rural connectivity coverage combined with persistent defense and government need for cost-effective surveillance capability.
North America dominated the High Altitude Pseudo Satellite Market in 2025, while Asia Pacific is the fastest-growing region.
