
Universal Flash Storage Market Report Scope & Overview:
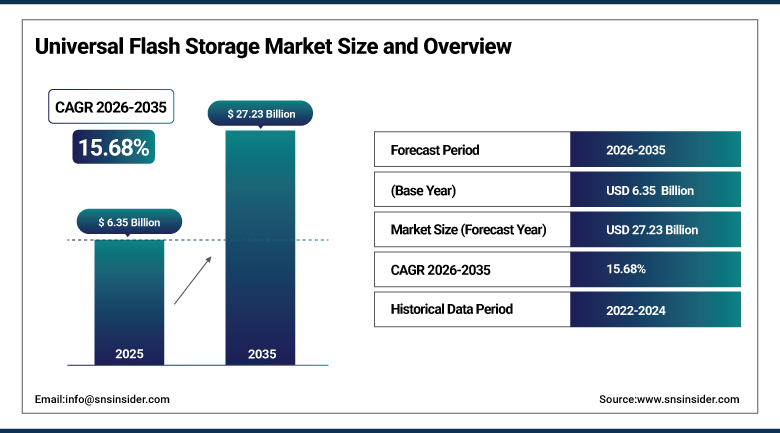
The Universal Flash Storage Market size was valued at USD 6.35 Billion in 2025 and is expected to reach USD 27.23 Billion by 2035, growing at a CAGR of 15.68% from 2026-2035.
The Universal Flash Storage Market covers flash memory devices that use a serial interface to deliver fast, low-power storage in phones, cars and other connected products. Compared with older eMMC storage, UFS reads and writes data at far higher speeds and handles several commands at once. Each new standard raises throughput, and on-device artificial intelligence now needs that bandwidth to load large models quickly. Automotive makers also adopt UFS for infotainment and driver assistance. Memory price swings and higher cost than eMMC remain challenges. A small group of memory makers and controller suppliers shapes supply, and demand is rising across consumer and industrial devices.
⮞In February 2026, JEDEC published the UFS 5.0 standard and its host controller specification, supporting speeds of up to 10.8 GB/s over two M-PHY lanes. The release shows how quickly the interface is advancing to serve data-heavy mobile and automotive workloads.
To Get more information Universal Flash Storage Market - Request Free Sample Report
Universal Flash Storage Market Trends
-
Rapid move from UFS 3.1 to UFS 4.1 and UFS 5.0 for on-device AI
-
Growing use of automotive-grade UFS in infotainment, cockpit and driver assistance systems
-
Higher storage capacities of 512 GB and 1 TB in premium smartphones
-
Layered 3D NAND with 300 or more layers lowering cost per bit
-
Expanding use in laptops, gaming devices, extended reality headsets and edge computing
U.S. Universal Flash Storage Market Size Outlook
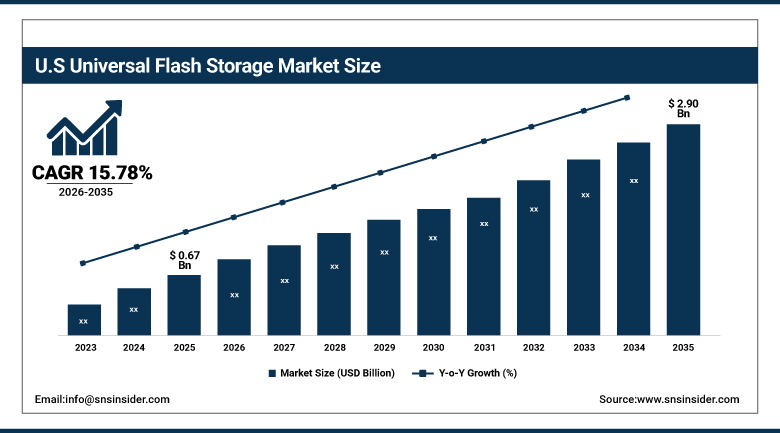
The U.S. Universal Flash Storage Market was valued at USD 0.67 Billion in 2025 and is expected to reach USD 2.90 Billion by 2035, growing at a CAGR of 15.78% from 2026-2035.
The U.S. Universal Flash Storage Market is shaped by demand from premium smartphones, connected vehicles and edge computing devices, even though most device assembly takes place in Asia. American memory and platform companies design the technology and sell UFS-based products to global handset and automotive customers. Federal incentives are encouraging more local chip and memory production. Automakers in the country are adding larger screens and driver assistance features that need fast storage. Data security rules and trade controls influence sourcing. Demand is expected to rise as vehicle software and on-device intelligence grow. Technology companies and startups in the country also use fast storage in edge servers and robots.
⮞In June 2025, the U.S. Department of Commerce announced that Micron plans USD 200 billion in U.S. manufacturing and research investment, backed by up to USD 275 Billion in additional CHIPS Act incentives. The plan shows the policy push to build local memory capacity.
Universal Flash Storage Market Segment Analysis
-
By Configuration, the Embedded segment dominated the Universal Flash Storage Market with approximately 68.10% share in 2025, while the Removable segment is the fastest growing with a CAGR of approximately 17.30%.
-
By Capacity, the 256 GB segment dominated the Universal Flash Storage Market with approximately 38.00% share in 2025, while the 1 TB & Above segment is the fastest growing with a CAGR of approximately 19.70%.
-
By Application, the Mass Storage segment dominated the Universal Flash Storage Market with approximately 51.70% share in 2025 and is also the fastest growing with a CAGR of approximately 16.76%.
-
By End Use, the Smartphones segment dominated the Universal Flash Storage Market with approximately 67.40% share in 2025, while the Automotive Electronics segment is the fastest growing with a CAGR of approximately 21.44%.
By Configuration, Embedded Dominates the Universal Flash Storage Market and Removable Grows Fastest
Embedded UFS leads because the chip is soldered to the main board of a phone, vehicle or tablet, which gives the highest speed, the smallest footprint and the best reliability. Handset makers prefer this format because it supports slim designs and tight power budgets. Automotive suppliers choose embedded packages that meet strict temperature and vibration rules. Memory makers also ship embedded devices in the largest volumes, which lowers cost per unit. Flagship phones from major brands launched in recent years almost all rely on embedded UFS rather than card slots. The format also simplifies thermal design inside slim bodies.
Removable UFS is the fastest growing configuration as card formats bring the interface to cameras, gaming handhelds, drones and professional video tools. Cards allow users to expand storage and move large files quickly, and the standard supports high sustained speeds that older card types struggle to match. Adoption is still early, and device makers need compatible slots and host controllers. Wider support from controller suppliers and brands is gradually closing that gap, and the format suits creators who want fast offloading of high-resolution content. Camera makers see this as a way to shorten transfer times after shoots.
⮞In March 2026, Biwin showed its TAU208 automotive-grade UFS 3.1 device at MWC 2026. The showing highlights how suppliers are tailoring UFS for vehicle use.
By Capacity, 256 GB Dominates the Universal Flash Storage Market and 1 TB & Above Grows Fastest
The 256 GB capacity leads because it balances price and room for apps, photos, video and local artificial intelligence models in mainstream and premium phones. Many handset makers use this option as the standard tier for current flagship models, while 128 GB serves entry-level devices. Larger storage raises the bill of materials, so brands are careful about moving the base model upward. Memory makers support 256 GB with mature production and attractive yields. Consumers also keep more content on phones than before, which sustains demand for mid-high tiers.
The 1 TB and above tier is the fastest growing as users store high-resolution video, large games and on-device models. Premium phones, automotive systems and laptops are the first products to use these sizes. Memory makers have introduced devices that reach 1 TB using high-density layered NAND, and some roadmaps point to even larger options. Price remains the main barrier, but falling cost per bit and the premium positioning of top models support growth. Vehicle makers also want larger local storage for maps, sensor logs and software updates.
⮞In March 2025, Sandisk introduced its iNAND AT EU752 automotive UFS 4.1 device in capacities from 128 GB to 1 TB. The range shows the spread of capacity options now available.
By Application, Mass Storage Dominates the Universal Flash Storage Market and Is Also the Fastest Growing
Mass storage leads because most UFS devices serve as the main storage for the operating system, apps and user data in phones, tablets and vehicles. The interface supports many parallel commands, so devices stay responsive when several apps run at once. Handset makers rely on this role to deliver fast app launches, quick camera saves and smooth gaming. Automotive systems use mass storage for maps, media and software images. Boot storage and execute-in-place flash are smaller uses with specific needs, and external cards add a further, still modest, share.
Mass storage is also the fastest growing application as artificial intelligence features need quick access to large model files. Phones now run language and image models on the device, and loading them from slow storage would delay responses. Vehicles likewise store several software images and sensor data sets that must be read quickly. Higher speeds in each new standard also let vendors replace separate memory components with one device. These shifts give mass storage the strongest momentum among the main application types over the forecast period.
⮞In March 2025, Longsys unveiled UFS 4.1 products using its WM7400 controller, offering speeds of up to 4,350 MB/s and capacities of up to 2 TB. The launch reflects the push toward high-speed mass storage.
By End Use, Smartphones Dominates the Universal Flash Storage Market and Automotive Electronics Grows Fastest
Smartphones lead because nearly every mid-range and premium handset now adopts UFS to support high-resolution cameras, gaming and on-device artificial intelligence. Annual handset volumes are far larger than any other device category, so even a modest attach rate produces major memory demand. Brands in China, South Korea and the United States compete on storage speed as a product feature. Lower-priced phones continue to use eMMC in some regions, which leaves room for further migration as prices drop and standards mature. Brands in emerging markets will follow once costs ease.
Automotive electronics is the fastest growing end use as cars add large displays, digital cockpits, advanced driver assistance and over-the-air updates. These functions need storage that is fast, durable and qualified for automotive temperature ranges. Suppliers have launched UFS 3.1 and 4.1 parts built to automotive standards, and carmakers are specifying them for new platforms. Longer vehicle design cycles mean growth builds gradually, yet each qualified design wins for years. Suppliers also gain from software update services over the vehicle life. Electric vehicles add more computing and therefore more storage per car.
⮞In April 2026, the European Automobile Manufacturers' Association reported that battery-electric cars held 19.4% of EU new registrations in the first quarter, equal to 546,937 vehicles. Electric models carry more onboard computing and storage content.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
40.00 |
|
Europe |
Germany |
27.31 |
|
Asia Pacific |
China |
41.22 |
|
Latin America |
Brazil |
46.54 |
|
Middle East & Africa |
Saudi Arabia |
28.67 |
North America Universal Flash Storage Market Insights
North America held about 26.73% of the Universal Flash Storage Market in 2025, supported by design activity at major memory, platform and device companies. The United States is the center of demand, with premium smartphones, connected vehicles and edge computing equipment using UFS. Several memory and storage brands supply products from the region. Canada and Mexico add automotive and electronics assembly demand, and Mexico builds vehicles that increasingly contain advanced infotainment and driver assistance electronics.
Federal policies favor new memory production in the country, while export restrictions affect the supplier that serves particular consumers. Automakers are switching to central processing, thus boosting the storage requirements for each vehicle. Telecom providers keep implementing 5G technology, hence creating a demand for good smartphones. The higher costs of memory in 2026 are making some device manufacturers reconsider their agreements; however, premium customers want devices with fast storage and increased storage capacity.
⮞In July 2026, the Semiconductor Industry Association reported that global chip sales reached USD 120.6 billion in May 2026, up 104.1% from a year earlier, with the Americas up 132.2%. The surge shows strong pricing and demand across memory-heavy markets.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Universal Flash Storage Market Insights
Europe accounts for about 15.27% of the Universal Flash Storage Market and is led by Germany, France, the United Kingdom and Italy. Demand comes mainly from automotive and industrial electronics rather than handset assembly. Cars built in the region increasingly carry large screens and connected services. German carmakers and suppliers specify automotive-grade storage for digital cockpits and driver assistance, and industrial users need long-life memory for factory and medical equipment. European phone sales also add consumption, though most devices are produced elsewhere.
Electrification is a major lever. As battery-electric cars gain share, vehicles carry more software and local data storage. European regulators emphasize cybersecurity and data protection, which shapes how storage is qualified and updated. Local memory production is limited, so buyers rely on imports from Asia and the United States, and supply chain resilience is a priority. Embedded specialists in the region serve industrial customers who need smaller volumes with extended availability guarantees. Long product lifecycles in medical and industrial markets favor suppliers with stable roadmaps.
⮞In April 2026, the European Automobile Manufacturers' Association reported that battery-electric cars made up 19.4% of new EU registrations in the first quarter. The shift supports demand for automotive-grade storage.
Asia Pacific Universal Flash Storage Market Insights
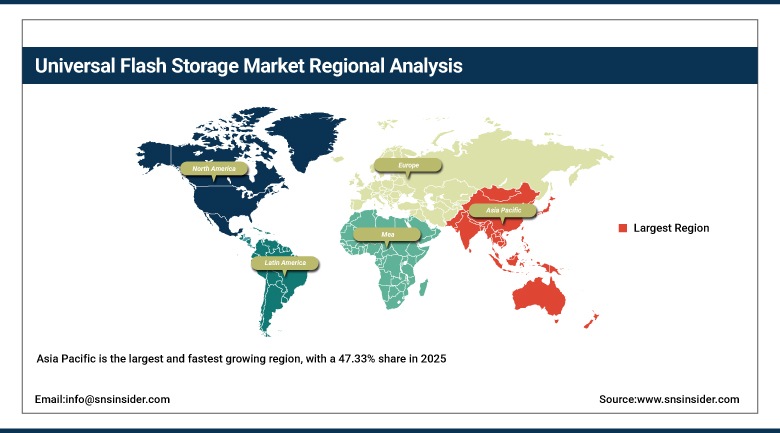
Asia Pacific is the largest and fastest growing region, with a 47.33% share in 2025 and a projected CAGR of 16.98% during 2026-2035. South Korea, China, Japan, Taiwan and India are central. Leading Korean and Japanese memory makers and several Chinese suppliers produce the memory, while the region also assembles most of the world's smartphones. Controller makers in Taiwan and China complete the supply chain, and large handset brands in the region set specifications for new generations. Their influence on standards is strong.
Local ecosystems give the region an advantage. Memory fabrication, packaging, controllers and device assembly sit close together, which speeds product cycles. Close contact between chip designers and phone brands helps new generations reach shelves quickly. China is building its own memory and controller capacity, and India is growing as a phone production base with government incentives. Memory price increases in 2026 have lifted supplier revenue but also raised handset costs for brands in price-sensitive markets. Automotive electronics in China, Japan and Korea add a second strong growth path.
⮞In October 2026, South Korea's trade ministry reported that September semiconductor exports reached USD 60.3 billion, up 263% from a year earlier. The figure shows how strongly memory demand is lifting regional output.
MEA & Latin America Universal Flash Storage Market Insights
Latin America and the Middle East and Africa together hold about 10.67% of the Universal Flash Storage Market. In Latin America, Brazil and Mexico lead, mainly through phone assembly and consumption. Brazil's manufacturing zone in Manaus produces large volumes of phones, and Mexico serves both consumer electronics and automotive plants. Most handsets sold in these markets are mid-range, so adoption of UFS is rising gradually as prices fall and 5G coverage spreads.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Turkey and South Africa lead demand, supported by rising smartphone penetration and growing mobile internet use. Affordability is the main constraint, since entry-level phones continue to use cheaper storage. Mobile operators and governments are investing in 5G and digital services, which should lift demand for capable devices. Younger populations in both regions are driving smartphone growth. Local assembly programs in several countries may also draw in memory content over the next decade. Telecom spending in the Gulf and Africa supports the shift to more capable handsets.
Market Dynamics
Growth Drivers: On-Device AI and 5G Adoption Drive Growth in the Universal Flash Storage Market
On-device artificial intelligence is the strongest driver. Phones now run language, imaging and assistant models locally, and these models are large files that must load quickly into memory. Faster storage cuts wait time, so brands are promoting speed as a feature. Each new UFS generation roughly doubles bandwidth and improves power efficiency, which matters for battery life. Memory makers also move to higher layer counts that raise capacity while lowering cost per bit, widening the range of devices that can adopt the interface. Suppliers also publish roadmaps that reassure handset makers about future capacity.
Fifth-generation networks and richer media reinforce demand. Faster connections encourage users to download large games, shoot high-resolution video and keep more content on the device, all of which need quick storage. Automotive, gaming and extended reality products add further uses. Competition among handset brands also keeps pushing specifications upward, since storage speed is easy to market. As prices of earlier generations fall, mid-range phones begin to adopt UFS in place of eMMC, which broadens the base. Developers of games and camera apps also design for faster storage once it is common.
⮞In June 2026, Ericsson reported that global 5G subscriptions were close to 3.3 billion. The large subscriber base supports demand for capable handsets with fast storage.
Restraints: Memory Cost Inflation and eMMC Substitution Restrain Growth in the Universal Flash Storage Market
Memory cost inflation restrains growth. In 2026, strong demand for artificial intelligence servers pulled supply toward high-end memory, and mobile memory prices rose sharply. Handset makers faced higher bills of materials and, in some cases, raised retail prices or trimmed storage options. Because UFS costs more than eMMC, price-sensitive brands may delay adoption or choose lower capacities. Cost swings also make it hard for buyers to commit to long supply contracts. Planning errors can leave some brands short of parts or holding costly stock.
Technical and supply limits add further pressure. Faster interfaces generate more heat, so thermal design must keep devices from throttling under sustained loads. Mid-range and Internet of Things products often stay with eMMC because it is cheaper and adequate. Supply depends on a small number of memory and controller makers, and one major supplier has reduced its focus on mobile NAND, which narrows choice. Trade controls and regional tensions add uncertainty to sourcing for some customers. Buyers therefore keep second sources, which adds qualification effort.
⮞In March 2026, OPPO announced price increases on selected A series, K series and OnePlus models from March 16, citing the rising cost of high-speed storage. The move shows how component costs can reach consumers.
Opportunities: Automotive and Edge Computing Create Opportunities in the Universal Flash Storage Market
Automotive electronics offer the most visible opportunity. Vehicles with digital cockpits, advanced driver assistance and over-the-air updates need storage that is fast and durable. Several suppliers have introduced UFS parts qualified to automotive standards and meeting functional safety needs, and carmakers are designing them into new platforms. Each design win supplies volume for many years, so early movers can secure steady revenue. Qualification takes a year or more, which protects incumbents once chosen. Electric vehicles raise content per car further because they carry more software and sensors.
Edge computing, wearables and extended reality devices add more potential. These products need compact, power-efficient storage with high throughput, which suits UFS. Data center and industrial uses are small today but may grow as vendors adapt the standard to new workloads. Memory makers are also adding capacity, which could ease pricing over time. New UFS 5.0 platforms give handset and vehicle designers headroom for the next generation of intelligent features. Lower prices as supply expands should also help adoption in mid-range products.
⮞In June 2026, SEMI projected that spending on 300mm memory equipment would reach about USD 52 billion in 2026, up 29%. The investment points to expanding supply for storage products.
Recent Developments:
-
2026: Samsung Electronics unveiled UFS 5.0 with read speeds of up to 10.8 GB/s, targeting on-device artificial intelligence. The company said mass production is planned for the fourth quarter of 2026.
-
2025: SK hynix announced that it had developed a UFS 4.1 solution built on 321-layer 1 Tb triple-level cell NAND, reaching speeds of up to 4,300 MB/s. The company planned volume supply from the first quarter of 2026.
-
2025: Kioxia began sampling automotive UFS version 4.1 devices in capacities from 128 GB to 1 TB, built on its BiCS8 flash. The devices are aimed at advanced driver assistance and in-vehicle systems.
Universal Flash Storage Companies are:
-
Samsung Electronics Co., Ltd.
-
Kioxia Holdings Corporation
-
Micron Technology, Inc.
-
Sandisk Corporation
-
Silicon Motion Technology Corporation
-
Longsys Electronics Co., Ltd.
-
Kingston Technology Company, Inc.
-
Biwin Storage Technology Co., Ltd.
-
HOSINGLOBAL
Universal Flash Storage Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 6.35 Billion |
| Market Size by 2035 | USD 27.23 Billion |
| CAGR | CAGR of 15.68% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Configuration (Embedded and Removable) • By Capacity (32 GB, 64 GB, 128 GB, 256 GB, 512 GB, and 1 TB & Above) • By Application (Mass Storage, Boot Storage, External Card, and Execute-in-Place Flash) • By End Use (Smartphones, Automotive Electronics, Gaming Consoles & Cameras, Laptops & Displays, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Samsung Electronics Co., Ltd., SK hynix Inc., Kioxia Holdings Corporation, Micron Technology, Inc., Sandisk Corporation, Silicon Motion Technology Corporation, Phison Electronics Corp., Longsys Electronics Co., Ltd., Kingston Technology Company, Inc., Biwin Storage Technology Co., Ltd., HOSINGLOBAL |

Frequently Asked Questions
Key players include Samsung Electronics, SK hynix, Kioxia, Micron Technology, Sandisk, Silicon Motion Technology, Phison Electronics, Longsys, Kingston Technology, YMTC, Intelligent Memory, Biwin and HOSINGLOBAL.
Key opportunities include automotive-grade UFS for digital cockpits and driver assistance, edge computing and extended reality devices, and next-generation UFS 5.0 platforms for on-device artificial intelligence.
On-device artificial intelligence and faster mobile networks are the main growth factors, since they require storage with high speed and low power use.
By Configuration, the Embedded segment dominated the market in 2025 with an estimated 68.10% share, supported by its speed, small footprint and reliability.
Asia Pacific dominated the market with a share of 47.33% in 2025, driven by memory production and smartphone assembly in South Korea, China, Japan and Taiwan.
