
Veterinary Software Market Report Scope & Overview:
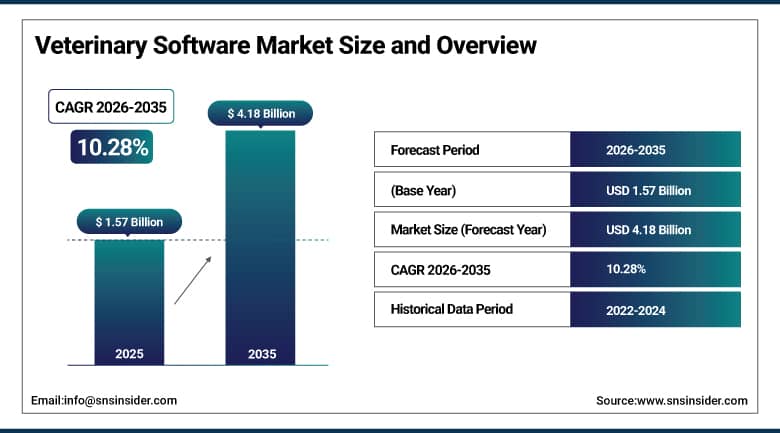
The Veterinary Software Market, which covers practice management, imaging, telehealth, and documentation software used by animal hospitals and clinics, was valued at USD 1.57 Billion in 2025 and is estimated at USD 1.73 Billion in 2026. It is projected to reach USD 4.18 Billion by 2035, registering a compound annual growth rate (CAGR) of 10.28% from 2026 to 2035. Clinics are moving from server-based systems to cloud platforms that manage records, scheduling, billing, and client communication in one place, while artificial intelligence (AI) tools that write visit notes are becoming a standard purchase.
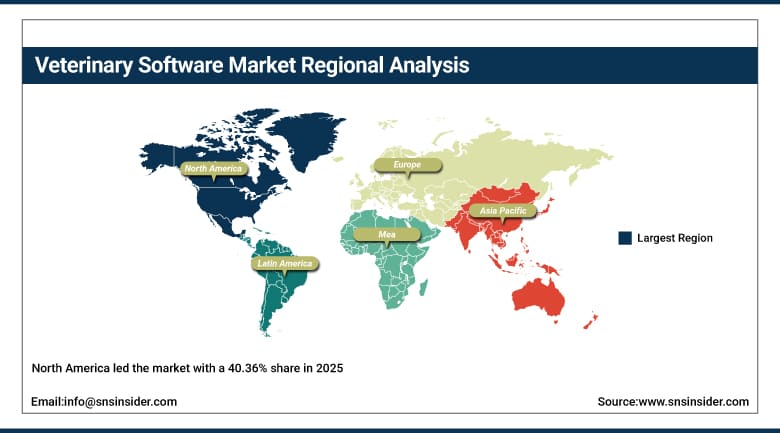
North America accounted for the largest share of the market at 40.36% in 2025. The region has high pet ownership spending, large corporate clinic groups, and an early shift to cloud-based systems and AI documentation. Europe holds the second position, supported by growing clinic chains and price transparency rules in the United Kingdom. Asia Pacific is expected to expand at the fastest pace through 2035, as rising pet adoption in China, Japan, and India lifts the number of veterinary clinics that buy digital systems. Latin America and the Middle East and Africa remain smaller.
To Get More Information On Veterinary Software Market - Request Free Sample Report
Key Report Takeaways
-
By product, practice management software held a 52.37% share in 2025, while telehealth software is the fastest growing.
-
By deployment, cloud held a 62.38% share in 2025, while hybrid is the fastest growing.
-
By animal type, companion animals held a 61.93% share in 2025, while livestock animals are the fastest growing.
-
By end user, veterinary hospitals and clinics held a 70.29% share in 2025, while specialty and referral centers are the fastest growing.
-
By region, North America held a 40.36% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
-
AI scribes are being built into practice management systems rather than sold as separate tools.
-
Cloud-native platforms are replacing server-based systems, supported by migration offers and data conversion services.
-
Corporate clinic groups are standardizing on one platform across hundreds of sites.
-
Diagnostics, imaging, and practice software are converging under single vendors.
-
Livestock and herd management software is moving closer to veterinary practice systems.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Pet population growth and higher spending per pet |
+3.18% |
North America, Europe, Asia Pacific |
Long term (4 years or more) |
|
Demand for AI scribe and documentation tools |
+4.26% |
North America, Europe |
Short term (2 years or less) |
|
Cloud migration of legacy systems |
+3.37% |
North America, Europe |
Short term (2 years or less) |
|
Labor constraints and efficiency needs |
+2.64% |
United States, United Kingdom |
Medium term (2 to 4 years) |
|
Corporate clinic group rollouts |
+2.27% |
Europe, North America |
Medium term (2 to 4 years) |
Rising Pet Ownership Expands the Clinic Client Base
Higher pet populations create more visits, more records, and more communication for each clinic to manage, and software keeps these tasks organized. In December 2025, the American Veterinary Medical Association (AVMA) reported that the U.S. dog population reached 87.3 million in 2025, compared with 52.9 million in 1996. Owners also treat pets as family members and spend more on preventive care, diagnostics, and specialty treatment, which raises the number of billable events that must be tracked. Clinics adopt digital systems to handle this volume without adding administrative staff.
AI Scribe Demand Reshapes Software Purchases
Veterinarians spend long hours on medical records after appointments, and ambient tools that listen to exams and draft notes reduce this burden. Practice management vendors now add scribing, treatment boards, and automated summaries to their platforms, and clinics treat these features as a reason to switch systems. Buyers value time saved per appointment, shorter days for staff, and cleaner records for billing and client communication. As language models improve in medical terminology and species-specific details, adoption is moving from early users to mainstream practices in the United States and Europe.
Cloud Migration Replaces Server-Based Systems
Many clinics continue to operate software through local servers, which require backing up, updating security, and on-site technical assistance. The cloud system takes care of all these tasks, provides access anywhere, and gets new capabilities automatically. Remote access is useful for ambulatory and mixed animal clinics since they document cases outside the clinic premises. Software vendors are motivating adoption by offering data migration services and pricing plans. Corporate organizations tend to favor cloud-based systems for their ability to offer consistent reporting from all locations.
Labor Constraints Increase the Need for Efficiency
Given the scarcity of veterinarians and veterinary technicians in clinics, automation software becomes extremely valuable since it helps minimize administrative tasks. As of October 2026, according to the United States Bureau of Labor Statistics, the number of jobs held by veterinarians is expected to grow by 9.00% from 2025 to 2035, which will be a rate much higher than the average for all occupations. The use of automated reminders, online appointment scheduling, e-forms, and electronic prescriptions enables staff to deal with a larger number of patients per day.
Corporate Clinic Groups Standardize Platforms
Consolidators and private equity-backed groups acquire independent clinics and then standardize operations across the network. A single platform supports shared inventory, pricing rules, central reporting, and consistent client communication, which makes integration of newly acquired sites faster. Large groups negotiate enterprise contracts that cover hundreds of clinics, and these deals give vendors long contract terms and cross-selling opportunities for imaging, payments, and analytics modules. The trend is strongest in the United States and Europe, where group ownership of clinics continues to expand.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Telehealth rules on the veterinarian-client-patient relationship |
-1.42% |
United States |
Medium term (2 to 4 years) |
|
Migration and implementation friction |
-1.96% |
Global |
Short term (2 years or less) |
|
Pricing and margin pressure on clinics |
-1.18% |
United Kingdom, Europe |
Medium term (2 to 4 years) |
|
Softer consumer spending on pet care |
-0.88% |
United States |
Short term (2 years or less) |
Veterinarian-Client-Patient Relationship Rules Limit Telehealth
Remote care software depends on rules that allow veterinarians to examine, diagnose, and prescribe without a physical visit. In September 2024, the U.S. Food and Drug Administration Center for Veterinary Medicine stated that, under federal rules, a veterinarian-client-patient relationship cannot be established by telemedicine alone. State laws differ on in-person exam requirements and prescription limits, which forces vendors to configure workflows state by state. Clinics hesitate to invest in virtual care modules until rules become clearer, and this slows the adoption of telehealth software.
Migration and Implementation Friction Delays Switching
Moving years of patient records, invoices, and imaging files to a new system is slow and carries a risk of data loss. Staff must learn new workflows while keeping the clinic open, and many practices delay changes during busy seasons. Vendors respond with onboarding teams, data conversion tools, and discounted training, but these programs raise their own costs. Large implementations across many sites can take months, and some groups pause rollouts when early sites report problems. As a result, replacement decisions are often postponed even when users are dissatisfied.
Pricing Scrutiny Adds Margin Pressure for Clinics
Regulatory authorities in some markets are looking at prices that veterinary groups are charging, impacting their expenditure towards technology investments. The United Kingdom’s Competition and Markets Authority released its final decision in March 2026 on veterinary services offered to domestic animals. It concerns online price lists and restriction on the cost of prescriptions. This requires clinics to adapt to posting prices and making valid prescriptions, leading to more work and reduced revenue. Budget limitations could stall optional software acquisitions, particularly independent clinics.
Softer Consumer Spending Reduces Elective Visits
Pet owners who face higher living costs may delay checkups, dental work, and diagnostics, which lowers clinic visit volume and the revenue that supports technology budgets. The American Pet Products Association reported in its 2026 survey that 32.00% of owners said they were spending less on pet care, up from 22.00% in the earlier survey. Clinics respond by limiting new purchases and negotiating contract terms. Vendors that show direct savings in staff hours or collections remain more resilient than those that sell optional features.
Veterinary Software Market Segment Analysis
By Deployment, Cloud Dominates Veterinary Software Market; Hybrid to Register Fastest Growth.
The cloud deployment will occupy 62.38% of market share in 2025 since practices do not want to manage the servers, patches, and backups. The browser and mobile usage will help veterinary doctors check the records in their homes, in the field, or even at their partner facilities. Frequent software updates from vendors will give cloud users new capabilities like AI scribing with no need for installation. In addition, the subscription-based model is better for independents since costs are distributed throughout the subscription. Small clinics can have enterprise-level security without employing IT personnel.
The hybrid deployment will have a CAGR of 11.61% for 2026 to 2035 due to practices' needs to store imaging archives and sensitive data locally but shift the work processes to the cloud. Practices face problems with huge imaging files and poor internet connection in the rural areas. Vendors try to fix the problem by introducing local storage and synchronization features, so migration can be done in pieces without changing everything at once.
By Product, Practice Management Software Dominates Veterinary Software Market; Telehealth Software to Register Fastest Growth.
Practice management software accounted for a 52.37% share in 2025 because it forms the core record system of every clinic, covering patient histories, appointments, billing, inventory, and client reminders. Other tools such as imaging, payments, and scribes connect to it, which makes the system hard to replace once staff are trained. Vendors keep adding modules for communication, e-prescribing, and reporting, and clinics prefer a single supplier that simplifies support and training. Integration with laboratory and payment tools adds further stickiness.
Telehealth software is projected to grow at a CAGR of 14.95% from 2026 to 2035 as clinics add video visits, remote triage, and follow-up messaging for busy owners. Remote consultations reduce travel for rural clients and help practices manage after-hours demand. As more states clarify rules for remote prescribing, vendors are packaging scheduling, payment, and record functions with virtual visits, and large groups are rolling out telehealth across many locations. Pet owners also value video visits for follow-up questions.
By Animal Type, Companion Animals Dominate Veterinary Software Market; Livestock Animals to Register Fastest Growth.
Companion Animals accounted for 61.93% of the market in 2025 due to the fact that the number of visits to clinics by dogs and cats is the largest, along with revenue from their services. Customers demand reminders, appointment scheduling, access to records, and prescriptions refilling. Software plays an important role in providing a high-quality client experience. Preventative care plans, vaccination, dental services, and chronic condition management create recurring appointments which require scheduling and billing. There are other services such as oncology and cardiology which have specific documentation needs.
Livestock animals are projected to witness the highest growth at a CAGR of 12.02% during 2026-2035. Producers and veterinarians responsible for managing herds have needs for treatment history, drug withdrawal time, vaccination schedule, and animal traceability. Requirements for food safety regulations and documentation of antibiotic usage encourage the implementation of digital solutions and mobile apps are used to perform operations on a farm. Herd management solution vendors begin to integrate veterinary practice management software, thus increasing the target market. Exporters are demanding records of animal health history.
By End User, Veterinary Hospitals and Clinics Dominate Veterinary Software Market; Specialty and Referral Centers to Register Fastest Growth.
Veterinary hospitals and clinics were expected to occupy 70.29% market share owing to the large number of patient visits and employment of veterinary personnel at these institutions. Each institution is required to have practice management software for record keeping, billing, inventory management, and patient communication. The more elaborate hospitals require additional functionalities like imaging, laboratory management, and surgery scheduling. The corporate entities acquire licenses for their entire network whereas the independent clinics acquire single license. All these factors contribute towards a substantial demand for practice management solutions.
The specialty and referral centers are anticipated to witness the highest CAGR of 11.91% during 2026 to 2035 due to growing demands for advanced care in oncology, neurology, cardiology, and emergency medicine from pet owners. The specialty and referral centers will require case referral solutions, intricate scheduling, imaging capabilities, and patient communication with referring clinics. An increasing number of multi-specialty hospitals will drive the need for inpatient care, anesthesia record management, and multiple departmental case management.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
86.42% |
|
Europe |
United Kingdom |
23.58% |
|
Asia Pacific |
China |
34.76% |
|
Middle East & Africa |
South Africa |
31.09% |
|
Latin America |
Brazil |
47.35% |
North America Veterinary Software Market
North America led the market with a 40.36% share in 2025, supported by high pet ownership, strong spending on veterinary care, and large corporate clinic groups that standardize systems across many sites. The United States generated USD 547.60 Million in 2025 and is projected to grow at a CAGR of 9.94% from 2026 to 2035. Early adoption of cloud systems and AI scribes keeps the region ahead, while Canada shows rising demand from independent clinics and provincial veterinary groups across the country.
In June 2025, Ohio signed a law that allows a veterinarian-client-patient relationship to be established through telehealth, with limits on the length of prescriptions issued after a virtual exam. State laws of this kind widen the use of video visit and remote monitoring modules, although rules differ across the country. Vendors that let clinics change workflows by state and keep complete audit trails in the record are better placed to serve multi-state groups. Compliance with state pharmacy rules also matters for prescription workflows.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Veterinary Software Market
Europe is the second largest market, having the share of 27.19% in 2025. The United Kingdom dominates the region, followed by Germany, France, and the Nordic countries where corporate clinic groups keep growing. The groups buy out independent clinics and move them into common platforms which allows using enterprise agreements. Language capabilities, compliance with local invoicing rules and integration with national pet registries affect the buying decisions, and European companies compete well with North American companies. Additional compliance requirements relate to pet passport and medicine importation documentation.
Northern Europe uses cloud extensively, while Southern and Eastern Europe use old installed systems and provide substantial replacement opportunity. Pet insurance developments in the United Kingdom, Sweden, and Germany drive the demand for digital claim/billing integration with the practice software. Livestock-focused software providers operate in Ireland, the Netherlands and Denmark where the recording of herd and medicine management is a significant part of farm regulation and dairy logistics. Providers with multination capabilities related to taxes and languages have competitive advantage.
Asia Pacific Veterinary Software Market
The Asia Pacific region will register the fastest growth rate, registering a CAGR of 12.24% during 2026 to 2035 due to growing adoption of pets and veterinary clinics in the urban regions. China will lead among all countries of the region due to the rapidly growing pet population and emergence of new clinic chains in urban regions. Japan has an already established market, which is driven by demand for imaging and record systems. Australia is one of the pioneers in implementing cloud platforms and AI-driven documentation services in companion and mixed practices.
India will be the fastest growing country in the region due to growing demand for preventative healthcare from young pet-owning households living in urban centers. South Korea, Thailand, and Singapore will contribute demand due to the presence of premium clinics and specialty hospitals. The majority of clinics in this region do not have enough budget to buy the software, thus the vendors provide mobile-first software, localized language interfaces, and monthly subscriptions as pricing model. The growing coverage of the insurance market for pets in Japan and Australia is also boosting the demand for billing solutions.
Latin America Veterinary Software Market
Latin America represents 6.47% of the market in 2025, dominated by Brazil with a high population of pets as well as a large number of independent clinics. Other top countries include Mexico, Argentina, Chile, and Colombia with urban clinics embracing cloud-based systems for scheduling appointments, billing, and reminders. Tax invoicing regulations require software to be compatible with nationally recognized formats for electronic invoices, favoring providers with regional teams and partners who can accommodate these regulations. In-store clinics from pet food retailers are also emerging.
The drivers for growth are an increase in pet ownership from urban families, expansion of pet retail clinics chains and the adoption of smartphones for communicating with owners. In addition, animal-heavy economies such as Brazil and Argentina help drive the need for herd health and traceability software for cattle farmers and export programs. Currency fluctuations and clinic budget constraints have slowed purchases, hence making it necessary for vendors to offer monthly subscriptions, payment methods that are favorable locally, and Spanish and Portuguese language support.
Middle East & Africa Veterinary Software Market
The Middle East and Africa accounted for a market share of 5.15% in 2025. The countries of the Gulf are key in terms of demand with their high-end small animal clinics, equine hospitals, and increasing numbers of pet owners in metropolitan areas like Dubai, Riyadh, and Doha. The equine and camel care presents particular software needs, such as breeding, racing, and performance management. The imports of pet food and medication are driving clinics to install inventory management and regulatory tools, as vendors collaborate with distributors in the region to reach these clients.
South Africa accounts for the biggest market of Africa. It features a well-developed private practice, hospitals with their practice management software installed, as well as developed livestock and game animal sectors. In other African countries, adoption is at its beginnings in the form of mobile apps used by animal health care professionals and farm veterinarians. Limited connectivity and funding is constraining broader adoption, and thus, the international development initiatives and distributors participate in the process. Slowly veterinary schools and government programs increase the professional capacity in the region.
Competitive Landscape
The Veterinary Software Market has moderate concentration. There are vendors of diagnostics and animal health companies, distributors, and software firms offering practice management solutions and associated tools without having a dominant share in revenues. Existing vendors secure big deals by leveraging an existing installed base, integration with diagnostics and imaging equipment, and comprehensive support networks, whereas cloud-native vendors fight through providing better usability, faster updates, and integrated artificial intelligence functionalities.
There are three core strategies pursued by vendors. First, they invest in acquiring AI scribe, imaging, and herd management firms for expanding their platform offerings. Second, they create alliances with distributors, pet food manufacturers, and clinic networks to access more customers at once. Finally, they offer product rebirths on the cloud-based architecture coupled with migration help, training, and incentives to ease transition from legacy systems.
Veterinary Software Market Industry Leaders
1. IDEXX Laboratories: Offers Cornerstone, Neo, and ezyVet practice management systems linked to diagnostics and imaging.
2. Covetrus: Provides the Pulse cloud platform and Ascend practice management software with AI workflow tools.
3. Nordhealth: Supplies Provet Cloud, a practice management platform used by clinic groups across Europe.
4. Patterson Veterinary: Delivers NaVetor cloud software for practice management and client communication.
5. Instinct Science: Develops Instinct EMR and AI scribe tools for veterinary clinics.
Companies Covered in this Report
-
IDEXX Laboratories
-
Covetrus
-
Nordhealth
-
Patterson Veterinary
-
Instinct Science
-
Digitail
-
Otto
-
Herdwatch
-
Cencora (MWI Animal Health)
-
DaySmart Software
Recent Industry Developments
-
January 2025: Covetrus added AI-powered ambient note writing and treatment boards to its Pulse platform.
-
July 2025: MWI Animal Health, part of Cencora, added Furscription e-prescribing to its technology solutions.
-
October 2025: Digitail announced a go-to-market partnership with CDMV in Canada.
-
January 2026: Instinct Science acquired ScribbleVet, an AI scribe provider for veterinary clinics.
-
January 2026: Herdwatch acquired VetDrive, a cloud practice management system.
-
January 2026: Patterson Veterinary took full ownership of NaVetor and relaunched the cloud software.
-
July 2026: Nordhealth reported that the 50th Vets for Pets clinic had gone live on Provet Cloud, with more than 400 planned.
-
September 2026: IDEXX Laboratories acquired CoVetAI to add ambient listening software to its veterinary workflow tools.
Scope and Research Methodology
The study defines the Veterinary Software Market as software and related services used by veterinary hospitals, clinics, and animal health professionals to manage records, appointments, billing, inventory, imaging, client communication, and remote care. Covered offerings include practice management systems, imaging and picture archiving software, telehealth platforms, and AI documentation tools. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are expressed in USD. The segmentation covers product, deployment, animal type, and end user, along with five regions and leading countries within each region. Diagnostic instruments, animal health drugs, and general business software are excluded. Software sold only for livestock farm management without veterinary records is also excluded.
The research program combines secondary and primary research. Secondary research draws on company annual reports, investor presentations, regulatory filings, government and regulator databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with executives, product and business heads, procurement leaders, veterinarians, and practice managers across the value chain. These discussions validate assumptions on adoption rates, deployment preferences, pricing, and switching behavior, and interview findings are weighted by the relevance of each respondent. Responses are cross-checked against company disclosures, and interview findings are weighted by the relevance and seniority of each respondent.
Market engineering follows a bottom-up build from vendor revenue, product adoption, and clinic counts, cross-checked top-down against animal health spending and pet population indicators. Triangulation across both approaches narrows differences before values are finalized. Forecasts reflect drivers such as cloud and AI adoption, regulation, clinic consolidation, and macroeconomic conditions. Regional estimates are aligned so that country values add to regional totals, and each estimate passes through an analyst quality review before publication. Sensitivity checks test the effect of changes in adoption speed, pricing, and regulation on each segment, and global totals equal the sum of regional values.
Veterinary Software Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.57 Billion |
| Market Size by 2035 | USD 4.18 Billion |
| CAGR | CAGR of 10.28% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Practice Management Software, Imaging Software, Telehealth Software, AI Documentation Software, and Others) • By Deployment (Cloud, On-Premise, and Hybrid) • By Animal Type (Companion Animals, Livestock Animals, and Equine) • By End User (Veterinary Hospitals and Clinics, Specialty and Referral Centers, Reference Laboratories, and Mobile Veterinary Services) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | IDEXX Laboratories, Covetrus, Nordhealth, Patterson Veterinary, Instinct Science, Digitail, Otto, Herdwatch, Cencora (MWI Animal Health), DaySmart Software |

Frequently Asked Questions
The market was valued at USD 1.57 Billion in 2025 and is projected to reach USD 4.18 Billion by 2035 at a CAGR of 10.28%.
North America led the market with a 40.36% share in 2025, supported by high pet ownership and large clinic groups.
Asia Pacific is expected to grow the fastest, at a CAGR of 12.24% from 2026 to 2035.
Practice management software, cloud deployment, companion animals, and veterinary hospitals and clinics hold the largest shares in their segments.
Telehealth software, hybrid deployment, livestock animals, and specialty and referral centers are the fastest growing segments.
Major players include IDEXX Laboratories, Covetrus, Nordhealth, Patterson Veterinary, and Instinct Science.
Telehealth rules, migration friction, pricing pressure on clinics, and softer consumer spending limit faster growth.
