
Whole Genome Sequencing Market Report Scope & Overview:
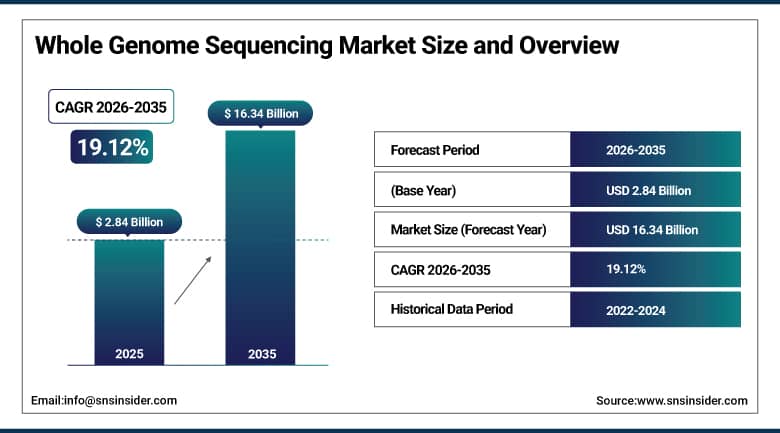
The Whole Genome Sequencing Market was valued at USD 2.84 Billion in 2025 and is estimated at USD 3.38 Billion in 2026. It is projected to reach USD 16.34 Billion by 2035, advancing at a CAGR of 19.12% from 2026 to 2035. Whole genome sequencing reads the complete DNA of an organism, and falling costs per genome are moving it from research projects into rare disease diagnosis, cancer care, newborn screening, and population health programs. New instruments, longer reads, and faster analysis software are widening the number of laboratories that can offer the test at scale.
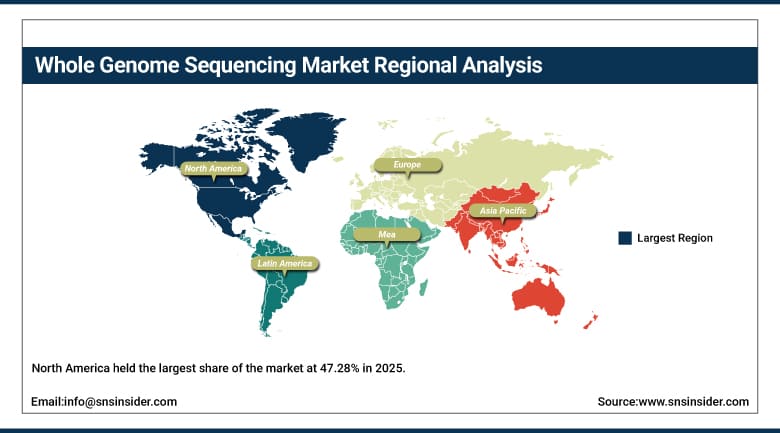
North America was the largest regional market in 2025 with a 47.28% share, supported by large research funding, early clinical adoption, and a concentration of instrument makers and sequencing service providers. Europe follows with national genomics programs and strong hospital networks, while Asia Pacific is expected to grow fastest over the forecast period as China, India, Japan, and South Korea invest in population genome projects. Latin America and the Middle East & Africa remain small but are building sequencing capacity through public programs and academic partnerships. Training partnerships support local capacity.
To Get More Information On Whole Genome Sequencing Market - Request Free Sample Report
Key Report Takeaways
- By product and service, consumables held a 56.72% share in 2025, while services are the fastest growing.
- By workflow, sequencing accounted for a 53.05% share in 2025, while data analysis is the fastest growing.
- By application, human genomes represented a 63.80% share in 2025, while microbial sequencing is the fastest growing.
- By end user, academic and research institutes commanded a 46.33% share in 2025, while hospitals and clinics are the fastest growing.
- By region, North America led with a 47.28% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
The cost of a genome keeps falling as new platforms compete on throughput and price. Instrument makers are releasing sequencers that process tens of thousands of genomes a year, and laboratories are moving from targeted panels to full genome testing because the incremental cost is shrinking while the information gained is much greater.
Long-read and phased sequencing are entering routine use. Technologies that read tens of thousands of bases at once resolve structural variants, repeat regions, and methylation patterns that short reads miss, and clinical laboratories are validating long-read genomes for cases that remain undiagnosed after standard testing.
Clinical programs are scaling. Rapid genome sequencing for critically ill infants, newborn genome studies, and genome-based monitoring of cancer after treatment are moving into health systems.
Artificial intelligence and cloud analysis are reshaping workflows. Variant calling, interpretation, and ranking tools reduce the time between sequencing and report.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Falling Cost per Genome and Platform Innovation |
+7.12% |
Global |
Short term (2 years or less) |
|
Clinical Adoption in Rare Disease, Oncology, and Newborn Care |
+5.78% |
North America and Europe |
Medium term (2 to 4 years) |
|
National and Population Genome Programs |
+4.21% |
Global |
Long term (4 years or more) |
|
Precision Medicine and Pharmaceutical Research |
+2.98% |
North America, Europe, and Asia Pacific |
Medium term (2 to 4 years) |
|
Artificial Intelligence and Cloud-Based Data Analysis |
+2.11% |
Global |
Medium term (2 to 4 years) |
Falling Cost per Genome and Platform Innovation
The price of sequencing a human genome has dropped by orders of magnitude since the first reference was completed, and the decline continues as new instruments reach the market. The National Human Genome Research Institute estimated that the Human Genome Project draft cost about USD 300 million, while current platforms deliver a genome at a small fraction of a thousand dollars. Cheaper genomes allow laboratories to replace panels and exomes with whole genome testing and enable larger research cohorts, which raises demand for instruments, consumables, and analysis services.
Clinical Adoption in Rare Disease, Oncology, and Newborn Care
Whole genome sequencing is gaining acceptance as a first-line test for children with suspected genetic disease, because it detects a wide range of variants in one assay. Hospitals use rapid genome sequencing in neonatal and pediatric intensive care to guide treatment within days. Genomics England reported in October 2025 that its Generation Study had enrolled 25,000 babies across more than 50 hospital sites. As evidence of clinical utility grows and coverage widens, hospital volumes rise and drive purchases of instruments, reagents, and interpretation services.
National and Population Genome Programs
Governments are funding large genome projects to support research, public health, and precision medicine. The National Institutes of Health reported in June 2026 that its All of Us program had released more than 535,000 whole genome sequences. The United Kingdom, India, China, Saudi Arabia, and several other countries run national programs that sequence large cohorts and build reference databases. These projects create long-term contracts for instruments, consumables, and sequencing services, support local manufacturing and data infrastructure, and generate resources that pharmaceutical developers and academic groups use to discover new targets and biomarkers.
Precision Medicine and Pharmaceutical Research
Drug developers use whole genome data to identify targets, select trial participants, and understand why patients respond differently to therapy. Genome sequencing of tumors and germline samples supports companion diagnostic development and biomarker discovery. Pharmaceutical and biotechnology companies partner with sequencing providers and biobanks to link genomic and clinical data at scale, and they increasingly sequence entire trial cohorts. This work creates recurring demand for high-throughput services and analysis platforms, especially in oncology, neurology, and rare disease programs where genetic evidence improves the odds of success.
Artificial Intelligence and Cloud-Based Data Analysis
A single genome generates hundreds of gigabytes of raw data, and turning it into a clinical report requires fast alignment, variant calling, and interpretation. Machine learning models improve accuracy and rank variants by likely relevance, while cloud platforms offer scalable storage and compute without large local investments. These tools shorten turnaround times and reduce the specialist labor needed per case. As laboratories adopt automated pipelines, they can handle higher volumes, and software and analysis services become a larger share of spending in the workflow.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High Total Cost of Ownership and Data Storage Needs |
-1.14% |
Global |
Short term (2 years or less) |
|
Limited Diagnostic Yield and Inconsistent Reimbursement |
-0.82% |
North America and Europe |
Medium term (2 to 4 years) |
|
Data Privacy, Ethics, and Regulatory Pressure |
-0.67% |
North America, Europe, and Asia Pacific |
Medium term (2 to 4 years) |
|
Shortage of Bioinformatics and Variant Interpretation Skills |
-0.45% |
Global |
Long term (4 years or more) |
High Total Cost of Ownership and Data Storage Needs
Although the cost per genome has fallen, a laboratory still needs instruments, automation, computing, storage, and trained staff, and the combined cost can be high for smaller hospitals and research groups. Raw data files are large, and storage and transfer costs rise with each additional genome. Many buyers therefore continue to use targeted panels or exome sequencing when budgets are tight, or they outsource work to service providers. These cost barriers slow the pace at which new laboratories enter the market and extend purchasing decisions.
Limited Diagnostic Yield and Inconsistent Reimbursement
Whole genome sequencing does not return a diagnosis for every patient, and the share of cases that receive an answer varies with the condition and the extent of prior testing. Payers in several regions hesitate to cover the test broadly until evidence of improved outcomes accumulates, and coverage policies differ across insurers and public programs. Uncertain reimbursement leaves some hospitals reluctant to build services, and it keeps many tests tied to research funding rather than routine healthcare budgets. Evidence from outcome studies should gradually strengthen the case for broader payment.
Data Privacy, Ethics, and Regulatory Pressure
Genomic data is highly personal, and laws such as the General Data Protection Regulation in Europe require strict consent, storage, and sharing practices. Concerns about ownership and misuse make some participants reluctant to join studies. In addition, the United States enacted the BIOSECURE Act in December 2025, restricting federal procurement from biotechnology companies of concern, which may force some buyers to change suppliers. Compliance costs and sourcing uncertainty complicate planning for both vendors and laboratories. Vendors respond with regional data hosting, consent tools, and diversified supply chains.
Shortage of Bioinformatics and Variant Interpretation Skills
Interpreting a genome requires specialists in bioinformatics, clinical genetics, and laboratory medicine, and these skills are in short supply in many countries. Laboratories struggle to hire analysts who can manage pipelines, curate variants, and write clear reports. Training programs take years, and demand from pharmaceutical and technology employers competes for the same people. The shortage limits throughput in hospital laboratories and increases reliance on external analysis services. Vendors and universities are creating joint training programs, though the supply of experienced staff remains tight.
Whole Genome Sequencing Market Segment Analysis
By Product and Service, Consumables Dominate Whole Genome Sequencing Market; Services to Register Fastest Growth.
Consumables led the market with a 56.72% share in 2025 because every sequencing run requires library preparation kits, flow cells, reagents, and cartridges that are purchased repeatedly. Instrument placements create a long stream of recurring orders, and higher throughput machines consume larger volumes of reagents. Vendors protect this revenue through validated workflows, which makes consumables the most stable part of the market and a major contributor to profits. Reagent rental and bundled supply agreements tie laboratories to preferred suppliers.
Services are expected to register the fastest growth, with a CAGR of 21.52% from 2026 to 2035. Hospitals, small research groups, and biotechnology firms outsource genome sequencing and analysis to avoid capital spending and staffing challenges. Clinical laboratories also expand rapid and long-read offerings as demand rises. Instruments remain essential for large centers, but outsourcing is attracting a growing set of buyers. Quality accreditation, clear pricing, and fast reporting help providers win repeat business from hospitals and drug developers alike.
By Workflow, Sequencing Dominates Whole Genome Sequencing Market; Data Analysis to Register Fastest Growth.
The sequencing step accounted for a 53.05% share in 2025 because it consumes the instruments and reagents that carry the largest costs in the workflow. Throughput gains from new platforms and rising sample counts keep spending high, and laboratories invest in additional capacity to meet demand from research programs and clinical testing. Pre-sequencing preparation, including extraction and library construction, supports this step and is increasingly automated. Automation in library preparation also adds spending as laboratories reduce hands-on time.
Data analysis is expected to register the fastest growth, with a CAGR of 20.82% from 2026 to 2035. Alignment, variant calling, annotation, and interpretation require software and compute that scale with every genome produced. Cloud platforms, artificial intelligence, and clinical decision tools shorten turnaround times and reduce manual review. As sequencing becomes cheaper, analysis represents a larger proportion of the cost of delivering a result. Interpretation tools for clinicians also reduce the need for scarce specialist review time.
By Application, Human Genomes Dominate Whole Genome Sequencing Market; Microbial Sequencing to Register Fastest Growth.
Human applications held a 63.80% share in 2025 because clinical diagnosis, cancer research, population studies, and pharmaceutical programs all concentrate on human DNA. Funding from governments and drug developers is directed mostly at human health, and hospitals are building services for rare disease and oncology. Large biobanks and national projects generate high volumes of genomes, which supports sustained demand across instruments, consumables, and analysis. Newborn and pediatric programs are adding further volume to this application each year across several regions.
Microbial sequencing is expected to register the fastest growth, with a CAGR of 20.47% from 2026 to 2035. Public health laboratories, hospitals, and food safety agencies use whole genome data to track outbreaks, identify resistance genes, and trace contamination. Lower costs make routine surveillance practical. Plant and animal sequencing also advance as breeders and researchers use genomes to improve crops and livestock, though they remain smaller than human and microbial work. Infection monitoring programs also add steady orders.
By End User, Academic and Research Institutes Dominate Whole Genome Sequencing Market; Hospitals and Clinics to Register Fastest Growth.
Academic and research institutes represented a 46.33% share in 2025 because universities, public laboratories, and genome centers run the largest sequencing projects and receive substantial government grants. They adopt new platforms early, evaluate methods, and generate data for population studies and basic research. Their purchasing power and technical expertise make them reference customers for instrument makers and shape standards used later by clinical laboratories. Core facilities there also train clinicians and technicians, which spreads skills into hospital laboratories over time.
Hospitals and clinics are expected to register the fastest growth, with a CAGR of 21.12% from 2026 to 2035. Genome testing for critically ill children, undiagnosed disease, and cancer is moving from research settings into routine care. Expanding payer coverage and hospital genomics units support steady volumes. Pharmaceutical and biotechnology companies remain large buyers, using genomes in discovery and trials, but clinical adoption is expanding faster. Several health systems are opening in-house genomic medicine units with dedicated sequencers.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
89.40% |
|
Europe |
United Kingdom |
27.65% |
|
Asia Pacific |
China |
38.12% |
|
Latin America |
Brazil |
46.78% |
|
Middle East & Africa |
Saudi Arabia |
33.91% |
North America Whole Genome Sequencing Market
North America held the largest share of the market at 47.28% in 2025, supported by large research budgets, early clinical adoption, and a concentration of instrument makers and sequencing service providers. The United States accounted for most regional demand, with a 2025 value of USD 1.20 Billion, and is expected to grow at a CAGR of 18.84% from 2026 to 2035. Expanding academic medical centers and state programs continue to add sequencers each year, and commercial testing laboratories compete aggressively for hospital and physician referrals.
Federal research funding, large biobank projects, and a growing list of state Medicaid programs that cover rapid genome sequencing for infants keep volumes rising. Pharmaceutical developers in the region commission large cohorts, while commercial laboratories invest in long-read and high-throughput capacity. Competition among instrument makers lowers prices, which helps hospitals and independent laboratories expand genome testing. Demand is also supported by strong venture investment in genomics companies, which funds clinical studies and accelerates product launches across the region over the coming decade.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Whole Genome Sequencing Market
Europe represents the second-biggest regional market, being fueled by the national genomics initiatives, public healthcare system and academic research. Most of the regional expenditure comes from the UK, Germany, France and the Netherlands. Population studies and newborn sequencing projects produce large patient cohorts, and the genomics testing starts to be integrated into the health care pathways for rare diseases and oncology through national health care systems. Even small countries in Northern and Eastern Europe become participants in cross-border initiatives of genomic data sharing, which increases their participation and the likelihood of sequencing orders in the future. Reimbursement pilots also provide additional impetus.
Regulation plays an important role, as the requirements of in vitro diagnostics and data protection necessitate the development of a validated workflow and proper management of the consent. Collaboration of hospitals, universities and sequencing companies increases access to sequencing, while the laboratories of Europe are among the first adopters of the new platforms. Companies providing services of high-throughput sequencing become widespread due to the demand from research communities. Public funding of rare disease networks provides further demand for diagnostic sequencing, while cross-border sample exchange stimulates standardized approaches to sequencing.
Asia Pacific Whole Genome Sequencing Market
APAC region is predicted to grow rapidly at a CAGR of 21.42% during the period from 2026 to 2035. Genome projects involving population-level genomic sequencing are underway in China, India, Japan, and South Korea, as well as expansion of hospital genomics infrastructure. Domestic players expand their activities, and there is governmental encouragement of manufacturing sequencers and reagents by domestic firms to decrease dependency on imports. Also, governmental funding for manufacturing of domestic sequencing equipment benefits local suppliers and provides purchasers with more options in terms of cost-efficient solutions.
Data from thousands of genomes in India National Genome Project are accessible for use for researchers, along with similar projects in other countries. Growing awareness of oncology and rare diseases, increasing number of private hospitals, and investments in biotechnology boost the growth. Australia and Singapore are advanced countries in clinical sector with many research collaborations and application of long-read platforms. In addition, Japan and South Korea contribute to demand through national biobank and clinical genomics programs. Southeast Asian countries develop their first sequencing centers.
Latin America Whole Genome Sequencing Market
Latin America is a small but emerging market, with Brazil and Mexico accounting for most spending. Academic centers and public research institutes lead adoption, using genome sequencing for infectious disease surveillance, agriculture, and population studies. Private diagnostic laboratories are starting to offer clinical genome testing, though high prices and limited reimbursement keep volumes modest. Pharmaceutical trials in the region increasingly include genomic analysis, which brings additional demand for sequencing from contract research organizations and laboratories. Private laboratories in Sao Paulo are leading early clinical offerings.
Many laboratories rely on sequencing services from international providers or on shared core facilities. Governments in Brazil, Chile, and Argentina are funding genomics initiatives, and regional collaborations help build skills and infrastructure. Falling prices per genome should gradually widen access, and distributors continue to expand service networks for instruments and reagents. Mexico is investing in genomic medicine centers, and private hospitals in major cities are beginning to market genome testing to families seeking answers for rare conditions. Training exchanges with European and North American centers are also helping skills development.
Middle East & Africa Whole Genome Sequencing Market
The Middle East & Africa accounts for the lowest market share but is gaining interest with Gulf states developing national genome projects and precision medicine facilities. The largest investments in the region come from Saudi Arabia and the United Arab Emirates and focus on studying inherited diseases prevalent in these populations via genomics. Sub-Saharan Africa's main player remains South Africa. Turkey and Egypt also develop sequencing infrastructure via their university hospitals, while Qatar and Kuwait make investments into national genome projects that will help in collaborating with other centers globally.
The adoption of genomics into public health labs in the region continues amid various international collaborations and training. Limited infrastructure and trained personnel outside major cities hinder the market development here; thus, many projects here depend on external sequencing providers. The development of the market is expected to be steady from low levels due to the construction of genomic medicine facilities in the hospitals. The collaborations with international instrument suppliers give access to high-quality devices and technical and training support; thus, the region can increase test menus at its laboratories.
Competitive Landscape
The competitive landscape combines dominant short-read platform makers, long-read specialists, new entrants with lower-cost instruments, and service providers that sequence samples for clients. Leading suppliers compete on cost per genome, accuracy, read length, throughput, and the strength of their software ecosystems, while service providers compete on turnaround time, clinical accreditation, and price. Concentration is moderate, because one supplier holds the largest installed base while several challengers are gaining placements.
Strategies center on lowering the cost of a genome, extending platforms into clinical use, and building software that turns raw data into reports. Companies pursue partnerships with hospitals and national programs, acquire complementary technologies, and seek regulatory clearances for diagnostic versions of their instruments.
Whole Genome Sequencing Market Industry Leaders
1. Illumina: Leading supplier of short-read sequencing, including the NovaSeq X series, library preparation kits, and DRAGEN analysis software for clinical and research genomes.
2. MGI Tech: China-based maker of DNBSEQ sequencers, including the T7+ high-throughput system, and sample preparation automation sold across Asia, Europe, and other regions.
3. Pacific Biosciences: Developer of HiFi long-read sequencing on the Revio and Vega systems, used for structural variant detection and clinical long-read genomes.
4. Oxford Nanopore Technologies: UK developer of nanopore sequencers, including the PromethION and P2i, which read long fragments of DNA and RNA in real time.
5. Element Biosciences: U.S. instrument maker whose AVITI platforms offer high-accuracy short-read sequencing for research and, in Europe, diagnostic use.
Companies Covered in this Report
- Illumina
- MGI Tech
- Pacific Biosciences
- Oxford Nanopore Technologies
- Element Biosciences
- Ultima Genomics
- Roche
- GeneDx
- Novogene
- Psomagen
- Macrogen
- Azenta Life Sciences
- Revvity
- BaseClear
Recent Industry Developments
- January 2026: Oxford Nanopore Technologies unveiled the P2i and MK1D instruments and announced a chief executive succession effective at the end of March 2026.
- February 2026: Illumina launched TruPath Genome, a workflow with on-flow-cell preparation for faster whole genome sequencing.
- February 2026: Ultima Genomics launched the UG200 series and Solaris 2.0 workflows for high-throughput whole genome sequencing.
- February 2026: Element Biosciences introduced the VITARI benchtop sequencing platform.
- March 2026: MGI Tech brought the DNBSEQ-T7+ high-throughput sequencer to the European market at Analytica 2026.
- June 2026: Roche launched the AXELIOS 1 sequencing platform based on sequencing by expansion for research use.
- July 2026: BaseClear became the first Ultima certified service provider in Europe.
- August 2026: Pacific Biosciences upgraded the Vega system to SPRQ-Nx chemistry and appointed a new chief executive.
Scope and Research Methodology
This report defines the Whole Genome Sequencing Market as the commercial value of instruments, consumables, software, and services used to determine the complete DNA sequence of human, plant, animal, and microbial genomes. Targeted panels, exome sequencing, microarrays, and transcriptome-only sequencing are excluded. Values are stated in USD at manufacturer selling prices for instruments and consumables and at the fee billed for services. The base year is 2025 and the forecast runs from 2026 to 2035. Direct-to-consumer ancestry tests that rely on genotyping arrays are excluded as well, because they do not read the complete genome.
Primary research comprised interviews with genomics core facility directors, clinical geneticists, laboratory managers, procurement officers, bioinformaticians, and executives at instrument makers and sequencing service providers. Secondary research drew on public genome program reports, regulatory records, funding databases, company filings, product catalogs, and scientific publications. Installed bases and run volumes were linked to research funding and clinical testing in each country, then converted to value using reagent consumption and price points. Each interview followed a structured guide covering sequencing volumes, instrument utilization, reagent contracts, outsourcing patterns, and adoption barriers, and responses were coded by region and by laboratory type so that patterns could be compared across countries.
A bottom-up build by product, workflow, and country was cross-checked against a top-down view based on genomics spending and sequencing capacity. Forecasts apply growth rates by segment that reflect falling prices, clinical coverage, program funding, and platform launches, with scenarios for regulatory change. Regional shares were validated against instrument placements and program budgets, and the five regions sum to the global figure. Findings were reviewed by internal analysts and external experts before release. Where estimates differed, analysts revisited assumptions on run volumes and pricing and consulted additional experts until the figures converged. Draft figures were stress-tested through sensitivity analysis.
Whole Genome Sequencing Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.84 Billion |
| Market Size by 2035 | USD 16.34 Billion |
| CAGR | CAGR of 19.12% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product and Service (Instruments, Consumables, and Services) • By Workflow (Pre-Sequencing, Sequencing, and Data Analysis) • By Application (Human, Plant, Animal, and Microbial) • By End User (Academic and Research Institutes, Hospitals and Clinics, Pharmaceutical and Biotechnology Companies, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Illumina, MGI Tech, Pacific Biosciences, Oxford Nanopore Technologies, Element Biosciences, Ultima Genomics, Roche, GeneDx, Novogene, Psomagen, Macrogen, Azenta Life Sciences, Revvity, BaseClear |

Frequently Asked Questions
The market was valued at USD 2.84 Billion in 2025 and is estimated at USD 3.38 Billion in 2026. It is forecast to reach USD 16.34 Billion by 2035.
The market is projected to expand at a CAGR of 19.12% from 2026 to 2035.
North America led with a 47.28% share in 2025, while Asia Pacific is the fastest-growing region, with a CAGR of 21.42% from 2026 to 2035.
Consumables held the largest share, at 56.72% in 2025, because every sequencing run requires kits, flow cells, and reagents.
Hospitals and clinics are expected to record the fastest growth, with a CAGR of 21.12% from 2026 to 2035.
