
X-ray Inspection System Market Report Scope & Overview:
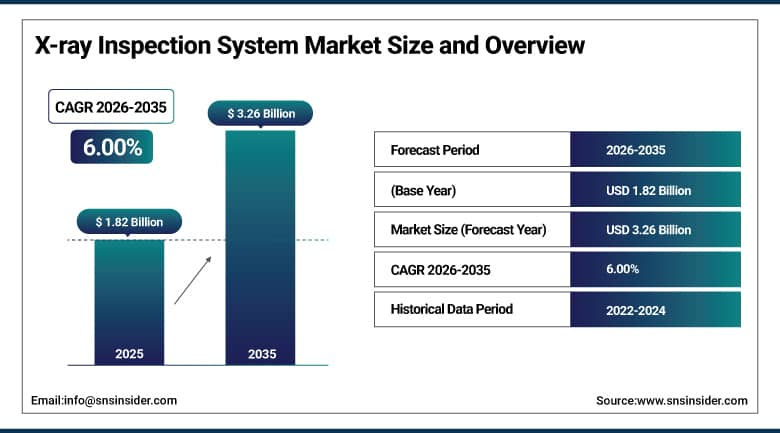
The X-ray Inspection System Market was valued at USD 1.82 Billion in 2025 and is expected to reach USD 3.26 Billion by 2035, growing at a CAGR of 6.00% from 2026-2035.
The X-ray Inspection System Market is expanding as manufacturers use X-ray imaging to find hidden defects, foreign objects and assembly errors without damaging products. Systems range from compact cabinet units for circuit boards to inline machines for packaged food and large computed tomography cells for castings and batteries. Demand is supported by tighter quality rules, rising electronics density and growth in electric vehicle production. Digital detectors, photon-counting sensors and artificial intelligence software are improving detection accuracy, while automation is moving inspection from sampling to full production lines.
⮞In January 2025, the International Organization for Standardization published ISO 15708-2:2025, the third edition of its standard on principles, equipment and samples for industrial X-ray computed tomography. A refreshed international standard supports consistent use of CT inspection across industries.
To Get More Information On X-ray Inspection System Market - Request Free Sample Report
X-ray Inspection System Market Trends
-
Photon-counting and dual-energy detectors improving detection of low-density contaminants
-
AI-based automatic defect recognition replacing manual image review
-
Inline computed tomography for batteries, castings and electronic components
-
Compact, lower-shielding cabinet systems for electronics and medical devices
-
Cloud connected image databases linking inspection results with production data
U.S. X-ray Inspection System Market Outlook
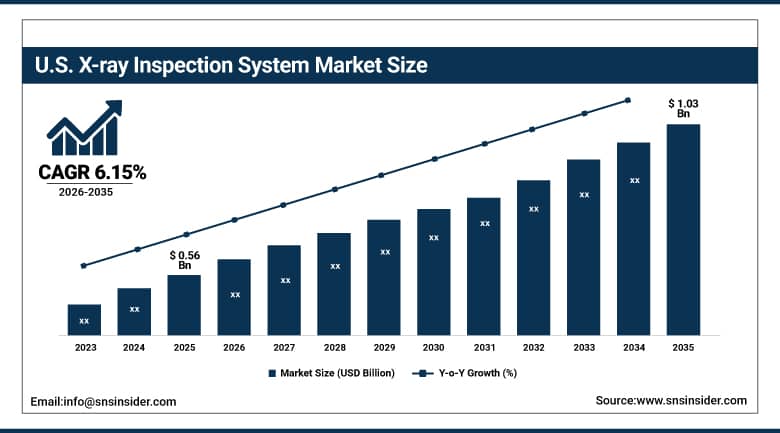
The U.S. X-ray Inspection System Market was valued at USD 0.56 Billion in 2025 and is expected to reach USD 1.03 Billion by 2035, growing at a CAGR of 6.15% from 2026-2035.
The U.S. X-ray Inspection System Market is the largest national market, supported by a deep base of aerospace, defense, medical device, electronics and food manufacturers with strict quality requirements. Growth in semiconductor packaging, battery plants and reshored electronics production is increasing demand for high-resolution and inline systems. Food processors rely on X-ray equipment to detect bone, glass and metal fragments. High equipment prices, radiation safety rules and a shortage of trained operators moderate faster adoption.
⮞In January 2026, U.S. Customs and Border Protection told Congress that it had deployed 405 large-scale non-intrusive inspection systems as of 2 December 2025. Large public deployments show the scale of X-ray scanning in U.S. trade.
X-ray Inspection System Market Segment Analysis
-
By Technology, the Digital Imaging segment dominated the X-ray Inspection System Market with approximately 51.72% share in 2025, while the Computed Tomography segment is the fastest growing with a CAGR of approximately 7.80%.
-
By Dimension, the 2D segment dominated the X-ray Inspection System Market with approximately 58.40% share in 2025, while the 3D segment is the fastest growing with a CAGR of approximately 7.60%.
-
By Offering, the Hardware segment dominated the X-ray Inspection System Market with approximately 66.30% share in 2025, while the Software segment is the fastest growing with a CAGR of approximately 8.10%.
-
By End Use, the Oil & Gas segment dominated the X-ray Inspection System Market with approximately 24.50% share in 2025, while the Electronics & Semiconductors segment is the fastest growing with a CAGR of approximately 8.40%.
By Technology, Digital Imaging Dominates the X-ray Inspection System Market and Computed Tomography Grows Fastest
Digital imaging leads because flat-panel and line-scan detectors deliver real-time images, lower radiation doses and easy storage compared with film. Manufacturers use digital systems for weld checks, castings, packaged food and electronic assemblies, and image software supports automatic pass or fail decisions. Replacement of film and computed radiography setups continues across inspection laboratories.
Computed tomography is advancing fastest as buyers want full three-dimensional views of internal features, voids and wall thickness. Battery makers, additive manufacturing plants and precision casting shops use CT for dimensional checks that 2D images cannot provide. Faster reconstruction, inline cells and cloud analysis are reducing scan times and widening use beyond laboratories.
⮞In July 2026, SEMI forecast global assembly and packaging equipment sales of USD 6.7 billion for 2026 as part of a record outlook for semiconductor equipment. Advanced packaging growth supports demand for X-ray inspection of hidden solder and die connections.
By Dimension, 2D Dominates the X-ray Inspection System Market and 3D Grows Fastest
Two-dimensional systems lead because they are fast, lower in cost and well suited to inline inspection of packaged goods, welds and circuit boards. Operators can identify foreign matter, missing components and fill errors in a single projection, and compact designs fit into existing lines. Decades of use have built a large installed base and trained workforce.
Three-dimensional inspection is growing faster as products become denser and defects must be located precisely in depth. Laminography and CT-based tools resolve overlapping features in stacked chips, batteries and complex castings. Easier operation and automated analysis are bringing 3D tools from metrology rooms to production floors, although cost remains a hurdle for smaller plants.
⮞According to the World Customs Organization, four scanners at the Port of Douala in Cameroon each process up to 100 containers per hour, and in 2025 nearly 90% of corrected declarations in one sector were identified from scanner images. Image-based screening is gaining credibility with regulators.
By Offering, Hardware Dominates the X-ray Inspection System Market and Software Grows Fastest
Hardware accounts for most spending because buyers purchase X-ray tubes, detectors, shielding cabinets, conveyors and handling systems as capital equipment. Microfocus tubes and high-sensitivity detectors carry premium prices, and customers often add several lines in one project. Replacement cycles and capacity additions in electronics, automotive and food plants keep orders steady.
Software is growing fastest as inspection value shifts to image analysis, defect libraries and reporting. Machine learning models reduce false rejects, while connections to manufacturing execution systems turn images into traceable quality records. Vendors are moving toward subscription analytics, remote support and update packages that increase recurring revenue beyond the initial machine sale.
⮞In July 2026, press reports citing the Transportation Security Administration said that CT checkpoint scanners had reached hundreds of U.S. airports. Large public deployments of CT screening are building familiarity with image-based analysis.
By End Use, Oil & Gas Dominates the X-ray Inspection System Market and Electronics & Semiconductors Grows Fastest
Oil and gas leads because pipelines, pressure vessels, valves and welds must be examined to prevent leaks and meet code requirements. Operators use radiography during construction and maintenance, and digital detectors are replacing film in field and plant settings. Safety regulations and aging infrastructure keep inspection programs in place across upstream, midstream and refining sites.
Electronics and semiconductors are the fastest growing end use as chips, boards and connectors become smaller and more densely packed. Ball grid arrays, stacked dies and power modules hide their solder joints, so X-ray is the only practical way to verify them. Expansion of advanced packaging, automotive electronics and battery assembly keeps adding inspection stations.
⮞In February 2026, Food Safety Magazine reported, citing U.S. Department of Agriculture data, that foreign material was the leading cause of USDA recalls in 2025, at 13 of 42. Contaminant detection is a key reason food processors invest in X-ray systems.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
87.31 |
|
Europe |
Germany |
22.46 |
|
Asia Pacific |
China |
36.74 |
|
Latin America |
Brazil |
43.18 |
|
Middle East & Africa |
Saudi Arabia |
27.63 |
North America X-ray Inspection System Market Insights
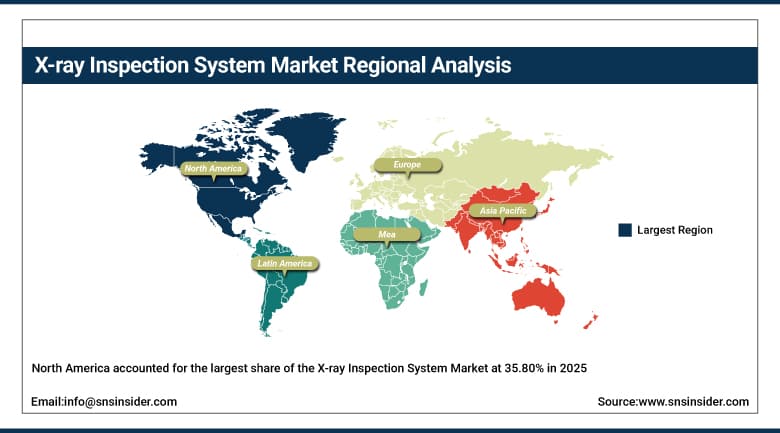
North America accounted for the largest share of the X-ray Inspection System Market at 35.80% in 2025, led by the United States and followed by Canada. The region has strong aerospace, defense, medical device and food manufacturing sectors, along with early adoption of AI-based image analysis. Government programs for border security and critical infrastructure add to equipment demand.
Reshoring of electronics and battery production is creating new plants that install inline inspection from the start. Long approval cycles for radiation-emitting equipment, high prices and limited availability of qualified operators moderate growth, particularly among small manufacturers.
⮞In June 2024, the Canada Border Services Agency deployed a mobile X-ray scanner in the Greater Toronto Area and reported more than 1,300 stolen vehicles intercepted that year. Mobile scanners expand the use of X-ray in Canadian trade enforcement.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific X-ray Inspection System Market Insights
Asia Pacific held about 26.70% of the X-ray Inspection System Market in 2025 and is projected to be the fastest growing region, at a CAGR of 7.90% over 2026-2035. China, Japan, South Korea, India and Taiwan lead, supported by the world's largest electronics, semiconductor and battery manufacturing base.
Local equipment makers compete on price while global suppliers focus on high-resolution and CT systems. Rising automotive electrification, food safety regulation and expanding packaging capacity add demand. Price sensitivity and uneven enforcement of inspection standards in smaller economies limit speed.
⮞In 2025, Japan Customs reported large-scale X-ray inspection equipment at 15 locations across 13 ports, cutting a one-container scan from about two hours to about ten minutes. Faster scanning supports the case for further investment.
Europe X-ray Inspection System Market Insights
Europe held about 24.30% of the X-ray Inspection System Market in 2025, led by Germany, the United Kingdom, France, Italy and Switzerland. The region is home to leading equipment makers and a dense base of automotive, aerospace, machinery and packaged food producers that depend on non-destructive testing.
Strict food safety rules, product liability standards and electric vehicle battery plants support steady demand. Energy costs and slower industrial investment in some countries restrain growth, while sustainability goals favor systems that reduce scrap through early defect detection.
⮞In December 2025, the European Commission's interim evaluation of its Customs Control Equipment Instrument reported that more than 900 pieces of customs control equipment had been acquired by the end of 2024. EU funding is renewing screening equipment at borders.
MEA & Latin America X-ray Inspection System Market Insights
Latin America and the Middle East and Africa together hold about 13.20% of the X-ray Inspection System Market. In Latin America, Brazil, Mexico, Argentina and Chile lead, with demand from automotive plants, food exporters and port and customs modernization.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Qatar and South Africa lead, with oil and gas, mining and airport projects driving purchases. Budget limits, import dependence and a limited number of service centers restrain growth in several markets.
⮞In October 2026, Chile's national customs service placed two new scanner trucks into operation at Valparaiso and Arica, raising its fleet from 10 to 13 non-intrusive units. Port modernization is lifting equipment demand across Latin America.
Market Dynamics
Growth Drivers: Electric Vehicle Battery Production and Electronics Miniaturization Drive Growth in the X-ray Inspection System Market
Electric vehicle battery production is a major driver. Cells, modules and welded busbars must be checked for misalignment, voids, foreign particles and electrode defects, because a single flaw can cause fires or early failure. Battery manufacturers are installing inline X-ray stations and CT sampling cells, and demand rises as new gigafactories open in Asia, Europe and North America.
Electronics miniaturization adds further momentum. Smaller packages, stacked chips and higher component density hide solder connections from optical inspection, so X-ray is needed for process control. Automotive electronics, power modules and data center hardware need near-zero defect rates, which leads manufacturers to adopt automated inspection with image analysis.
⮞In May 2026, the International Energy Agency projected that close to 30% of cars sold in 2026 will be electric. Rising electric vehicle output increases the number of batteries and power electronics that need inspection.
Restraints: High Equipment Costs and Radiation Safety Compliance Restrain Growth in the X-ray Inspection System Market
High equipment costs restrain growth. Microfocus tubes, large detectors, lead shielding and CT cells can cost many times more than optical systems, and payback depends on scrap reduction and recall avoidance. Small and mid-sized manufacturers often postpone purchases or rely on outsourced inspection services, which slows unit sales.
Radiation safety compliance adds further limits. Operators must obtain licenses or registrations, train staff, monitor doses and maintain shielding, and rules differ by country. Public programs that install large scanners also face schedule slips and availability challenges, which show the practical difficulty of deploying and maintaining X-ray assets at scale.
⮞In January 2026, the U.S. Government Accountability Office reported that deployment of U.S. Customs and Border Protection scanners is expected to finish in December 2029, later than the 2027 congressional target, with FY2024 availability at 90% against a 95% goal. Deployment and uptime remain real challenges.
Opportunities: Semiconductor Packaging Investment and Component Manufacturing Programs Create Opportunities in the X-ray Inspection System Market
Semiconductor packaging investment offers a major opportunity. Advanced packaging methods such as chiplets, high-bandwidth memory stacks and fan-out designs rely on hidden interconnects that only X-ray and CT can verify. As packaging plants expand in Asia, the United States and Europe, they need inline systems with higher resolution and faster throughput.
Component manufacturing programs create a second opportunity. Governments are funding local production of printed circuit boards, passive components and modules to reduce import reliance, and new plants buy inspection equipment as part of their quality systems. Suppliers that offer training, local service and financing can win long-term relationships with these first-time buyers.
⮞In October 2025, India's Ministry of Electronics and Information Technology approved seven electronic component projects under its Electronics Components Manufacturing Scheme, with investment of about USD 630 Billion and more than 5,000 direct jobs. Local component production is creating new inspection demand.
Recent Developments:
-
2026: Mettler-Toledo launched the X56 DXD dual-energy photon-counting X-ray system with AI. It detects low-density contaminants such as rubber and plastic at up to 500 products per minute.
-
2026: Hexagon signed an agreement to acquire Waygate Technologies from Baker Hughes for USD 1.45 billion. Waygate's radiography unit supplies 2D X-ray and 3D CT systems to aerospace, automotive, electronics and battery customers.
-
2026: Lumafield launched Neptune Performance metrology-grade CT and Triton Performance inline CT systems. The inline model can complete full volumetric reconstruction in as little as ten seconds per part.
X-ray Inspection System Market Key Players are:
-
Mettler-Toledo International Inc.
-
Comet Group (Comet Yxlon)
-
Nikon Corporation (Industrial Metrology)
-
Carl Zeiss AG
-
Waygate Technologies (Baker Hughes)
-
Viscom SE
-
Loma Systems (Illinois Tool Works)
-
Sesotec GmbH
-
Minebea Intec GmbH
-
Ishida Co., Ltd.
-
Shimadzu Corporation
-
Lumafield, Inc.
-
Nordson Corporation
-
North Star Imaging Inc.
-
Saki Corporation
X-ray Inspection System Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.82 Billion |
| Market Size by 2035 | USD 3.26 Billion |
| CAGR | CAGR of 6.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Film-based Imaging and Digital Imaging (Computed Radiography (CR), Direct Radiography (DR), Computed Tomography (CT))) • By Dimension (2D and 3D) • By Offering (Hardware, Software, and Services) • By End Use (Oil and Gas, Electronics and Semiconductors, Automotive, Aerospace and Defense, Food and Beverage, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Mettler-Toledo International Inc., Comet Group (Comet Yxlon), Nikon Corporation (Industrial Metrology), Carl Zeiss AG, Waygate Technologies (Baker Hughes), Viscom SE, Loma Systems (Illinois Tool Works), Sesotec GmbH, Minebea Intec GmbH, Ishida Co., Ltd., Shimadzu Corporation, Lumafield, Inc., Nordson Corporation, North Star Imaging Inc., Saki Corporation |

Frequently Asked Questions
Key players include Mettler-Toledo, Comet Yxlon, Nikon, ZEISS, Waygate Technologies, Viscom, Loma Systems, Sesotec, Minebea Intec, Ishida, Shimadzu, Lumafield, Nordson, North Star Imaging and Saki.
Key opportunities include semiconductor packaging inspection, component manufacturing programs, AI defect recognition, inline CT and fast-growing Asia Pacific demand.
Growth in electric vehicle battery production and electronics miniaturization, which require internal defect detection, is the main growth factor.
By Technology, the Digital Imaging segment dominated the market in 2025 with an estimated 51.72% share, supported by real-time imaging and lower radiation doses.
North America dominated the market with a share of 35.80% in 2025, driven by aerospace, defense, medical device and food manufacturing sectors.
