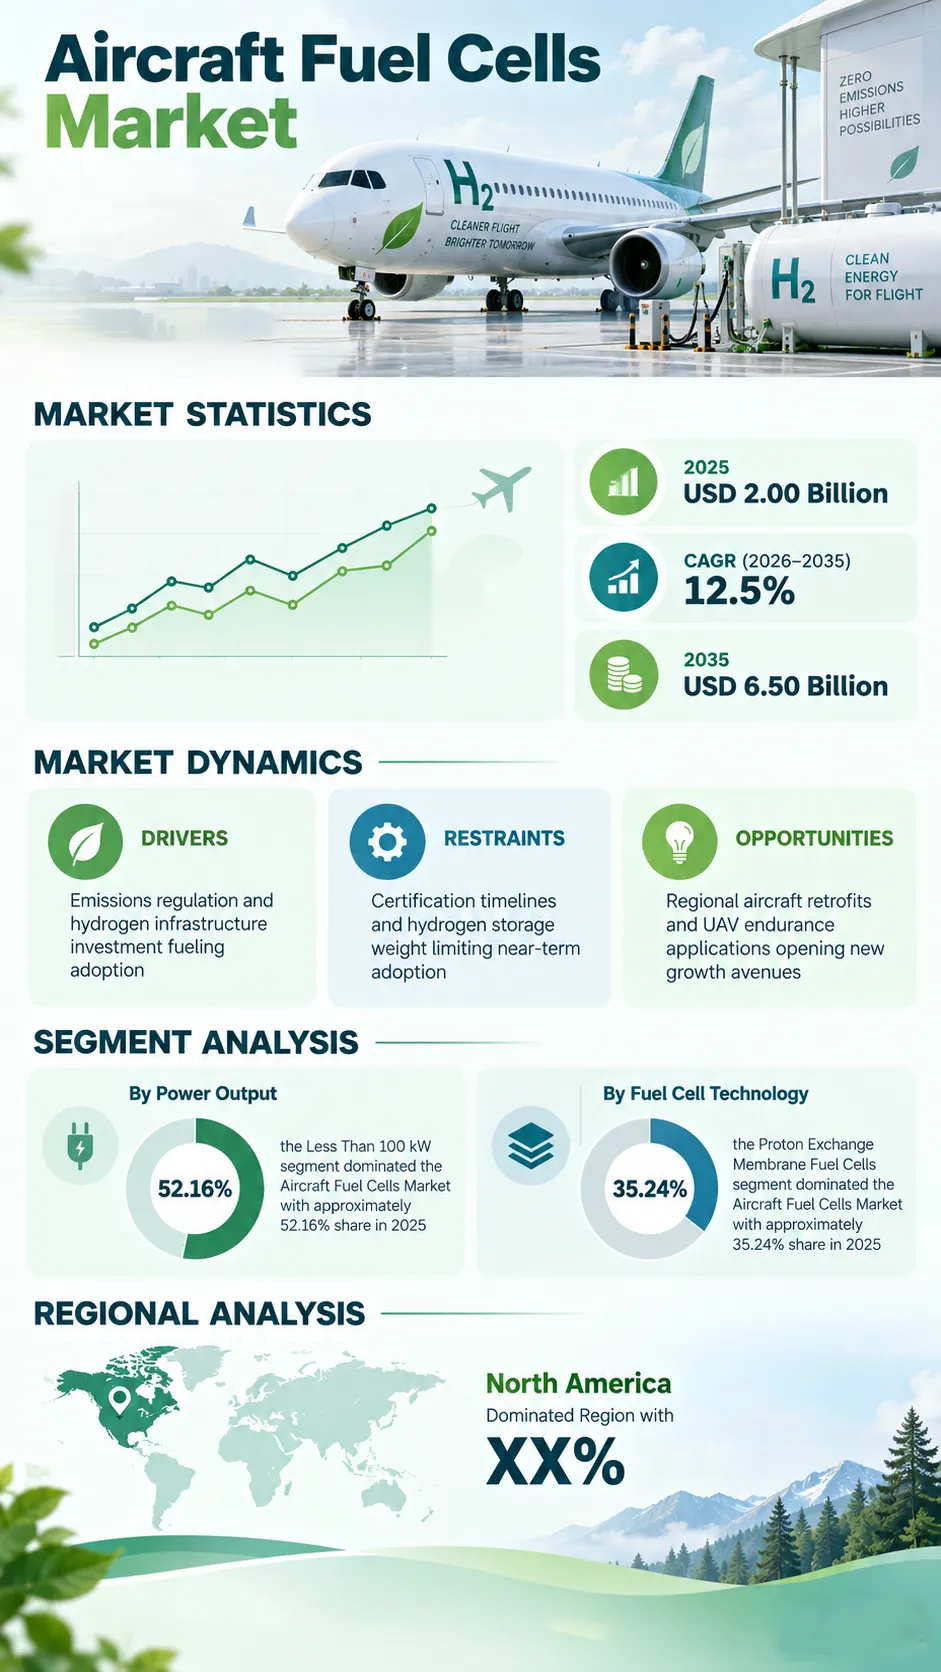
The global Aircraft Fuel Cells Market is set for rapid expansion as certification milestones bring hydrogen-electric aviation closer to genuine commercial service. “According to a recent study by SNS Insider, the global Aircraft Fuel Cells Market Size valued at USD 2.00 billion in 2025, is anticipated to grow to USD 6.50 billion by 2035, registering a CAGR of 12.5% over the 2026-2035 forecast period.”
There have been rapid changes within fuel cell and hydrogen storage technology over time, due to which many developers aiming at improved power output and certification readiness can take advantage of this trend. This includes the need for more resilient, higher-power fuel cell systems that give regulators and airline partners confidence in propulsion reliability, across a wide range of applications from auxiliary power units to genuine flight propulsion. This applies in situations where aircraft fuel cells are used across commercial, military, and unmanned aerial vehicle applications.
Developers are constantly working to improve certification readiness and power output in order to meet various needs of airlines and aerospace manufacturers worldwide.
To Get Detailed Insights on the Aircraft Fuel Cells Market – Request a Sample Report
Emissions Regulation and Hydrogen Infrastructure Ecosystems Create New Demand
The aircraft fuel cells market has evolved from small demonstrator programs into a broader mix of auxiliary power, propulsion, and UAV applications approaching genuine commercial readiness. The growing investment in liquid hydrogen storage, certification-intent system design, and multi-platform development has required the development of more efficient and reliable production systems.
New fuel cell and storage approaches can improve power output, reduce regulatory uncertainty, and expand the range of applications aircraft fuel cells can serve. This gives developers the possibility to be more effective when reaching airline and government partners and strengthening claims around safety and operational reliability.
Fuel cell developers, airlines, and regulatory agencies are increasingly cooperating due to the growing interest in developing future solutions for zero-emission aircraft propulsion.
Key Market Findings Highlight High-Growth Segments
The proton exchange membrane fuel cells segment dominated all categories in the aircraft fuel cells market share with a market revenue share of approximately 35.24% in 2025 due to its low operating temperature and lighter overall system weight.
The fastest growing category is expected to be the solid oxide fuel cells segment, which will grow at a CAGR of approximately 14.8% through 2035. This will be possible owing to higher electrical efficiency and fuel flexibility for larger aircraft auxiliary power applications.
By application, auxiliary power unit held the largest share of total market revenue at approximately 44.07% in 2025 due to its established, lower-certification-burden use case. The propulsion segment will see the fastest growth in revenue generation at a CAGR of approximately 16.8%.
Regional trends show North America leading with approximately 31.56% revenue share in 2025, while Asia Pacific is expected to register a fast growth trajectory driven by increasing investment in alternative energy technologies across the region.
Certification Progress, Power Scaling, and Application Diversification Gain Importance
In this regard, developers have been looking at aircraft fuel cell platforms that would make their certification pathways clearer, their power output higher, and their applications more diverse.
Innovation in liquid hydrogen storage, certification-intent system design, and multi-platform development has been making it possible for companies to come up with platforms that can meet increasingly demanding regulatory and airline-partner expectations. In addition to that, increasing emphasis on graduated power-class progression is also making it possible for companies to find solutions that support eventual larger-aircraft propulsion.
Such trends are likely to become even more prominent in the future.
North America Leads Amid Clear Regulatory Direction and Airline Investment
North America represented approximately 31.56% share of global market revenue in 2025 and was the largest regional market, owing to clear FAA regulatory direction and significant airline investment commitments from carriers moving from pre-orders to definitive purchase agreements. In addition, Asia Pacific is expected to register a fast growth trajectory during the forecast period, propelled by increasing investment in alternative energy technologies across the region's fast-growing economies.
On the other hand, Europe represented a meaningful share of global market revenue in 2025, aided by France's position as home to Airbus and strong European aerospace engineering expertise supporting hydrogen propulsion research.
Leading Companies Drive Innovation and Competition
The environment continues to stay very dynamic since players continue innovating on fuel cell and hydrogen storage technology as well as forming partnerships in order to enhance their position in the industry.
Some of the major companies that operate in the global aircraft fuel cells market are Ballard Power Systems Inc., ZeroAvia, Inc., Plug Power Inc., Intelligent Energy Limited, Airbus SE, HES Energy Systems, Doosan Mobility Innovation, H2FLY GmbH, Universal Hydrogen Co., and Pratt & Whitney.
An SNS Insider Analyst Sushant Kadam commented, “The steady progress toward FAA and UK CAA certification milestones is creating a genuine, if still capital-intensive, pathway to commercial hydrogen-electric aviation. Developers that successfully combine certification execution, hydrogen storage innovation, regional aircraft retrofit strategy, and strong airline backing will be best positioned to capitalize on emerging opportunities across propulsion, auxiliary power, and UAV endurance applications.”
About the Author
Get in touch