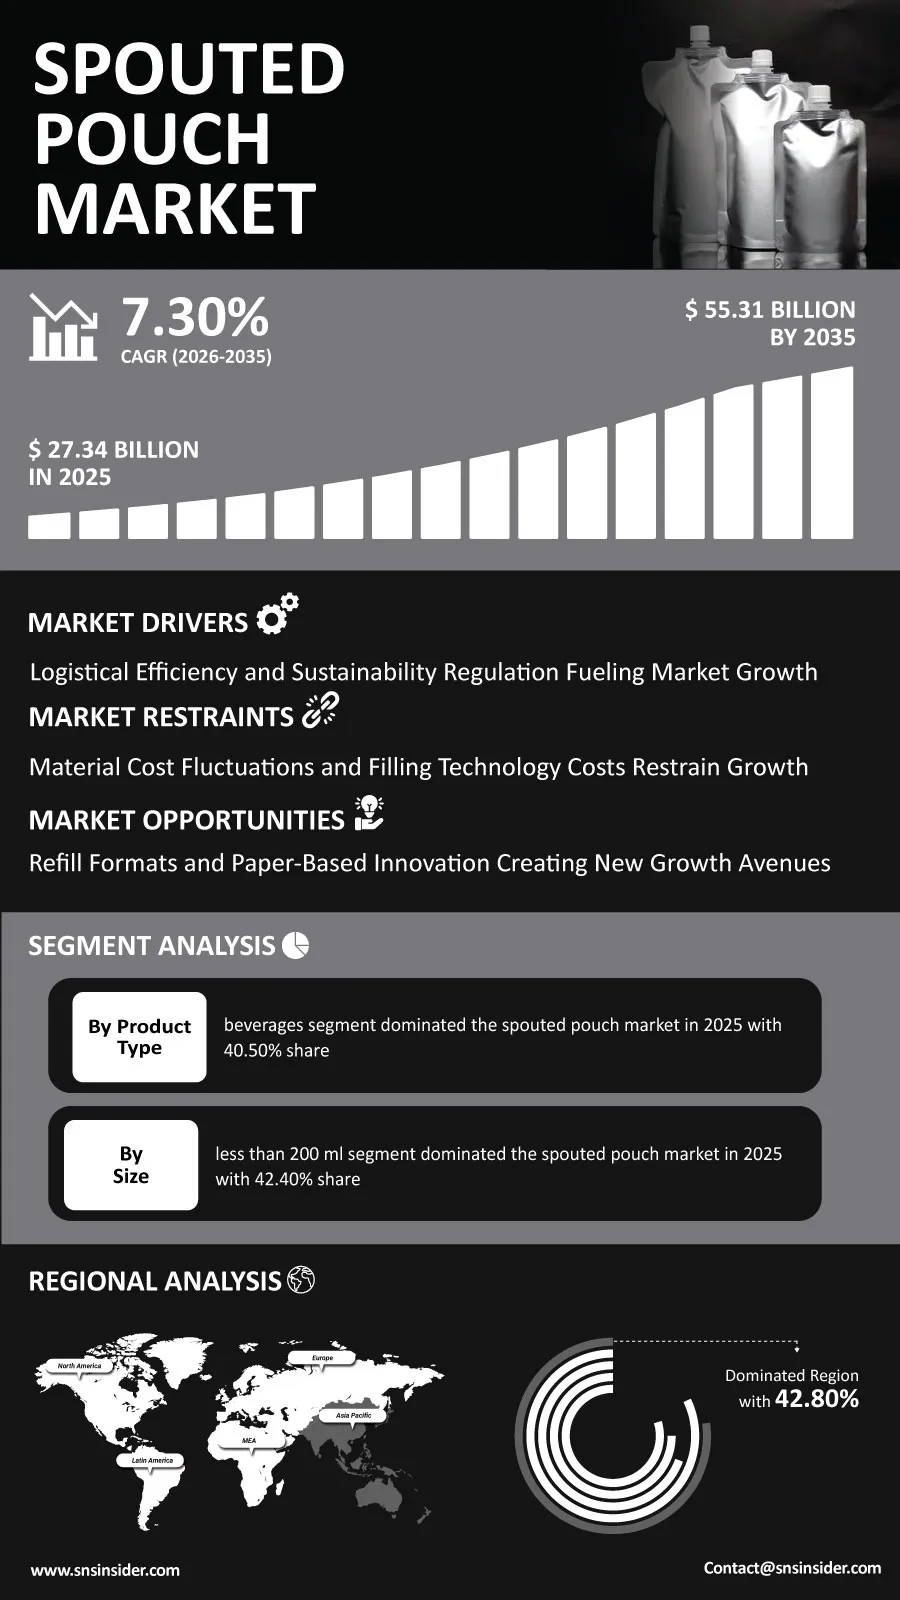
The global Spouted Pouch Market is on a steady growth path through 2035, as logistical efficiency and tightening plastic packaging regulation continue reshaping how liquid and semi-liquid products get packaged worldwide. “According to a recent study by SNS Insider, the global Spouted Pouch Market size valued at USD 27.34 billion in 2025, is anticipated to grow to USD 55.31 billion by 2035, registering a CAGR of 7.30% over the 2026-2035 forecast period.”
A spout pouch solves a genuinely practical problem better than almost any packaging alternative, it delivers a bottle's pourability and resealability while shipping and storing at a fraction of the weight and volume. That efficiency advantage translates directly into cost and carbon savings that are becoming harder for brands to ignore as both fuel costs and packaging regulation keep tightening.
Material innovation is where most of the competitive activity is concentrated right now, as manufacturers race to develop mono-material and paper-based structures that can match multilayer laminate performance while clearing increasingly strict recyclability requirements.
To Get Detailed Insights on the Spouted Pouch Market – Request a Sample Report
Mono-Material and Paper Innovation Reshape Category Standards
Where multilayer laminate structures once dominated spout pouch construction by default, mono-material polyethylene and polypropylene formats are increasingly capturing brand attention as recyclability regulation tightens across major markets.
This shift is changing how packaging engineers approach pouch design, since barrier performance, seal integrity, and spout compatibility now all have to be achieved within a single recyclable material rather than through multilayer lamination.
Paper-based pouch innovation is pushing this trend even further, particularly for dry products where fiber-based structures can achieve genuine kerbside recyclability that plastic, even mono-material plastic, often cannot match in current recycling infrastructure.
Key Market Findings Highlight High-Growth Segments
Beverages held the largest share of the Spouted Pouch Market in 2025, at 40.50%, reflecting the format's ability to bridge flexible film's low cost with a rigid bottle's genuine functionality.
Personal care is the fastest-growing product type, expanding at a 9.20% CAGR, pulled forward by refill formats that let consumers reuse existing rigid bottles rather than buying new ones.
By size, less than 200 ml led with 42.40% share in 2025, while pouches above 1000 ml are growing fastest, at a 9.60% CAGR, as bulk refill formats for home care and personal care products expand.
Plastic remained the dominant material at 68% share, but paper is growing fastest, at a 10.20% CAGR, as brands respond to tightening plastic packaging regulation with fiber-based alternatives.
Recyclability Credentials and Logistical Efficiency Anchor Competitive Positioning
Brands are increasingly evaluating pouch suppliers on recyclability credentials and demonstrated carbon footprint reduction nearly as much as on cost, particularly in markets with tightening plastic packaging tax regimes.
Investment in mono-material and paper-based structures is becoming a genuine competitive differentiator among larger manufacturers, while suppliers without that investment increasingly compete only in commodity, multilayer laminate segments.
This divide is expected to sharpen further as more markets adopt Europe-style plastic packaging taxes and extended producer responsibility regulation.
Asia Pacific Leads as Latin America Grows Fastest
Asia Pacific holds the largest share of global market revenue, fueled by China's raw material cost advantage and the region's high overall packaged food and beverage consumption. Latin America, meanwhile, is growing fastest, propelled by expanding packaged food and beverage manufacturing across Brazil and Mexico and rapidly growing e-commerce distribution.
North America holds a steady, mature share as well, anchored by the United States, the world's largest individual national market for spouted pouches.
Leading Companies Drive Innovation and Competition
Competition in this market centers on mono-material innovation, paper-based development, and filling technology capability nearly as much as on price, with major players investing heavily in recyclable material research to meet tightening regulatory requirements.
Some of the major companies that operate in the global spouted pouch market are Amcor plc, Mondi Group, Sealed Air Corporation, Smurfit Westrock plc, Sonoco Products Company, ProAmpac LLC, AptarGroup, Inc., Gualapack S.p.A.
An SNS Insider Analyst Himanshu Sharma commented, “Spout pouches have moved well past being a niche convenience format, brands now need genuine recyclability credentials alongside the logistical efficiency that made the category popular in the first place, and the manufacturers capturing the fastest-growing parts of this market are the ones investing in mono-material and paper-based innovation rather than relying on multilayer laminate structures. As plastic packaging regulation keeps tightening globally, recyclable pouch capability is becoming a genuine competitive advantage.”
About the Author

Get in touch