
Adaptive Traffic Control System Management Market Report Scope & Overview:
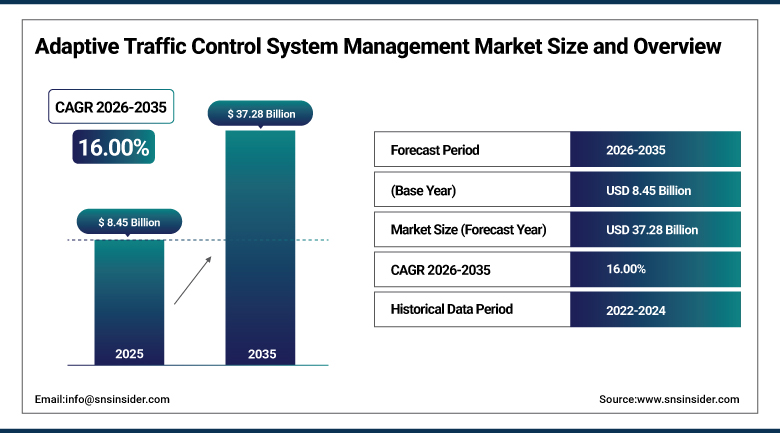
The Adaptive Traffic Control System Management Market was valued at USD 8.45 Billion in 2025 and is expected to reach USD 37.28 Billion by 2035, growing at a CAGR of 16.00% from 2026-2035.
The Adaptive Traffic Control System Management Market is expanding as cities and highway agencies replace fixed-time signal plans with systems that adjust timings in response to live traffic conditions. Growth is supported by urbanization, rising congestion, road safety and emissions goals, and the spread of connected vehicles, cameras, radar and cloud analytics at intersections. Vendors supply controllers, detection hardware, central management software and services, and many now add artificial intelligence for signal optimization and performance monitoring. Published valuations vary with scope, ranging from roughly USD 7 billion to USD 11.5 billion for 2025 where they refer specifically to adaptive control, while broader intelligent traffic management estimates are considerably higher.
⮞On May 20, 2026, Miovision announced an end-to-end traffic signal optimization solution on its Miovision One cloud platform, combining Mateo, a generative AI traffic engineering assistant, with a Signal Optimizer that uses Highway Capacity Manual methods and an AI-based genetic algorithm, and a Controller Manager that pushes approved timing plans to multi-vendor controllers using NTCIP. The company stated that the integrated workflow can speed retiming by up to 50%, moving agencies from infrequent manual retiming toward proactive optimization.
To Get more information Adaptive Traffic Control System Management Market - Request Free Sample Report
Adaptive Traffic Control System Management Market Trends
- Cloud-based management platforms replacing standalone central servers
- AI and machine learning for automated signal timing optimization
- Video analytics and radar detection replacing in-ground loops
- Connected vehicle and vehicle-to-infrastructure data feeding signal control
- Priority for transit, emergency and freight vehicles at intersections
- Performance monitoring and automated retiming reports for agencies
U.S. Adaptive Traffic Control System Management Market Outlook
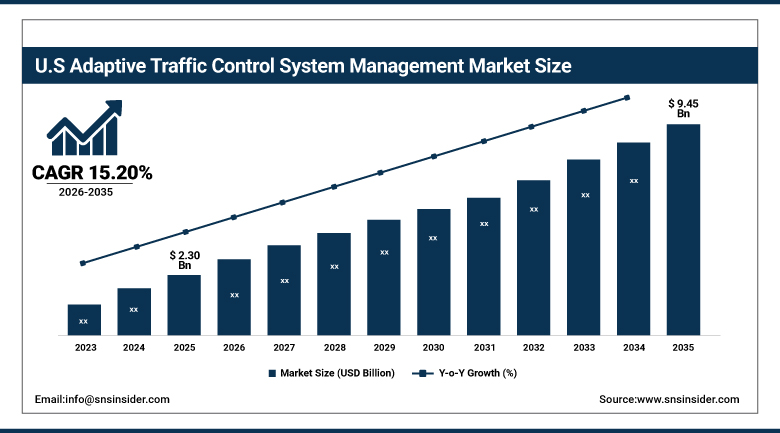
The U.S. Adaptive Traffic Control System Management Market was valued at USD 2.30 Billion in 2025 and is expected to reach USD 9.45 Billion by 2035, growing at a CAGR of 15.20% from 2026-2035.
The U.S. Adaptive Traffic Control System Management Market is the largest national market, supported by a vast network of signalized intersections operated by state and municipal agencies, federal funding for congestion and safety programs and a mature base of suppliers such as Econolite, Cubic, Iteris and Siemens Mobility. Agencies increasingly retrofit corridors with adaptive control and connected infrastructure to improve travel times and reduce crashes. Procurement is fragmented across thousands of local jurisdictions, and budget cycles and tariffs on imported hardware influence the pace of deployments.
⮞In June 2025, Siemens Mobility integrated AI-driven predictive algorithms into its Sitraffic Symphony platform in a partnership with the city of Dallas, allowing signal timing to anticipate demand rather than only react to it. The deployment illustrates how U.S. cities are using software upgrades to extract more capacity from existing intersections without major road construction.
Adaptive Traffic Control System Management Market Segment Analysis
- By Type, the SCATS segment dominated the Adaptive Traffic Control System Management Market with approximately 31.42% share in 2025, while the Others (AI-Based Systems) segment is the fastest growing with a CAGR of approximately 21.30%.
- By Component, the Hardware segment dominated the Adaptive Traffic Control System Management Market with approximately 47.30% share in 2025, while the Software segment is the fastest growing with a CAGR of approximately 19.40%.
- By Deployment, the Cloud-Based segment dominated the Adaptive Traffic Control System Management Market with approximately 41.86% share in 2025, while the Hybrid segment is the fastest growing with a CAGR of approximately 21.20%.
- By Application, the Streets and Urban Arterials segment dominated the Adaptive Traffic Control System Management Market with approximately 52.18% share in 2025, while the Highways segment is the fastest growing with a CAGR of approximately 18.70%.
- By End User, the Government Bodies segment dominated the Adaptive Traffic Control System Management Market with approximately 58.73% share in 2025, while the Private Enterprises segment is the fastest growing with a CAGR of approximately 18.30%.
By Type, SCATS Dominates the Adaptive Traffic Control System Management Market and Others Grows Fastest
SCATS remains the dominant system type within the Adaptive Traffic Control System Management Market, characterized by decades of deployment across Australia, Asia and parts of North America and Europe, and by its proven ability to adjust cycle lengths and splits using detector data. Its long installed base creates steady revenue from expansions, licenses and maintenance, and agencies value the familiarity of established operating procedures. This system type benefits from a large community of trained traffic engineers and from integration with a wide range of controllers and detection equipment.
Newer AI-based and proprietary systems, grouped under others, are emerging as the fastest-growing type, driven by machine learning methods that optimize networks using video, radar and connected vehicle data. These platforms often run in the cloud, update continuously and can be deployed at lower upfront cost than traditional central systems. Vendors such as Miovision and others offer analytics-led approaches that appeal to agencies with limited engineering staff, and competition from these entrants is encouraging established suppliers to add AI capabilities to their own platforms.
By Component, Hardware Dominates the Adaptive Traffic Control System Management Market and Software Grows Fastest
The hardware continues to be the largest constituent part, considering that it entails the provision of the controllers, sensors, cameras, radars, communication devices, and control cabinets at each and every managed intersection. The replacement of aged controllers and extension of corridors lead to repeated purchases, while procurement processes usually involve standard compliant hardware from authorized vendors. While software becomes increasingly important, the hardware continues to constitute the major part of initial project cost, taking into account the tariff issues and transportation costs of foreign hardware.
Software is the most rapidly expanding element due to central management systems, which enable analytics and optimizations that are upgradeable without changing the field equipment. Examples of cloud-based products include Swarco Pulse and Miovision One that remotely measure and control intersection performance by detecting errors and proposing timings. Subscription pricing allows spreading payments out over time. With standardization of controllers, competition will increasingly depend on software capabilities and performance, resulting in recurring revenue through licenses, analytics, and managed services.
By Deployment, Cloud-Based Dominates the Adaptive Traffic Control System Management Market and Hybrid Grows Fastest
Cloud-based deployment is the leading mode in recent assessments, supported by the appeal of lower infrastructure maintenance, remote access and easier updates for agencies that lack large data centers. Cloud platforms support centralized monitoring of signals across jurisdictions and simplify the sharing of data with navigation providers, emergency services and planners. Vendors promote subscription pricing and rapid feature releases, and many new deployments in smaller cities begin with cloud tools rather than building central servers. Open data interfaces make cloud tools attractive to agencies.
Hybrid architectures are growing fastest because agencies want local controllers to continue operating if connectivity fails while still benefiting from cloud analytics and optimization. Safety-critical signal control generally needs deterministic local operation, so a split between edge processing at the intersection and cloud-based management provides resilience and security. Cybersecurity concerns and data sovereignty rules also encourage hybrid designs, and they allow gradual migration from legacy central systems without disrupting traffic operations. Fail-safe fallback plans are a standard requirement in tenders.
By Application, Streets and Urban Arterials Dominates the Adaptive Traffic Control System Management Market and Highways Grows Fastest
Streets and urban arterials account for the largest share, because most signalized intersections are located on city networks where congestion, pedestrian safety and transit priority are pressing concerns. Adaptive control on arterial corridors can improve travel times and reduce stops, and benefits are visible to the public. Municipal projects often combine adaptive signals with detection upgrades and communications, and large cities such as those using SCATS or SCOOT have extended systems across hundreds of intersections. Pedestrian and cyclist detection is increasingly bundled into arterial projects.
Highways are growing fastest as agencies deploy adaptive ramp metering, variable speed limits and incident-responsive signal timing on interchanges and freeway-adjacent corridors. Rising freight volumes and the need to manage queues near ramps encourage investment, and connected vehicle data provides new visibility into speeds and incidents. Coordination between highway operators and city signal systems at interchanges is increasing, which extends adaptive control beyond downtown grids and supports demand for integrated management platforms. Dedicated lanes for buses and freight also benefit from coordinated control.
By End User, Government Bodies Dominates the Adaptive Traffic Control System Management Market and Private Enterprises Grows Fastest
Government bodies, including municipal traffic departments and state transportation agencies, are the primary purchasers because they own and operate most signalized intersections. Funding comes from public budgets, federal grants and smart city programs, and procurement follows formal tendering. Agencies prioritize reliability, interoperability and long-term support, which favors established suppliers, and demonstrated congestion and safety improvements help justify spending in competitive budget environments. Long contract terms with maintenance obligations give suppliers predictable revenue, and national road safety strategies increasingly mandate performance reporting for signal networks, which encourages the adoption of monitoring software.
Private enterprises are growing fastest as toll operators, logistics campuses, ports, airports, mines and industrial parks adopt adaptive control to manage internal traffic and access roads. Private developers also fund signal upgrades as part of large mixed-use projects, and concession operators of highways use adaptive systems to maximize throughput. These customers tend to decide faster than public agencies and are more willing to test cloud and AI-based offerings, which gives innovative vendors an entry point for broader adoption. Corporate fleets also value shorter queue times.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
78.46 |
|
Asia Pacific |
China |
39.28 |
|
Europe |
Germany |
24.73 |
|
Middle East & Africa |
United Arab Emirates |
37.59 |
|
Latin America |
Brazil |
49.12 |
North America Adaptive Traffic Control System Management Market Insights
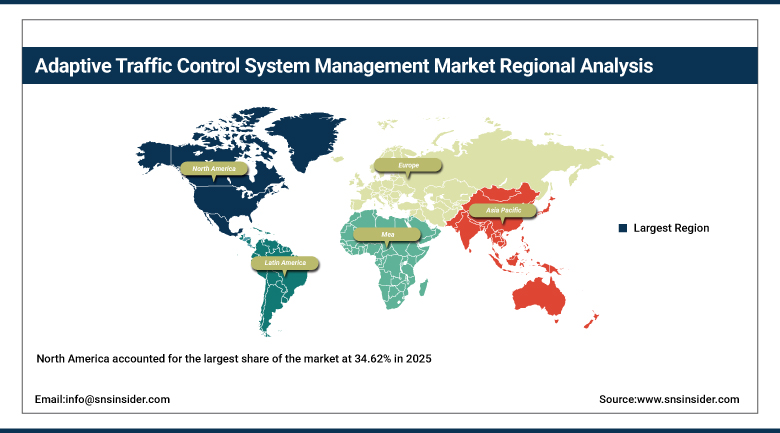
North America accounted for the largest share of the market at 34.62% in 2025, supported by extensive signalized road networks, established suppliers and federal programs that fund congestion mitigation and safety improvements. The United States leads, with Canada adding demand through cities adopting cloud-based signal management. The region is projected to expand at a robust pace through 2035, as agencies replace aging controllers and add connected infrastructure. Canada adds adoption through provincial funding for transit priority and urban safety projects in Toronto, Vancouver and Calgary.
Suppliers including Econolite, Cubic, Iteris, Siemens Mobility and Miovision compete across the region, and Econolite completed its acquisition of the signal analytics start-up StreetPulse in March 2025. Fragmented procurement across thousands of jurisdictions, limited engineering staff at small agencies and tariffs on imported electronics slow some projects, although grant funding and growing interest in vehicle-to-infrastructure communication continue to support steady deployment. The Infrastructure Investment and Jobs Act continues to channel federal funds toward intelligent transportation projects, and state departments increasingly specify performance-based requirements for signal operations.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Adaptive Traffic Control System Management Market Insights
Asia Pacific is the fastest-growing region, advancing at a CAGR of 18.60% during 2026-2035. China leads through large-scale smart city projects and local suppliers such as Huawei and Hikvision, while India, Japan, South Korea, Australia and Southeast Asia add growth. Australia is the birthplace of SCATS, and its states continue to operate large adaptive networks. Japan and South Korea contribute advanced intelligent transportation programs with high detector density, and Australia's New South Wales operates one of the world's largest adaptive networks.
The rapid process of urbanization and increasing ownership of vehicles along with congestion issues in cities like Bengaluru, Jakarta, and Bangkok are contributing to the need for adaptive control, and local suppliers like Efftronics and EFKON are making their own contributions in this regard. Smart city projects and expressway projects of the government are financing the technology, but there is standardization issue, limited budget, and mixed traffic environment with large number of two wheelers that create problems in terms of detection and optimization.
Europe Adaptive Traffic Control System Management Market Insights
Europe held significant share of the market in 2025. Germany leads, followed by the United Kingdom, France, Spain, Italy and the Netherlands, supported by established suppliers including Siemens Mobility, Kapsch TrafficCom, Swarco, PTV Group, Lacroix and Indra. The United Kingdom's SCOOT system, developed for urban networks, remains widely deployed. Eastern European countries are modernizing aging signal networks with support from European structural funds, which broadens the regional customer base.
European cities pursue low-emission zones, public transport priority and road safety targets, which favor adaptive control that reduces stops and emissions. Swarco introduced its cloud-based Swarco Pulse system in association with T-Mobile Austria in January 2025. This shows that there is a trend towards connected management. Strong data privacy policies, developed networks with already optimized signal strength, and tight city budgets limit the growth rate in comparison to Asia Pacific. The directive on intelligent transport systems and the cooperative-ITS program promote data sharing between cars and signals.
MEA & Latin America Adaptive Traffic Control System Management Market Insights
The Middle East and Africa contributed significantly in the market in 2025. The United Arab Emirates and Saudi Arabia lead through smart city programs and large infrastructure investments in Dubai, Abu Dhabi and Riyadh, while South Africa and Egypt add demand through urban congestion management. Gulf projects often adopt integrated intelligent transportation platforms from European and Asian suppliers. Egypt's new administrative capital and Saudi Arabia's giga-projects include planned intelligent traffic networks designed with adaptive control from the outset.
Latin America is projected to grow at a stronger growth rate. Brazil leads, with Mexico, Colombia, Chile and Argentina adding projects in major cities such as São Paulo, Mexico City and Bogotá. Congestion costs are high and municipalities are modernizing signal networks, but budget volatility, procurement delays and limited technical capacity restrain the rate of adoption across the region. Public-private partnerships and concession models are used in several countries to fund signal upgrades, while international suppliers are opening regional offices to support projects and training.
Market Dynamics
Growth Drivers: Urban Congestion and Demand for Safer, Lower-Emission Roads
Urban congestion is a leading reason why adaptive traffic signals are in such high demand. With the increasing population and number of cars in the cities, the time-dependent traffic plan becomes outdated after a few years and re-timing manually is costly and happens rarely. An adaptive system is capable of adjusting timings on the go and is capable of decreasing delay and stops on the corridor. The optimization of signals is considered to be one of the cheapest solutions when the need arises to increase mobility without expanding the road network.
Safety and environmental objectives reinforce this demand. Rising road casualties in several countries have prompted programs for intersection safety, while cities seek to lower fuel consumption and emissions by reducing stop-and-go driving. Technology advances, including inexpensive radar and video detection, cloud analytics and connected vehicle data, make adaptive control easier to deploy. Government funding for smart city and sustainable transport initiatives further supports investment, and large events encourage temporary and permanent upgrades.
Restraints: High Upfront Cost, Legacy Infrastructure and Cybersecurity Risks
High upfront cost and legacy infrastructure restrain adoption. Adaptive control requires reliable detection, communications and modern controllers, and many agencies operate older equipment that must be replaced before benefits can be realized. Project costs can be significant for large corridors, and tariffs on imported signal-processing and control hardware have increased infrastructure costs in some markets. Smaller municipalities with limited budgets often defer upgrades or choose simpler coordinated timing plans instead.
Moreover, cybersecurity threats and talent deficits pose additional problems. Networked signals and cloud-based systems increase the threat exposure, requiring agencies to secure and comply. Adaptive systems are operated by traffic engineers that can tweak, analyze, and debug the algorithms, but not all agencies have such personnel. Fragmentation of standards and vendor lock-in problems pose risks for purchasers, and inadequate detection capabilities may lower the benefits of the technology.
Opportunities: AI-Based Optimization, Connected Vehicles and Cloud Services
AI-based optimization offers a significant opportunity because it can automate retiming, identify poorly performing intersections and recommend improvements with limited manual effort. Generative AI assistants, such as the tools Miovision announced in May 2026, allow engineers to query data in natural language, which could widen adoption among agencies with small teams. Vendors that deliver measurable improvements in travel time and emissions can sell performance-based services and long-term software subscriptions.
Connected vehicles and cloud services provide additional opportunity. Vehicle-to-infrastructure communication and probe data from navigation providers give signals earlier information on approaching traffic, supporting transit and emergency priority and green wave strategies. Cloud platforms allow suppliers to manage multi-vendor fleets of controllers remotely, creating recurring revenue streams. Emerging markets in Asia, the Middle East and Latin America are building new networks, and suppliers offering scalable, low-cost solutions can capture early deployments.
Recent Developments:
- 2025: Econolite Group completed its acquisition of StreetPulse, a traffic signal analytics start-up. The acquisition adds performance monitoring and data analytics capabilities to Econolite's signal control portfolio.
- 2025 Swarco AG launched Swarco Pulse, a cloud-native traffic management platform developed in collaboration with T-Mobile Austria. The platform supports remote monitoring and management of signalized intersections.
- 2026: Kapsch TrafficCom launched its next-generation EcoTrafiX platform, integrating AI, connected-vehicle capabilities, predictive analytics, incident management, and traffic operations in a unified system.
Adaptive Traffic Control System Management Market Key Players are:
- Siemens Mobility GmbH
- Yunex Traffic
- Kapsch TrafficCom AG
- SWARCO AG
- Econolite Group, Inc.
- Cubic Corporation
- Iteris, Inc.
- PTV Group
- Q-Free ASA
- TransCore
- Miovision Technologies Inc.
- Indra Sistemas, S.A.
- Thales Group
- Huawei Technologies Co., Ltd.
- Lacroix Group
- Aldridge Traffic Controllers Pty Ltd
- Hangzhou Hikvision Digital Technology Co., Ltd.
- Efftronics Systems Pvt. Ltd.
- EFKON India
- Sumitomo Electric Industries, Ltd.
Adaptive Traffic Control System Management Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 8.45 Billion |
| Market Size by 2035 | USD 37.28 Billion |
| CAGR | CAGR of 16.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (SCATS, SCOOT, RHODES, ACS-Lite, OPAC, Others) • By Component (Hardware, Software, Services) • By Deployment (On-Premise, Cloud-Based, Hybrid) • By Application (Streets and Urban Arterials, Highways, Others) • By End User (Government Bodies, Transportation Authorities, Private Enterprises, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Siemens Mobility GmbH, Yunex Traffic, Kapsch TrafficCom AG, SWARCO AG, Econolite Group, Inc., Cubic Corporation, Iteris, Inc., PTV Group, Q-Free ASA, TransCore, Miovision Technologies Inc., Indra Sistemas, S.A., Thales Group, Huawei Technologies Co., Ltd., Lacroix Group, Aldridge Traffic Controllers Pty Ltd, Hangzhou Hikvision Digital Technology Co., Ltd., Efftronics Systems Pvt. Ltd., EFKON India, Sumitomo Electric Industries, Ltd. |

Frequently Asked Questions
Key players include Siemens Mobility, Yunex Traffic, Kapsch TrafficCom, Q-Free, TransCore, Miovision, and Huawei, among others.
Key opportunities include AI-based signal optimization, connected vehicle integration, cloud-based management subscriptions and new deployments in Asia Pacific, the Middle East and Latin America.
The major growth factor is rising urban congestion, combined with safety and emissions goals that push agencies to replace fixed-time signal plans with systems that adjust in real time.
By Type, the SCATS segment dominated the market with approximately 31.42% share in 2025, supported by its long deployment record and large installed base across multiple regions.
North America dominated the market with a share of 34.62% in 2025, supported by extensive signalized networks, federal safety and congestion funding and an established supplier base.
